 Follow Us on Google News
 Follow Us on Google Discover
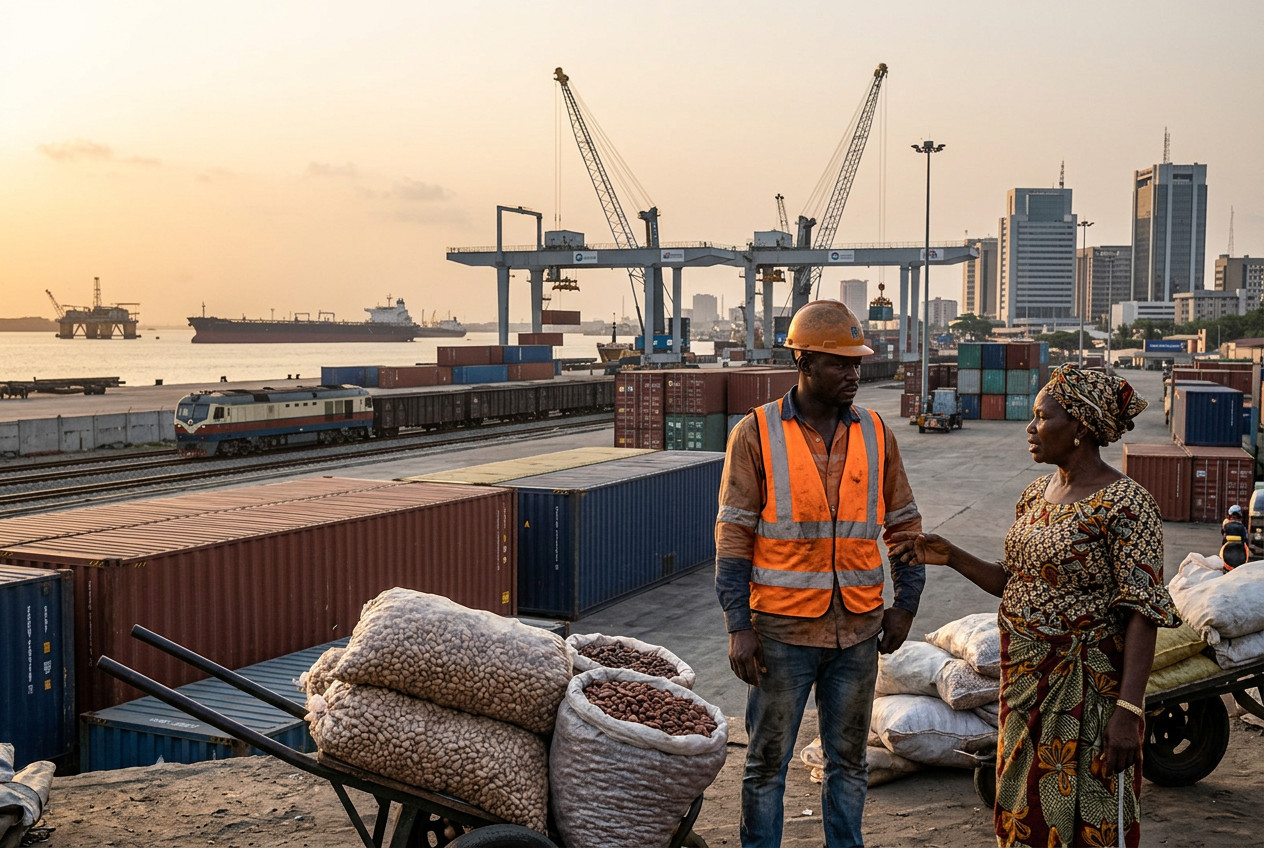
Nigeria does not suffer from a lack of foreign economic partners. China has become one of the country’s most important commercial partners. Europe remains a major source of trade, finance and development investment.
Yet beneath this expanding network lies a paradox.
Nigeria has become increasingly capable of attracting foreign investment into projects, zones and sectors that function even when the wider institutional environment does not. But the arrangements that make these investments work are not necessarily strengthening the institutions around them.
In other words, we are becoming better at building around weak institutions without becoming equally good at strengthening them.
Consider Nigeria’s relationship with China. China’s zero-tariff treatment for products from Nigeria and 52 other African countries took effect on May 1, 2026. Nigerian businesses now have greater access to one of the largest consumer markets in the world.
But our trade structure tells a less comfortable story. In the second quarter of 2026, China supplied more than 41 per cent of Nigeria’s imports. At the same time, Nigeria’s manufactured exports fell sharply year-on-year, while petroleum products continued to dominate what we sold abroad.
The problem is not that Nigeria trades too much with China. Access to Chinese capital, machinery, infrastructure and markets presents enormous opportunities. The question is what Nigeria is becoming capable of doing with those opportunities.
Are Nigerian firms becoming stronger suppliers? Are we acquiring technologies that allow more production to take place locally? Are the Nigerian institutions overseeing these investments becoming more capable?
Europe presents a somewhat different model but brings us back to the same questions. The European Union accounted for about 31 per cent of Nigeria’s foreign trade in 2025 and continues to expand investment through initiatives such as Global Gateway. European engagement often places greater formal emphasis on standards, sustainability, regulation and institutional development.
Yet whether the capital comes from Beijing, Brussels or elsewhere, Nigeria confronts the same reality: external investment can provide infrastructure and expertise, but the institutions needed to convert these into long-term national capability have to be built here.
We can see this already. Foreign companies have built and financed major infrastructure in Nigeria. Foreign investors operate factories and industrial facilities.
But familiar weaknesses remain: unreliable electricity, costly logistics, regulatory uncertainty, limited access to affordable finance and public institutions that often work much better for a major foreign-funded project receiving special attention than for the ordinary Nigerian firm trying to operate every day.
For decades, we have celebrated success in terms of how much investment comes in, how many agreements are signed, how many factories are built or how many billions of naira are attached to a project. This is not to say these numbers are not important. But they do not tell us whether these investments are changing what Nigeria itself is capable of producing, managing and sustaining.
The more important question should be, what can Nigeria do after the investment that it could not do before it?
This is what might be called institutional additionality.
An investment should leave behind more than a physical project and jobs. It should leave Nigerian engineers with greater expertise, Nigerian firms able to supply more sophisticated inputs, regulators better able to oversee an industry, workers with transferable skills and institutions more capable of managing the next project.
Instead, what we often see are small islands of efficiency surrounded by the same problems that existed before the investment arrived.
We know what happens inside some of our industrial and special economic zones. Electricity is more reliable. Infrastructure is better organised. Customs and administrative processes sometimes move faster. Major investors receive the attention needed to resolve problems that could otherwise delay their operations.
Step outside those arrangements and the Nigerian manufacturer is back in a very different economy: generating electricity, struggling with logistics, paying high financing costs and navigating institutions that are often far less responsive.
That gap is the issue.
The success of these zones shows that Nigeria is capable of creating environments in which businesses can function. But those improvements have not spread far enough. We have created places where the Nigerian system works exceptionally well without sufficiently asking why the same reliability, responsiveness and administrative efficiency cannot become normal conditions outside them.
Research on Chinese-backed special economic zones in Nigeria points to this problem. A 2025 study found that inadequate infrastructure and weaknesses in the Nigerian state’s ability to formulate and implement effective rules were limiting the capacity of the zones to generate technology transfer and broader industrial benefits.
There is a difference between foreign investment occurring in Nigeria and foreign investment transforming Nigeria. The former brings capital. The latter changes capability to produce and manufacture. Nigeria has diversified the countries with which it does business without achieving comparable diversification in what it produces. We trade extensively with China. Europe remains a major commercial partner.
Yet petroleum continues to dominate exports while our dependence on imported manufactured goods remains substantial. We have, in effect, diversified our partners much faster than we have diversified our productive capabilities.
Opening another market does not automatically give Nigerian firms something competitive to sell there. A tariff concession is valuable only if domestic companies can produce at the quality, quantity and price required to take advantage of it. To compete favourably in the 21st century, Nigeria needs to become better at extracting long-term domestic capability from both.
When government grants incentives to a major investor, the conversation should extend beyond the amount invested and the number of jobs promised. We should know what Nigerian suppliers will eventually provide, what skills Nigerian workers will acquire, what technology will be transferred and what Nigerian agencies will learn from the project.
Where foreign engineering and managerial expertise is being used today, there should be a visible pathway through which Nigerians take on more of that work tomorrow. And if electricity, customs procedures and regulation can work efficiently inside a special economic zone, government should be asking what made those systems work there and how much of that efficiency can be extended to the rest of the economy.
We have built railways. The next question is whether Nigeria is becoming better at maintaining, managing and eventually developing railway infrastructure itself. We have attracted manufacturing investment. The question is whether Nigerian companies are moving into the supply chains around those factories or whether most sophisticated inputs will still be imported ten years from now.
Nigeria unquestionably needs foreign investment. Our infrastructure, employment and industrialisation needs are too large to suggest otherwise.
But attracting foreign capacity cannot become a permanent substitute for building our own.
The most valuable foreign investment is more than simply the project that succeeds while the foreign investor is here. It is the investment that leaves Nigerian firms, workers and institutions able to do more after it is completed. That should ultimately be how we judge Nigeria’s economic relationships with China, Europe and every other partner.
The true test of foreign investment is not simply what an investor builds in Nigeria. It is what Nigeria becomes capable of building after the investor leaves.
David MasagborDavid Masagbor, PhD, is a public policy researcher with interests in community development, development economics, educational equity, urban inequality and program evaluation. He earned his doctorate from Rutgers University–New Jersey, where his research examined institutional supports for underserved communities.