 Follow Us on Google News
 Follow Us on Google Discover
ACCI: Trade surplus should drive industrialisation, not complacency
The Federal Government has moved to make late payment of taxes more closely reflect prevailing market conditions, with taxpayers required to pay interest tied to benchmark rates from October 1, 2026.
Meanwhile, the Abuja Chamber of Commerce and Industry (ACCI) has urged the Federal Government to channel Nigeria’s growing trade surplus into industrialisation, non-oil export expansion and private investment, warning that the gains remain fragile as long as they depend largely on crude oil.
Under the new framework, interest on naira-denominated tax liabilities will be based on the Central Bank of Nigeria (CBN)’s Monetary Policy Rate (MPR) plus one percentage point, subject to a floor equivalent to the yield on 364-day Treasury Bills.
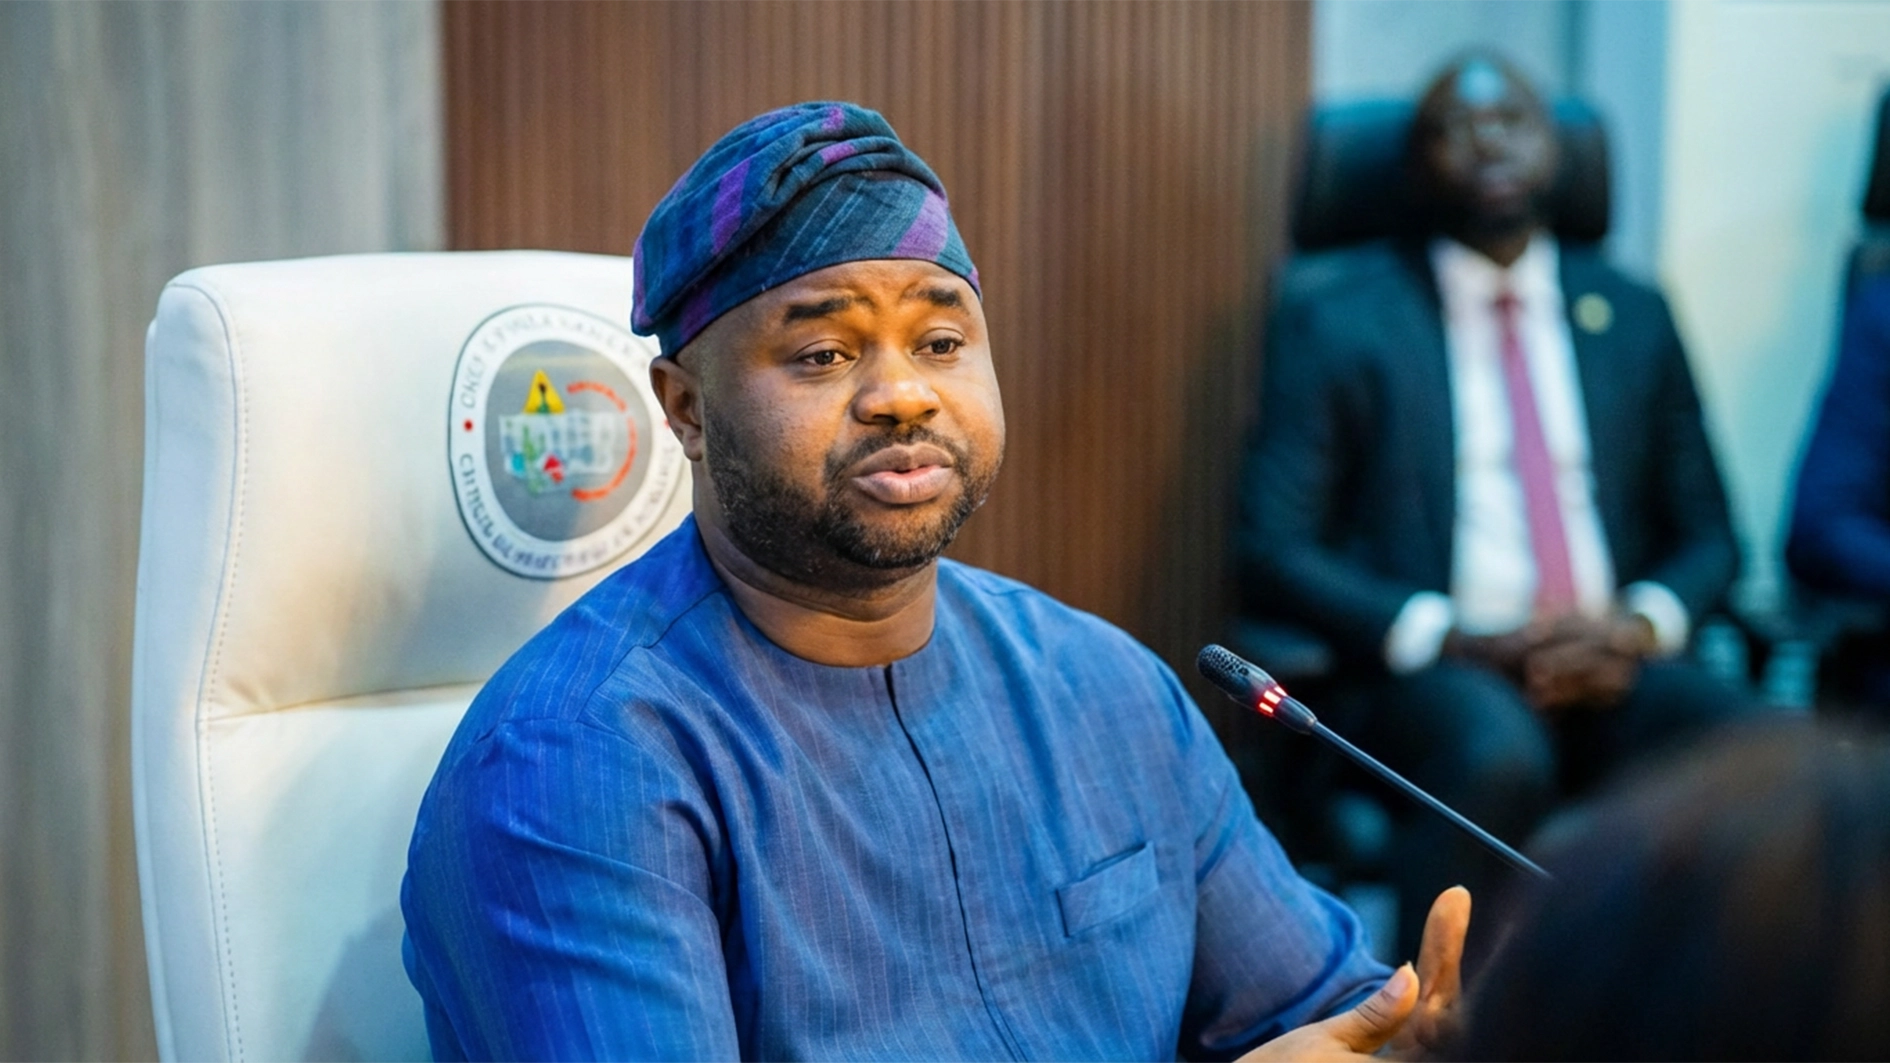
The Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, yesterday, issued the Nigeria Tax Administration (Interest on Late Payment of Tax) Order, 2026, pursuant to Section 65 of the Nigeria Tax Administration Act, 2025.
According to the Federal Ministry of Finance, the new framework replaces the previous five-percentage-point margin with a market-linked approach that covers tax authorities at the federal, state, and Federal Capital Territory (FCT) levels.
For tax liabilities denominated in foreign currency, the applicable interest rate will be the Secured Overnight Financing Rate (SOFR) plus six percentage points, with an official successor benchmark to apply if SOFR is discontinued.
Oyedele said the new arrangement was designed to ensure that delaying tax payments does not give taxpayers cheaper financing than is available in the market.
“Tax that is due belongs to the public. When it is paid late, the government may have to borrow to fill the gap, and the cost falls on everyone,” he said. “This Order ties the cost of late payment to real market rates, so that delaying tax does not become a cheaper form of credit than the market itself.”
The applicable interest rate will be reviewed monthly, with a single rate applying throughout each calendar month, based on the relevant benchmark as of the last business day of the preceding month.
The Nigeria Revenue Service (NRS) is required to publish the applicable rate on its website by the third business day of each month, while interest will be calculated daily on a simple-interest basis from the date the tax becomes due until payment.
The framework will apply to self-assessment and assessments administered by the NRS, as well as state and FCT internal revenue services.
Oyedele said the uniform approach would give taxpayers greater certainty over their liabilities, irrespective of the tax authority administering them.
“Every taxpayer, whether dealing with the NRS or a state revenue service, will know the rate in advance, see it published every month, and be charged in the same way,” he said.
The ministry, however, clarified that the new order does not replace the existing 10 per cent penalty for late payment provided under Section 65 of the Nigeria Tax Administration Act.
Consequently, taxpayers who default may face both the 10 per cent penalty and the applicable market-linked interest.
The relevant tax authorities may, however, waive penalties or interest where taxpayers can demonstrate good cause, in line with Section 66 of the Act.
The ministry said the new rates would apply to interest arising from October 1, including interest on taxes that became due before that date, while interest accrued before October 1 would remain subject to the rules in force at the time.
The order supersedes the 2017 notice regarding interest on unpaid taxes and all prior notices on the matter.
ACCI Director-General, Agabaidu Jideani, while reacting in Abuja to the latest merchandise trade figures from the National Bureau of Statistics (NBS), said the surplus could ease foreign exchange pressures and offer the economy a buffer, but cautioned against reading the import decline as proof of stronger domestic production.
The NBS figures showed total trade rising 19.13 per cent to N41.44 trillion in the second quarter of 2026, from N34.79 trillion in the first. The country posted a trade surplus of N12.60 trillion in the period, as exports rose and imports fell.
Jideani said lower imports could also reflect weak consumer demand and production constraints.
“The increase in the trade surplus largely reflected stronger crude oil exports and a contraction in import volumes,” he said.
He called for policies to direct gains into productive sectors such as agro-processing, light manufacturing, pharmaceuticals, solid minerals, and digital services, alongside affordable working capital for exporters, incentives for local content and value addition, and faster investment in gas and renewable energy.
Cutting the cost of power, logistics, multiple taxation and insecurity, he added, would be critical to helping businesses, especially small and medium enterprises, expand production and compete regionally. He pressed for stronger implementation of the African Continental Free Trade Area (AfCFTA), simplified export procedures and deeper integration of Nigerian firms into global value chains.
Ultimately, the ACCI said, sustaining the trade gains would require Nigeria to move beyond raw commodity exports toward producing and selling higher-value goods.