 Follow Us on Google News
 Follow Us on Google Discover
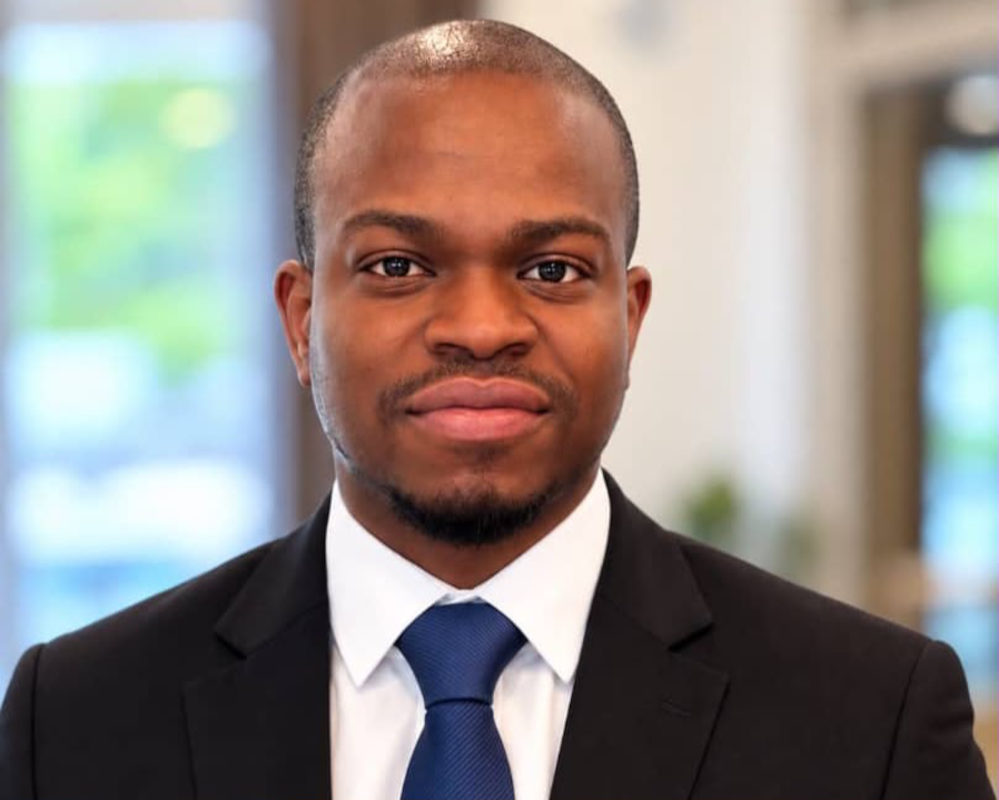
Financial literacy may improve household saving behavior, but knowledge alone cannot guarantee that families will have money set aside for emergencies, financial researcher Olawale Akinleye has said.
Akinleye made this observation while discussing research he presented at the 2026 Financial Therapy Association (FTA) Annual Conference, held from June 4 to 6, 2026, at the Hyatt Regency Austin in Austin, Texas, United States.
The study, titled “The Impact of Financial Literacy on Emergency Savings: The Moderating Role of Household Income,” examined whether the influence of financial literacy on emergency savings varies across income groups.
Emergency savings help households meet unexpected expenses arising from illness, job loss, urgent repairs, and other financial shocks. Without such a financial buffer, families may resort to expensive loans, sell valuable assets, delay essential healthcare, or depend on relatives and friends.
Explaining the significance of the study, Akinleye said financial knowledge remains important but must be considered alongside the economic circumstances in which households make decisions.
According to him, “Knowledge alone is insufficient. People must also have the financial capacity and opportunity to apply what they know.”
The findings showed that objective financial literacy, knowledge demonstrated through responses to financial questions, was associated with emergency savings among middle- and higher-income households. However, it had little measurable effect among low-income households.
Akinleye explained that this does not necessarily mean low-income households lack financial discipline. Rather, many may understand the importance of saving but have little money remaining after meeting essential needs.
The study also examined subjective financial literacy, which refers to an individual’s confidence in managing money. This form of financial literacy was associated with emergency savings across income groups, with the strongest effect observed among middle-income households. Savings-account ownership was another important predictor of emergency savings.
Although the study examined data from the United States, Akinleye noted that its central message is relevant to Nigeria, where many households contend with irregular incomes, inflation, rising living costs, and limited access to affordable financial services.
He urged the government to adopt a broader approach to improving household financial resilience.
Financial education, he said, should be incorporated into schools, universities, workplaces, vocational programs, and community initiatives. Such education must, however, be supported by policies that promote income stability, consumer protection, affordable banking, and accessible savings opportunities.
He also called on banks, fintech companies, microfinance institutions, cooperatives, and employers to design products that reflect the circumstances of low- and moderate-income earners.
These could include low-cost emergency savings accounts, automated micro-savings platforms, voluntary payroll deductions, and flexible savings products for workers with fluctuating incomes.
Akinleye further encouraged Nigerian researchers to investigate how income, inflation, employment instability, family responsibilities, and access to formal financial services affect emergency savings in the country. He said locally generated evidence would help policymakers and financial institutions develop interventions suited to Nigeria’s economic realities.
The researcher stressed that financial inclusion should not be measured merely by the number of people who own bank accounts. Its success should also be assessed by whether households can build savings, withstand financial shocks, and avoid falling into debt during emergencies.
Akinleye’s presentation at the FTA Annual Conference brought the issue before an international audience of researchers, financial therapists, educators, policymakers, and financial professionals.
The study’s central message is that households require both the knowledge to make sound financial decisions and the economic capacity to act on that knowledge. Consequently, efforts to improve emergency savings must combine financial education with practical measures that enable households to save.