 Follow Us on Google News
 Follow Us on Google Discover
* Commits 186,000 bpd to liabilities payment, interest
The Nigerian National Petroleum Company Limited (NNPC Ltd) had about N8.2 trillion in liabilities arising from forward crude oil sale agreements at the end of 2025, showing the extent to which future crude production has been committed under financing and prepayment arrangements.
The figure represents the bulk of N8.69 trillion in contract liabilities reported in the company’s 2025 audited financial statements, with about N8.25 trillion attributed to forward-sale agreements. The company also recorded about N847.6 billion in interest relating to contract liabilities during the year.
The disclosure remains significant because forward-sale arrangements allow NNPC to obtain funding upfront against crude oil to be delivered in the future. While the arrangements provide immediate liquidity, the financial statements show that they also create obligations that must be settled through future crude deliveries and associated financing costs.
One of the most significant arrangements is Project Gazelle, a crude-backed financing structure initiated in 2023.
Under the arrangement, NNPC entered into a forward sale agreement to supply 90,000 barrels of crude oil per day from Production Sharing Contract (PSC) assets. The financing was used to fund advance payments of future tax and royalty obligations due to the Federation in respect of PSC assets managed by the company.
The earlier structure involved a five-year arrangement. NNPC’s 2024 financial statements disclosed that N4.9 trillion had been drawn from a N5.1 trillion facility by December 2024, while crude valued at N991 billion had been lifted, leaving a balance of about N3.8 trillion at that date. The facility carried an interest rate benchmarked to three-month SOFR plus a margin.
The 2025 accounts show that Project Gazelle remains part of the company’s forward-sale financing obligations, alongside other arrangements including Project Leopard and Project Leopard II.
Project Leopard involves the forward sale of 35,000 barrels per day, while Project Leopard II involves 61,250 barrels per day. Together, those two arrangements represent commitments covering 96,250 barrels per day of future crude production, separate from the 90,000 barrels per day associated with Gazelle.
The scale of the arrangements raises an important financial question of how much of NNPC’s future crude production is already committed to servicing existing financing obligations and what that means for the company’s future cash flows.
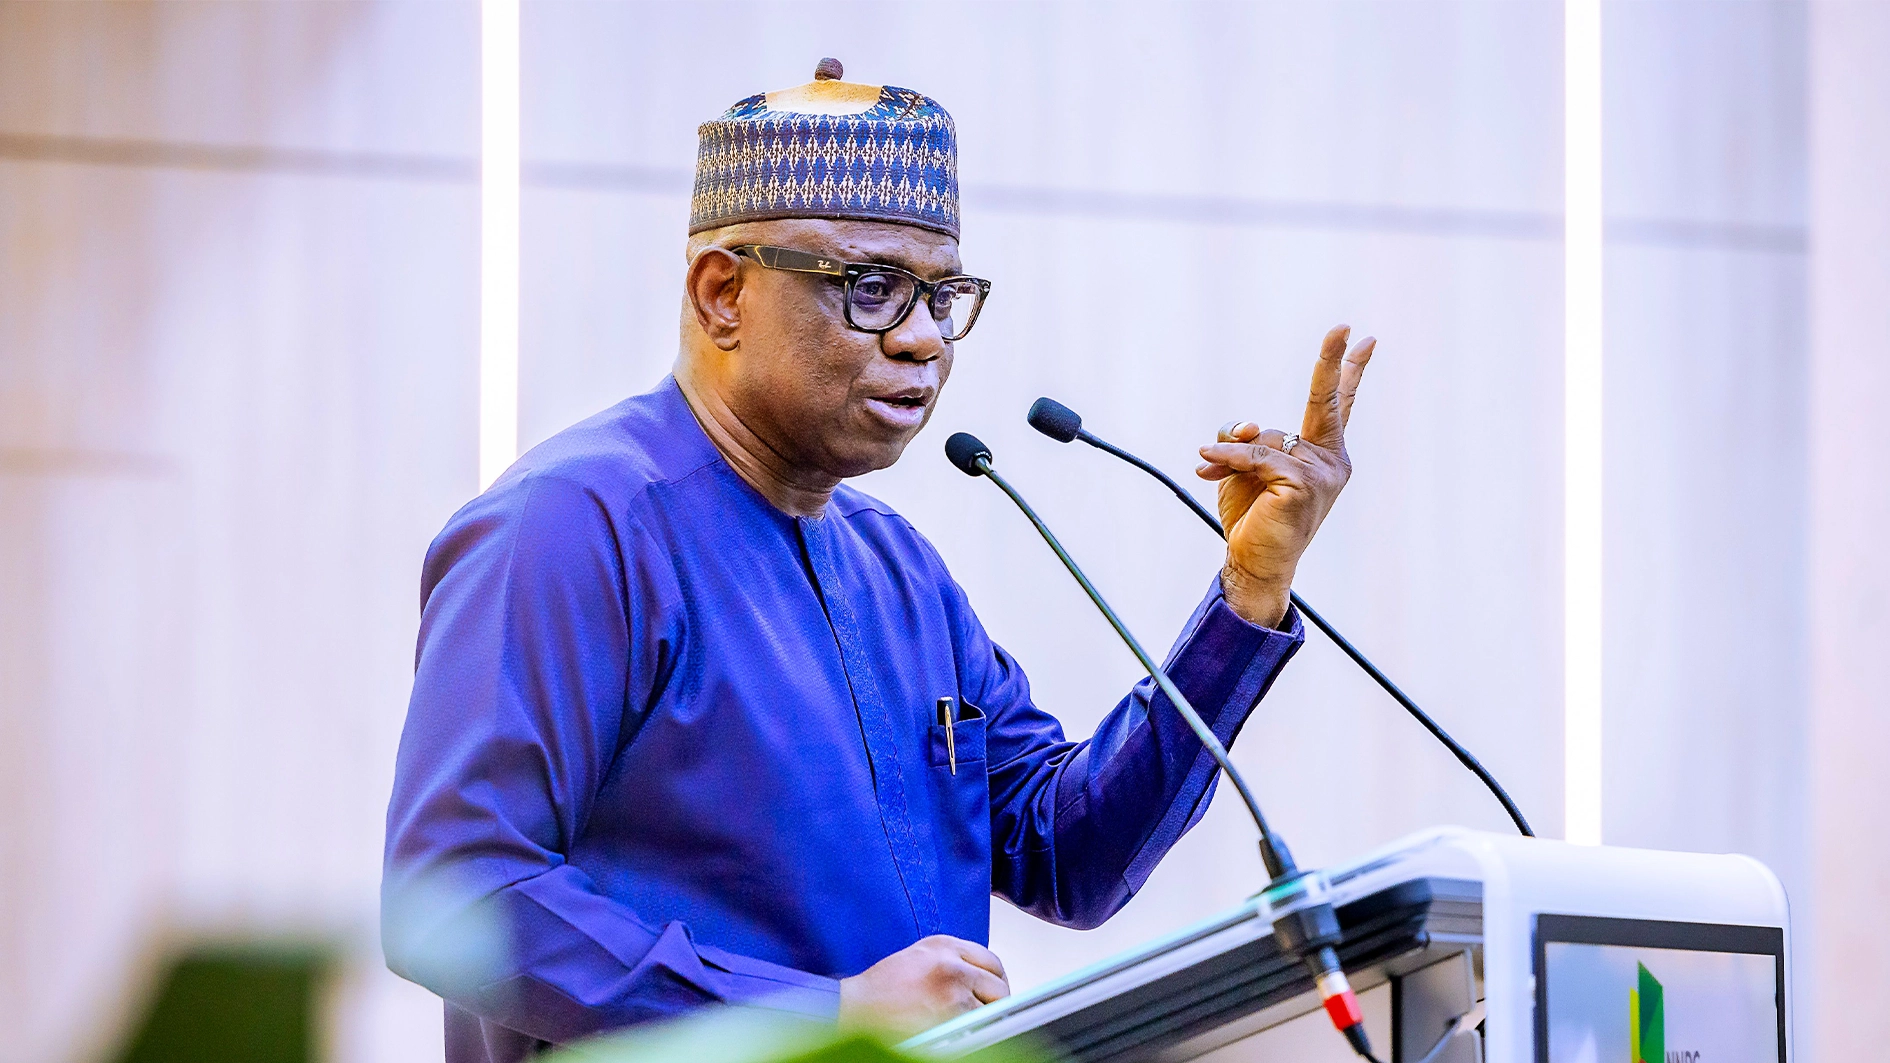
Speaking in Abuja on Tuesday while discussing NNPC’s 2025 audited results, Group Chief Executive Officer, Bashir Bayo Ojulari, said Project Gazelle remains active until its obligations are fully settled.
“Specifically, Project Gazelle is still on,” Ojulari said, explaining that the arrangement relates to PSCs rather than joint ventures.
He said the distinction was important because Gazelle does not directly affect NNPC’s “bottom-line crude projection” in the same way some other production arrangements might.
ccording to Ojulari, the facility will remain in place until it is paid off, although the repayment period could change depending on crude prices and production levels.
“If your price is low and your production is low, it may be extended a little bit,” he said.
That comment provides an important context for the liability disclosed in the financial statements. A lower crude price or lower production does not simply eliminate the obligation; according to the GCEO, it could affect the period over which the financing remains outstanding.
The financial statements therefore put a monetary value on a broader question about Nigeria’s oil finances, especially the extent to which future crude output is already committed before the company receives the associated proceeds.
NNPC’s 2025 results show that the company remained profitable, recording N7.2 trillion profit after tax, although revenue declined to N34.5 trillion from N45.1 trillion in 2024. Operating cash flow was N12.8 trillion.
Against that backdrop, the N8.2 trillion forward-sale liability deserves close attention, not because the audited accounts establish wrongdoing, but because it represents a substantial contractual obligation tied to future crude deliveries.