 Follow Us on Google News
 Follow Us on Google Discover
By Oluwaseun Jegede
Abstract
Budget blowouts are an endemic problem in building construction, especially when project budgets are designed with insufficient detailed provisions for aligning scope, resources, responsibilities and costs. While the WBS is generally viewed as the most basic project management tool, its impact on actual cost performance is not often analysed in terms of the quality or maturity of the WBS. This study evaluates WBS maturity as a predictor of project cost control quality in the Nigerian building construction industry with specific focus on the correlation between front-end scope decomposition and EVM indicators. The implication is that WBS maturity is important not simply because a project has a WBS but that the extent of the structure has implications for whether or not project work can be meaningfully assigned, budgeted, measured and controlled. A mature WBS produces discrete work packages that can be linked to planned value, actual cost and earned value making Cost Performance Index (CPI) variances visible at increasingly lower levels of project delivery. Conversely, immature WBS layouts cluster activities into large cost buckets that make it difficult for project teams to trace the source and timing of cost overruns. This difference is critical to understand in the context of Nigerian construction where inflation, material-price volatility, procurement challenges, and scope variations may be compounded by the inadequacies of project planning.
Lay summary: Therefore, the article considers the maturity of WBS as a key cost-informational architecture rather than as a scheduling tool. The information reviewed indicates that to achieve effective cost performance, it is essential to integrate the development of the WBS with budgeting, assigning responsibility, measuring progress, and EV M. The results have implications for Nigerian contractors and project managers who wish to enhance early warning systems for cost overruns.
1. Introduction
1.1 Translating projects needs into identifiable activities
Project cost performance is largely determined by decisions made before any significant physical work is done. The scope of work at the start of a project needs to be translated into identifiable activities, resources need to be allocated and financial commitments need to be created against an agreed baseline. In cases where these relationships are ill defined, cost control becomes primarily reactive. This is especially relevant in construction projects as projects are interdependent activities, multiple specialist contractors, varying site conditions and high vulnerability to material and labour costs (AlNasseri, 2015; Oduoza et al., 2018). The issue is not just whether construction teams track costs, but whether the initial project structure allows costs to be tracked in a way that is meaningful.
The Work Breakdown Structure is a prime avenue for breaking down project scope into manageable elements. The WBS allows the project team to progress from a high-level project goal to increasingly detailed work packages that can then be scheduled, costed, made responsible and tracked. It is not only important as a documentation tool: the way that the WBS is structured also affects how the project baseline is built and how performance information is subsequently aggregated. The literature on construction planning also highlights the interplay between work structuring, scheduling and project control (Ballard, 2003; AlNasseri, 2015). However, the simple presence of a WBS does not necessarily mean good project planning. Two projects may have WBS documents but their WBS may be very different in terms of level of decomposition, cost traceability, responsibility allocation and measurability.
This distinction represents a significant conceptual gap. In project management literature, WBS is often presented as a mandatory element of planning, while the cost performance literature is dominated by cost variance, cost overrun and CPI. Earned Value Management is a bridge between these two worlds, as it requires project scope, schedule and cost information to be integrated into a common performance framework. CPI is defined as earned value divided by actual cost and is a measure of the cost efficiency with which completed work has been delivered. But the quality of CPI is also determined, at least in part, by the quality of the underlying work and cost structure. The primary concern with using large and ill-defined activities as the project’s base units of reporting is that cost problems may go undetected until significant resources have already been expended.
This issue is particularly relevant in the context of the Nigerian construction industry. Previous studies of Nigerian construction projects have consistently identified cost overrun, poor planning, resource constraints, variations and other project management deficiencies as major contributors to poor project performance (Yusuf, 2021; Simon-Eigbe, 2022). Recent Nigerian literature also continues to find project management tools and techniques as a key aspect of building project delivery, including the WBS as a tool to structure project work and facilitate performance measurement. In this light, this paper investigates the relationship between WBS maturity and project cost performance, and argues that the essence of WBS is its ability to convert an otherwise high-level construction budget into a measurable control system.
2. WBS Maturity as a Foundation for Cost Control
2.1 A look a substructure, superstructure, roofing
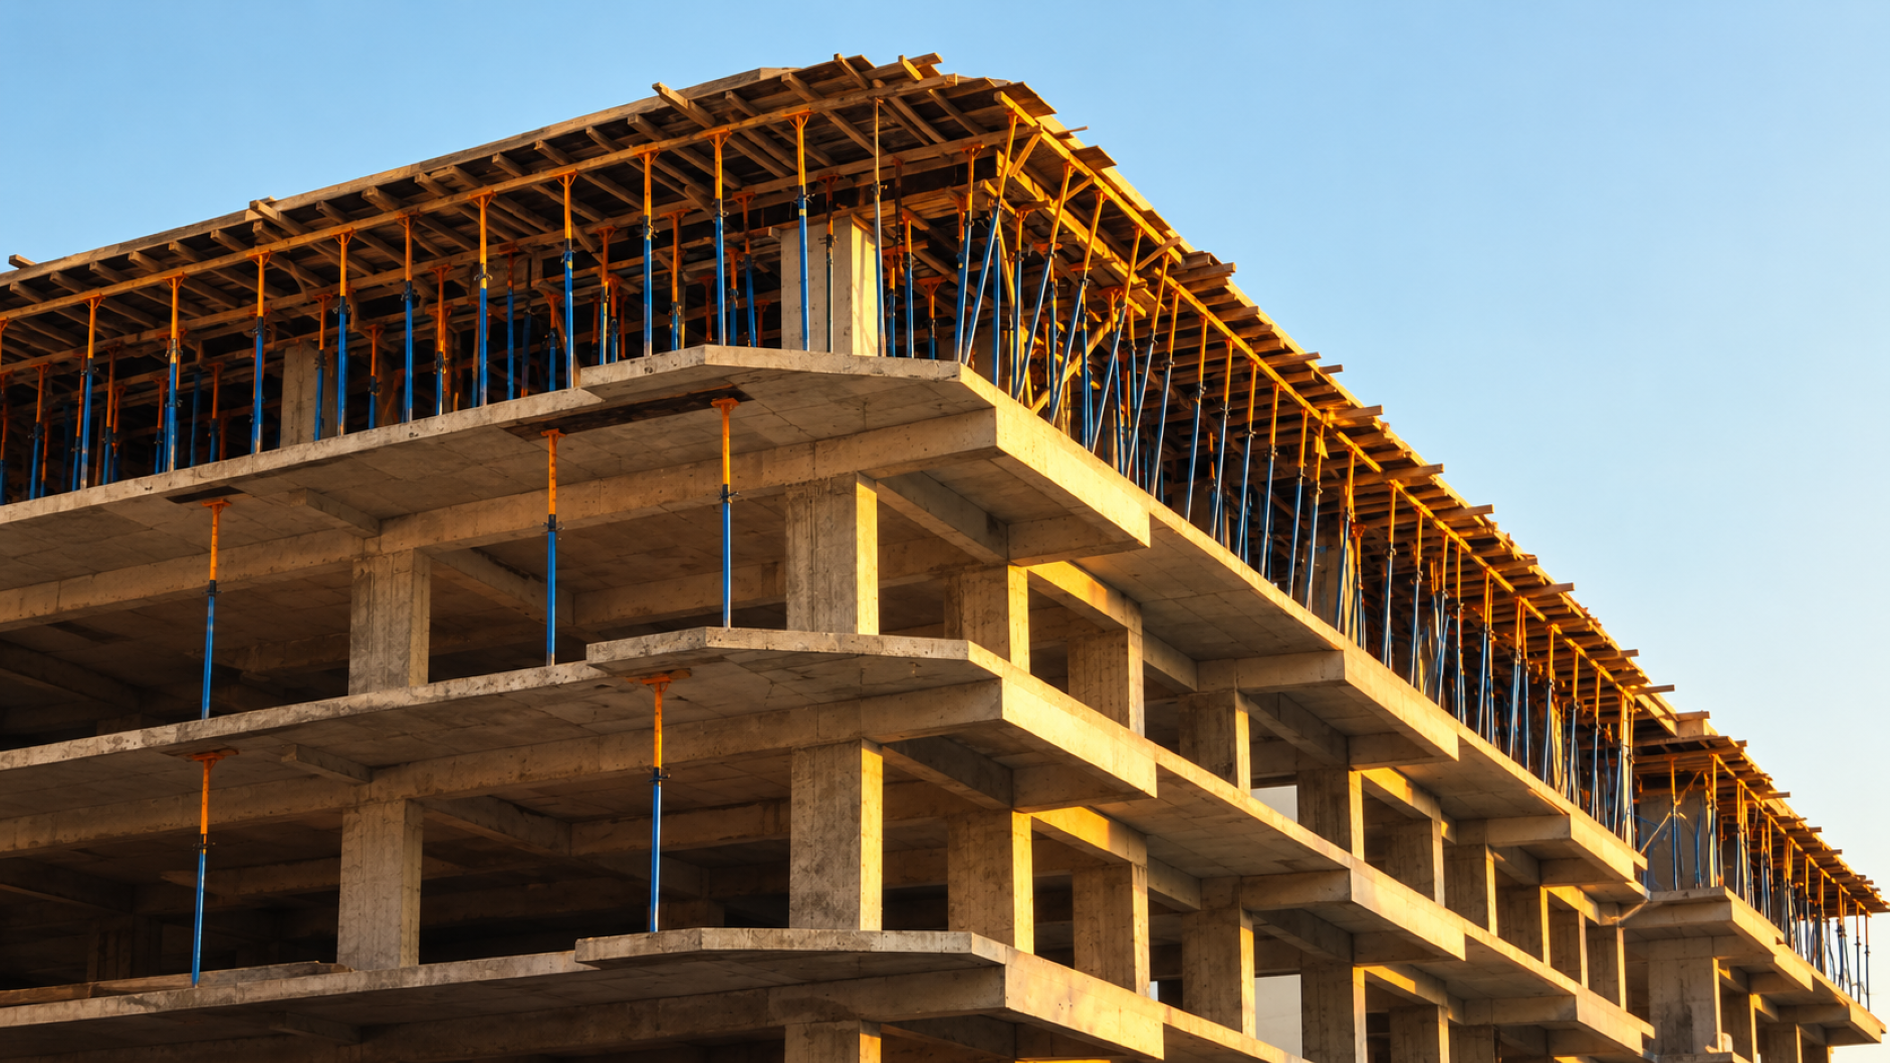
The term WBS maturity is not to be confused with the availability of a WBS. A simple WBS can show items like the major portions of the project, such as substructure, superstructure, roofing, finishes and services. At a more mature level, these elements are decomposed into well-defined work packages with tangible outputs, cost estimates, schedules, responsible parties and completion criteria that can be measured. The distinction matters because to control a project it is not enough for managers to know what the project contains; they also have to know how much each piece should cost, when it should take place, who is responsible and how they will know it is done.
2.2 WBS as a Framework for Project Control and Cost Tracking
The connection between work structuring and project control has been observed in construction-management literature. Schedules are basically products of work structuring as they define the activities and relations through which project work is organized (Ballard, 2003). Also, as evident from AlNasseri (2015), it also proves how planning and scheduling techniques are very crucial in construction-project management. These views indicate that the quality of a WBS influences more than just the planning document that is initially prepared: it dictates the level at which management information is rendered.
The literature results show that WBS maturity was the most useful when cost information needed to be traced to physical progress. A poorly decomposed project can state that ₦100 million has been expended on “structural works,” but such a number tells little diagnostic information. A mature WBS can break down the excavation, foundation concrete, reinforcement, formwork, columns, beams and slabs, so that at each stage the actual expenditure is compared with the value of work performed. This provides a much stronger basis for intervention.
Here, WBS becomes a cost information architecture. Its intent is not simply to break down a project into pieces, but to create a common framework where scope, schedule, budget and actual can talk to one another. Modern research on construction information management and digital project controls is increasingly revealing this paradigm, with structured project information enabling finer-performance monitoring. In like manner, recent BIM-based construction analytics show the benefit of linking performance measures to identifiable WBS nodes rather than depending solely on project-level summarizations Kim, Y. (2022).
3. WBS Maturity and Earned Value Cost Performance
3.1 WBS Maturity and Earned Value Management for Cost Performance
Earned Value Management (EVM) provides a critical linkage analysis that can be considered the strongest between the quality of WBS and the cost performance. EVM includes three basic elements: Planned Value (PV), Earned Value (EV), and Actual Cost (AC). From these indicators, the manager can calculate the CPI of the cost performance: CPI = EV/AC. When CPI is greater than 1, it means the value of completed work is greater than the actual cost associated to it, and in case of a CPI less than 1, the project is spending more than the value of work completed. But the practicality of this measurement relies on knowing exactly what work has been planned, how much of it actually completed, and how much cost has been incurred on that work.
That is exactly where the maturity of the WBS comes into play. A comprehensive WBS provides a series of discrete elements that budgets and progress quantifications may be assigned. As such, EVM can show not only that a project is being cost-inefficient, but in which areas the cost-inefficiency is most prevalent. A project level CPI of 0.88 has meaning, but it is made far more meaningful when that number is supported by data that show a CPI of 0.74 for the structural work package and a 1.03 for mechanical services. Instead of wobbling the whole project as an undifferentiated cost problem, management can then track down the elusive cause of the decline.
3.2 WBS Maturity and the Balance Between Detail and Control
Findings from construction-management studies are consistent with advocating the use of a suite of performance measures to assess project outcomes. Performance measures have been used in Nigerian research to study cost and schedule trends in building projects, and studies on proactive cost management have highlighted the importance of holistic methods of construction-cost control monitoring (Yusuf, 2021; Simon-Eigbe, 2022). The nascent literature also continues to focus on the integration of WBS, EVM and digital project-control systems, implying a cross-fertilization from period cost reporting towards more and more detailed performance monitoring Chen, S.-M., Griffis, F. H., Chen, P.-H., & Chang, L.-M. (2015).
The result, then, suggests a threshold effect in WBS maturity. When maturity is low, additional decomposition of work may bring little advantage if work packages so formed are not related to budgets and measurable outputs. However, at higher levels, any further meaningful decomposition naturally leads to better cost traceability. Therefore, the important point is not too much detail but sufficient detail. Too much fragmentation might lead to increased administrative overhead, and may hide rather than reveal control, and too little decomposition does not allow for useful variance analysis.
4. The Nigerian Construction Context
4.1 Factors driving final project cost
The link between WBS maturity and cost performance cannot be viewed in isolation from the wider operating environment of Nigerian construction. Inflation, exchange rate fluctuations, supply chain disruptions, fluctuations in material prices, procurement delays and scope changes can all drive up final project costs. As a result, a mature WBS cannot prevent cost overruns. Instead, it is valuable in helping project teams more accurately identify where a cost variance has occurred, when it happened and what factors might have contributed to it.
This distinction is significant because cost overruns are frequently considered as a single result. Nigerian construction research has shown that project performance is influenced by interacting technical, managerial and external factors (Oduoza et al., 2018; Yusuf, 2021). As a result, a contractor may incur increasing costs even if the original project plan was appropriate. A mature WBS does not remove the possibility of such external shocks, but it does offer a more robust baseline against which their impacts can be measured.
The results also imply that risk management and WBS maturity need to be dealt with in parallel and not in isolation. Risk events can be expressed in specific work packages, for example: material delivery delay will impact masonry or finishing work packages; design modifications may impact structural or services work packages; regulatory intervention might halt specific work packages. Once these aspects are explicitly represented in the WBS, their financial impacts can also be folded into project-control-in-process. Research such as that by Oduoza et al. (2018) on construction risk management similarly stresses the significance of systematic methods of recognising and managing project risks.
4.2 Integrating WBS with Cost and Project Control Systems
Therefore, for Nigerian contractors, WBS development should be integrated with the development of the cost baseline, responsibility matrix, procurement plan and progress-measurement system. The WBS becomes the focal point through which the functions are linked. This turns project cost control into less of a backward-looking exercise, “Why did we spend more than the budget?”, and more of a diagnostic one that can catch variances early.
5. Conclusion
5.1 WBS Maturity and Project Cost Performance
The findings reviewed in this paper suggest that the association between WBS development and project cost success is more positive in terms of matter of degree rather than matter of existence in the sense that WBS should be considered as a concept that is more related to maturity than a yes/no question. A WBS that just catalogs the elements of a project top down has little cost-control utility. A sophisticated WBS, on the other hand, produces work packages that are measurable, which can be associated with budget, schedule, responsibility and actual costs.
Thus, the major contribution of this study is to conceptualize WBS as a cost-information structure. Its significance is to define the module where Earned Value Management (EVM) becomes meaningful at the operational level. By linking work packages to planned value, earned value and actual cost, a mature WBS brings visibility and traceability to cost overruns. This will not remove the external influences that cause cost pressures in Nigerian construction but it will make their effects more identifiable and manageable.
For Nigerian construction projects, it means that better cost performance is not to be achieved simply by better financial monitoring once the building work is underway. More focus need to be placed on how well a project initially decomposes scope. Integrated with budgeting, scheduling, risk management and EVM, maturity provides a more pro-active control approach of construction cost, that is capable of identifying cost deterioration of performance prior to rooting in final project expenditure.
References
AlNasseri, H. A. (2015). Understanding applications of project planning and scheduling in construction projects. Lund University. https://portal.research.lu.se/en/publications/understanding-applications-of-project-planning-and-scheduling-in/
Ballard, G. (2003). An update on the Last Planner. Proceedings of the 11th Annual Conference of the International Group for Lean Construction. https://www.iglc.net/
Oduoza, C. F., Odimabo, O. O., & others. (2018). An insight into the process, tools and techniques for construction risk management. Risk Management and Healthcare Policy / related construction-risk literature. https://wlv.openrepository.com/server/api/core/bitstreams/4bae7d1a-5f11-43b4-a68d-07749b897de6/content
Yusuf, G. (2021). Proactive cost management model for building projects. Current Journal of Applied Science and Technology. https://www.academia.edu/download/85539000/58708.pdf
Simon-Eigbe, B. (2022). Factors affecting project performance of building construction projects in Federal Capital Territory (FCT), Abuja, Nigeria. Current Journal of Applied Science and Technology. https://www.academia.edu/download/99697112/7921.pdf
Chen, S.-M., Griffis, F. H., Chen, P.-H., & Chang, L.-M. (2015). An integrated BIM system to track the time and cost of construction projects: A case study. The Scientific World Journal, 2015, Article 579486. https://doi.org/10.1155/2015/579486.
Kim, Y. (2022). A case study on BIM object-based earned value and process management in highway construction. KSCE Journal of Civil Engineering. https://doi.org/10.1007/s12205-021-1348-3
About the Author
Oluwaseun Jegede is a building and construction engineer with expertise in construction project management, quality assurance, project scheduling and site execution in Nigeria, with additional studies on Construction Project Management at tertiary level in the United Kingdom.