 Follow Us on Google News
 Follow Us on Google Discover
Financial failures rarely announce themselves. More often than dramatic investment losses or collapsing revenues, they begin quietly — with weak controls, unreliable reporting, poorly reconciled records, inconsistencies nobody noticed and management decisions taken on incomplete information.
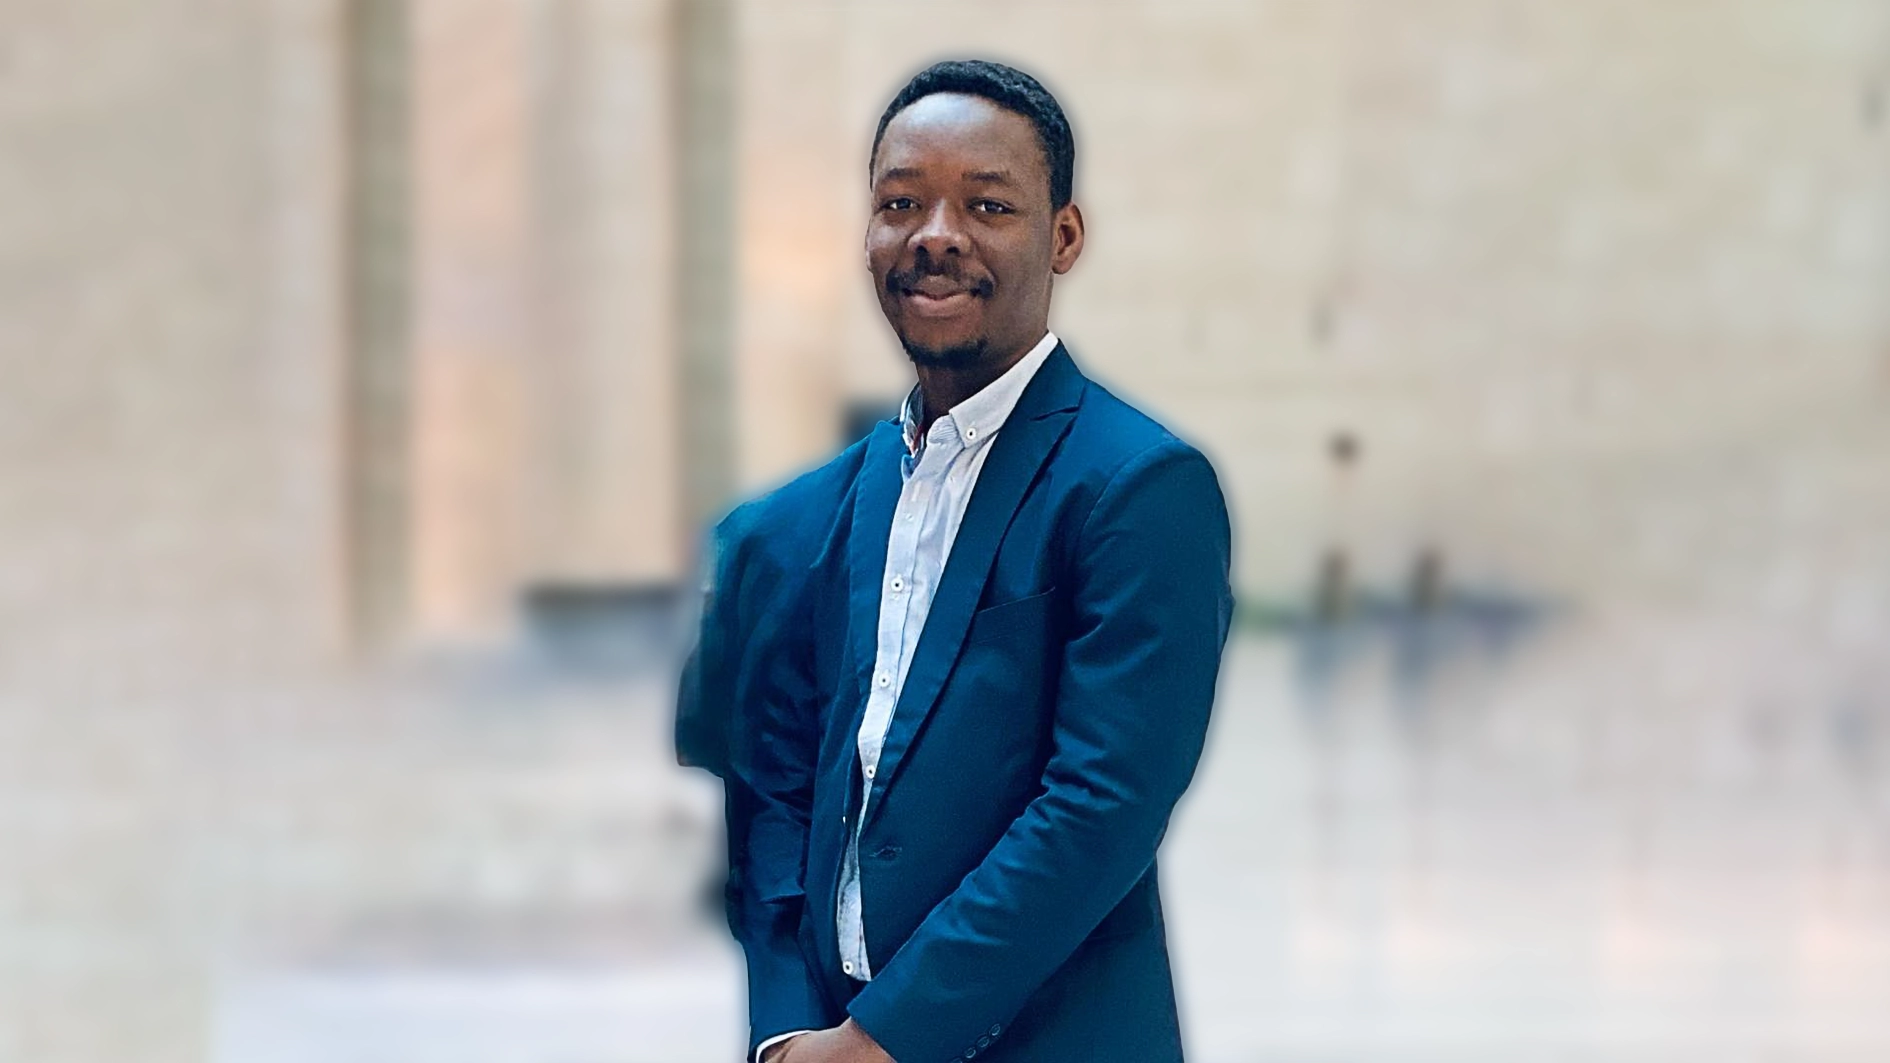
For Oluwapelumi Oladepo, a quantitative economics and business analytics professional, that pattern underlines a principle increasingly central to modern financial management: the quality of financial decisions depends heavily on the quality of the information and the controls behind them. His work across financial operations, risk mitigation and quantitative analysis reflects a broader transformation in the field, as organisations fold analytics, forecasting and systematic controls into everyday decision-making.
Financial management has traditionally centred on budgeting, accounting, investment and capital allocation. Yet organisations now operate in environments generating enormous volumes of data continuously, and the presence of more data does not automatically produce better decisions. Poor-quality financial information carries real risk: incorrect categorisation distorts management reporting, inconsistent processes erode confidence in financial statements, and weak controls create openings for error and compliance failure.
That reasoning has pushed Oladepo’s analytical interests toward the relationship between quality control and financial risk. In 2024 he co-authored research titled “Quality Control in Financial Operations: Best Practices for Risk Mitigation and Compliance,” examining how financial controls, standardised processes and quality-management practices can strengthen reliability and reduce exposure to operational and compliance risk.
Controls are often perceived narrowly, as mechanisms for catching wrongdoing.
Their function is considerably broader. Effective controls ensure that transactions are properly recorded, that information is reliable, that responsibilities are clearly assigned and that management decisions rest on accurate figures. Oladepo argues that financial quality control should therefore be understood as part of strategic management rather than administrative housekeeping.
The consequences of neglecting it compound quickly. When management cannot trust its financial data, forecasting becomes less reliable, budgeting becomes harder, performance measurement is distorted, and investment decisions may rest on inaccurate assumptions. Quality control, in short, provides the foundation on which more advanced financial analysis can stand.
Oladepo’s academic development has reinforced that perspective. In 2024 he completed a Master of Science in Quantitative Economics alongside post-baccalaureate study in Business Analytics at Western Illinois University — a combination that pairs tools for understanding relationships among economic variables with methods for extracting actionable information from organisational data. Forecasting, predictive analytics, econometrics, data mining and statistical analysis all contribute to better financial decisions when applied to the right questions.
Those techniques also mark a shift in what finance functions are expected to deliver. Traditional reporting explains what has already happened; modern financial management increasingly asks what is likely to happen next. Historical expenditure data can be examined for patterns, performance indicators monitored for emerging deviations, forecasts updated as new information arrives and alternative scenarios evaluated before resources are committed.
Predictive analysis does not eliminate uncertainty, but it allows organisations to understand uncertainty more intelligently — and Oladepo’s training in predictive analytics, econometrics, statistics, data mining and data visualisation is aimed squarely at that shift.
Technology has changed how the work is done. Tools such as Python, SAS, R, Tableau, Power BI, Excel and SQL let analysts handle larger datasets, automate parts of the analysis and communicate findings through dashboards and visual reporting. But technology alone guarantees nothing.
The analyst must still know which questions matter, and a sophisticated model aimed at the wrong financial question is less useful than a simple analysis aimed at the right one. This is why the economics background remains central to his method: economics supplies the reasoning framework, analytics the means of testing assumptions against evidence.
The practical payoff of data-driven financial management is visibility. Management needs to know where resources are being consumed, how actual results compare with expectations, where significant deviations are occurring and whether those deviations are temporary or structural. When financial information is properly organised, analysed and communicated, concerns surface earlier — which makes financial analytics a component of risk management rather than an adjunct to it. Instead of waiting for problems to appear in annual results, organisations can build systems that evaluate performance continuously.
Taken together, Oladepo’s work suggests a financial-management philosophy built on interconnected principles: reliable information, effective controls, rigorous analysis, meaningful forecasting and clear communication. Its relevance extends well beyond corporations, to financial institutions, investment organisations, government agencies and nonprofits all under pressure to manage resources responsibly and demonstrate measurable performance.
Financial management, on this account, is not simply about recording the movement of money. It is about creating systems through which financial information can be trusted, understood and converted into better decisions. In an economy where poor financial decisions carry consequences far beyond the organisation that makes them, improving the quality of those decisions has become a professional challenge of some consequence.