 Follow Us on Google News
 Follow Us on Google Discover
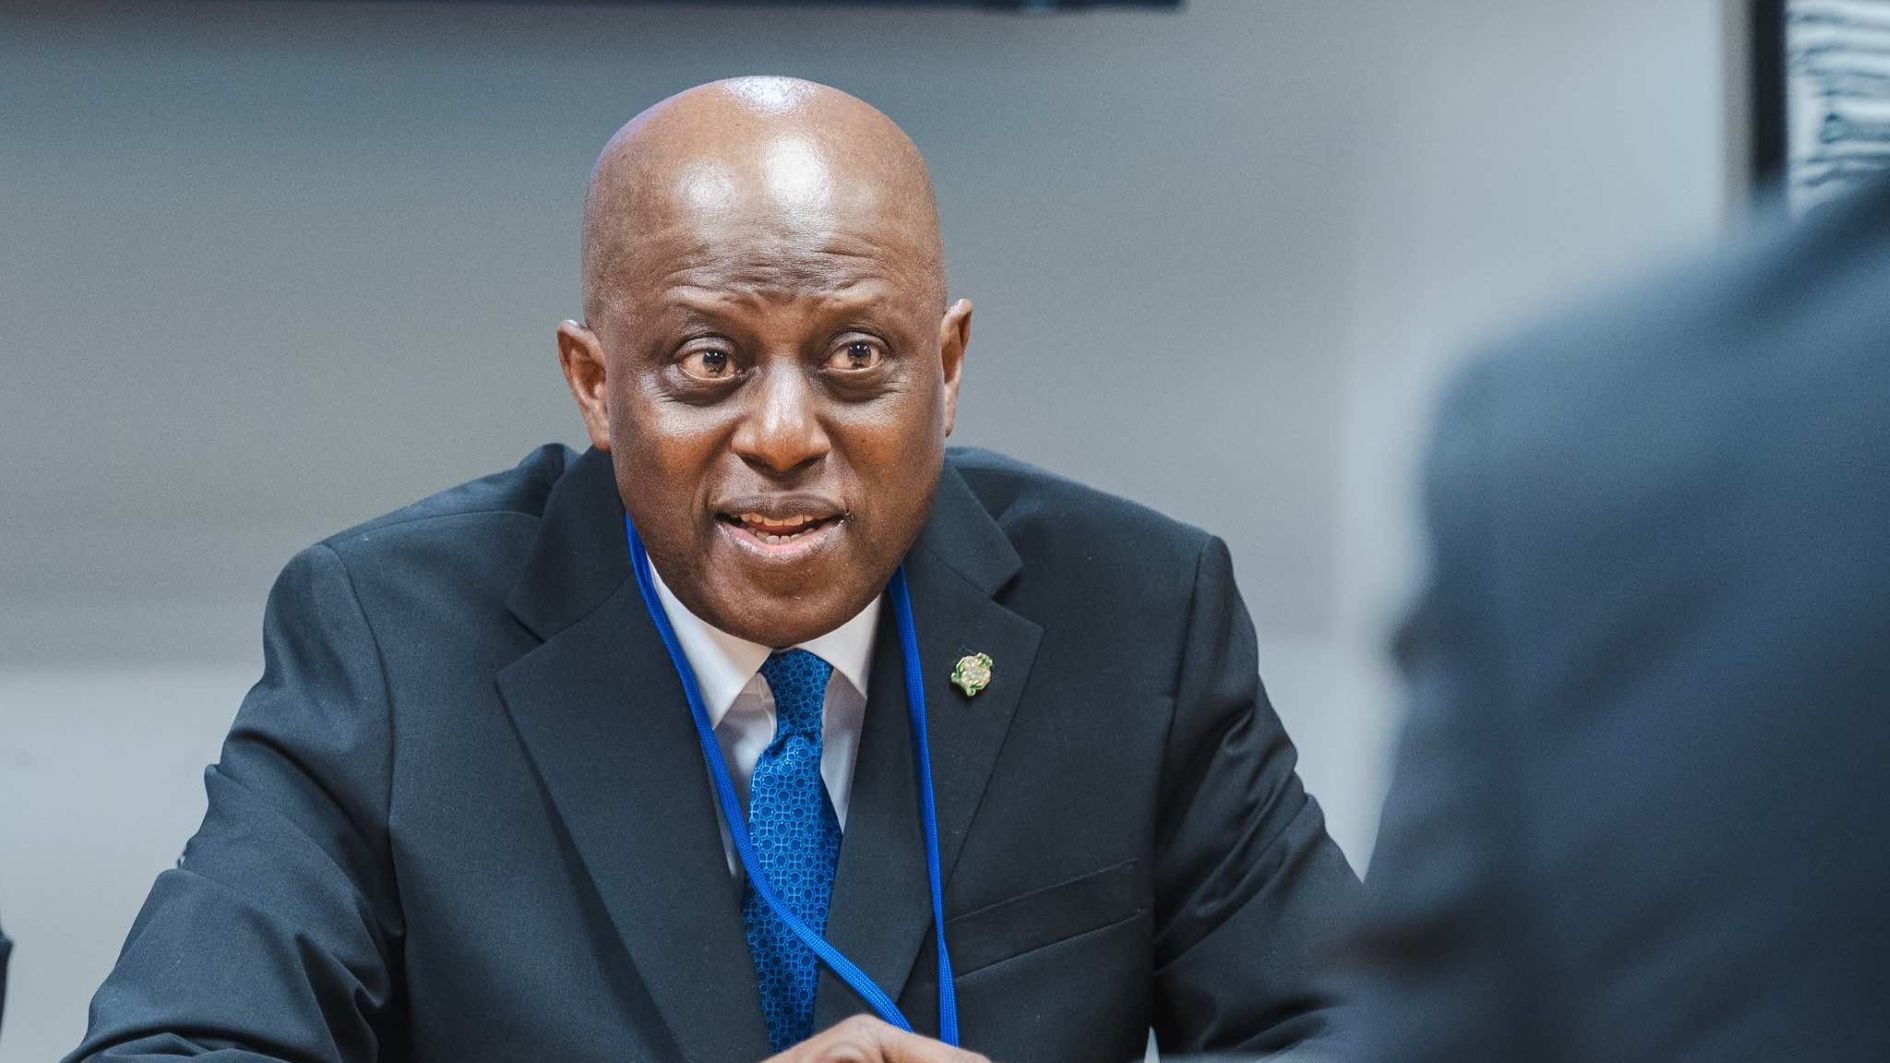
In the past three years, the Central Bank of Nigeria (CBN), under Yemi Cardoso, has embarked on broad financial-system reforms aimed at stabilising key economic prices and creating a more efficient banking system. While the macroeconomic objectives have recorded measurable progress, the significance of the decisions for millions of Nigerians continues to raise questions about the policy choices, GEOFF IYATSE and COLLINS OLAYINKA report.
The Central Bank of Nigeria (CBN) has overhauled the foreign exchange market, embarked on an ambitious banking recapitalisation, tightened monetary policy, strengthened payment-system regulation and introduced new measures to combat fraud and financial crimes since September 2023, when Yemi Cardoso assumed office.
And the results are visible. Foreign exchange-market distortions have been reduced, with the informal-market premium falling to less than five per cent. The naira has experienced one of the longest periods of stability in recent years. Foreign reserves have risen to above $55 billion, while banks have raised about N4.65 trillion in fresh capital in about two years. Digital payment systems have also improved. On the strength of these results, many have scored Cardoso highly.
But for households and businesses, the assessment is more complicated. The naira exchange rate remains above N1,300/$, about N200 below what many economists consider its current fair value. Inflation, at above 15 per cent, remains higher than in many other African economies, while high financing costs continue to constrain business performance.
The inability to bring inflation into single digits and the exchange rate below N1,000/$ makes the macroeconomic gains understandably difficult for many Nigerians to relate to.
These form the central debate around Cardoso’s tenure. Is the stabilisation of the financial system beginning to produce sufficient gains in the real economy? But the question itself betrays a poor understanding of the role of the central bank and the limits of monetary intervention in the economy.
Cardoso’s reforms have largely focused on rebuilding the machinery through which monetary policy works and recalibrating key economic prices — inflation, exchange rates and interest rates. The more difficult phase is making these processes deliver results that households and businesses can relate to. But the economy needs more than monetary policy to achieve that; it needs the support of robust fiscal programmes to respond positively to monetary-policy gains.
For instance, a stable naira, improved liquidity and lower inflation cannot automatically translate into improved credit in a largely unbankable economy, where operators battle high regulatory costs and resort to self-help where public goods are needed.
Cardoso inherited a monetary and financial system under considerable pressure. Inflation was elevated; the FX market was rising from the ashes of fragmentation and extreme rigidities; confidence in policy signals was at its weakest, while the banking system’s capital stocks were eroded by the weaker naira.
The CBN tightened monetary policy, reformed the FX market, commenced a major bank recapitalisation programme, strengthened regulation of financial institutions and payment operators, introduced new anti-fraud and financial-crime measures, modernised market infrastructure and sought to rebuild external buffers. The scale of the changes seen in the past three years has been substantial.
The banking-sector recapitalisation is perhaps the clearest example of the difference between institutional reform and its economic payoff.
By March 31, 2026, 33 banks had met the CBN’s revised minimum capital requirements, raising about N4.65 trillion in fresh capital. The exercise was designed to strengthen banks’ ability to absorb shocks and finance the $1 trillion economy ambition.
The additional capital provides stronger buffers for many banks. But stronger bank balance sheets do not automatically mean cheaper credit. If banks have more capital but businesses continue to face lending rates of 35 per cent, the transmission from recapitalisation to production remains weak — a contradiction that suggests the reform remains an unfinished business for Cardoso.
More importantly, the 35 per cent interest rate, being the price of a high-risk premium, says much about how much work governments must do to make monetary policy serve its purpose. Banks need efficient power to optimise operations and lend at lower interest rates. Long-term capital must be unlocked to mobilise financing for manufacturing. Insecurity should be tackled and market access improved to make agro-businesses bankable.
With the cost of operations still extremely high for banks that must self-generate power to run their offices, reducing the cost of credit is not the job of Cardoso and his team alone. How the CBN and the fiscal authorities collaborate to achieve cheaper capital will go a long way in determining whether the overall objective of recapitalisation will be achieved.
The foreign exchange market represents another area where Cardoso’s reforms have produced significant change but also generated a difficult debate. The CBN has placed considerable emphasis on FX stability rather than defending a particular value range for the naira, so much so that faster-than-expected appreciation of the local currency last year caused some panic in policy circles.
The argument is that businesses and investors can plan better around a stable and transparent market than under a regime dominated by an artificially strong currency and market distortions. For many Nigerians, however, this explanation is less important than the cost implications of a weaker naira.
nagement and about 65 per cent since the June 2023 pro-market reforms. A naira that is more stable but significantly weaker than its pre-reform value raises the nominal cost of imported food, machinery, raw materials, fuel and other goods. But this is a policy choice, not necessarily a failure, highlighting the complexity of monetary policy management as a dismal science.
To improve market functioning, the CBN has introduced the Nigerian FX Code, revised FX regulations, reformed bureaux de change (BDCs), and introduced new rules for international money-transfer operators and oil-company export proceeds. The Fourth Edition of the Foreign Exchange Manual, launched in May 2026, represented another step towards codifying the market. The reforms are aimed at reducing uncertainty.
Importers need predictable access to foreign currency. Manufacturers need greater certainty over input costs. Foreign investors need confidence that they can repatriate legitimate earnings. Exporters need a transparent mechanism for bringing proceeds into the country. The reforms have produced greater liquidity, narrower arbitrage, less speculative demand for dollars, reduced backlogs and more predictable access to FX for legitimate businesses.
The CBN’s reforms on international oil companies illustrate the same challenge. It allowed companies to repatriate 100 per cent of export proceeds through authorised dealer banks, reducing rigidities and enhancing market confidence, while underpinning the rising significance of the impossible trinity in exchange-rate management.
With the benefits of hindsight, the reform strand sits in the gap between positive and normative principles, leaving Cardoso significantly satisfied with the outcome of the reforms and some Nigerians justifiably not. The chief central banker, from the outset, wanted to create a market that was transparent and predictable, but not a “Father Christmas” naira supported by distortive policies.
For Nigerians who value stability, he is on course to achieving significant success. But for those who see a weaker naira as a falling knife in an importing economy such as Nigeria, the reforms have fallen short. Two expectations, two grading systems and two scores.
Until its last meeting, when the Monetary Policy Committee (MPC) reduced the benchmark interest rate by 3.5 percentage points — a policy choice that was as surprising as the earlier increases — Cardoso had chosen to ‘choke’ the economy to rein in inflation. For the optics, Cardoso would not be forgiven if he failed to take a position on the direction of interest rates. From 18.5 per cent, he took the rate to one of the highest levels globally. That did much to shape expectations.
Perhaps stronger transmission channels would help to better assess the policy choice. With fiscal distortions undermining money-supply targeting and scant opportunities in the formal sector pushing more people into the informal and black markets, the link between the monetary policy rate (MPR) and the broader economy does not exist. This is one reason money supply has assumed a rising function of interest rates.
It manifests in the decoupling of commercial interest rates from the MPR in recent times. For instance, while the MPR rose by 900 basis points to reach its peak of 27.5 per cent under Cardoso, commercial interest rates remained between 35 and 38 per cent.
Cardoso has spoken more about strengthening the MPR transmission channels than he has done to achieve the same. But, like other issues, the CBN can lean against an excessively high residual. Authorities need to rein in excessive distortions from the political system, underground economic operators and the informal sector. These are the huge error terms that may have undermined the MPC’s money-supply determination over the years.
The debate over Cardoso’s tenure is reflected in the assessments of economists and private-sector stakeholders. A senior economics lecturer at Pan-Atlantic University, Stanley Nwani, described the scorecard as mixed, while identifying data credibility as one of the most pressing gaps.
He noted a persistent discrepancy between figures published by the CBN and the National Bureau of Statistics (NBS) and those reported by external institutions such as the World Bank, International Monetary Fund and African Development Bank.
Nwani credited Cardoso with steering the banking recapitalisation, which he said had strengthened banks’ capital base and positioned them for international classification. He also acknowledged the rise in foreign reserves, although he cautioned that the outcome reflected a combination of fiscal and monetary policies rather than CBN action alone.
However, he maintained that interest rates remain too high, that the minimum wage has not kept pace with fuel-price increases and that access to credit remains skewed towards large firms. According to him, many small and medium-sized enterprises remain excluded because of inadequate formal registration, tax records and collateral.
He called for greater efforts to formalise informal businesses and connect them to credit through microfinance banks and fintech platforms.
Chief Executive Officer of the Centre for the Promotion of Private Enterprise, Muda Yusuf, described the tenure as largely successful, particularly in addressing the severe FX liquidity crisis inherited by the administration.
According to Yusuf, the CBN inherited almost $7 billion in outstanding FX obligations, while unpaid airline remittances had left correspondent banks unwilling to honour letters of credit.
However, he said the gains had come at a steep cost, particularly the high interest-rate environment, which has made bank financing too expensive for businesses.
He said lending rates of between 25 and 35 per cent, combined with a cash reserve ratio of about 45 per cent, had made bank credit prohibitively expensive for real-sector businesses, forcing more companies to seek alternative funding through commercial papers.
Yusuf also faulted the CBN for showing less appetite for development finance than its predecessor, arguing that sectors such as manufacturing, agriculture and healthcare still lack robust long-term funding windows.
He, however, commended the banking recapitalisation exercise, describing it as relatively seamless compared with previous exercises that resulted in significant disruption and bank failures.
Prof. Sherifdeen Tella of the Department of Economics, Olabisi Onabanjo University, also pointed to reserve growth, reduced currency depreciation and the recapitalisation exercise as notable developments, saying the latter had strengthened the banking system’s capacity to withstand external shocks.