 Follow Us on Google News
 Follow Us on Google Discover
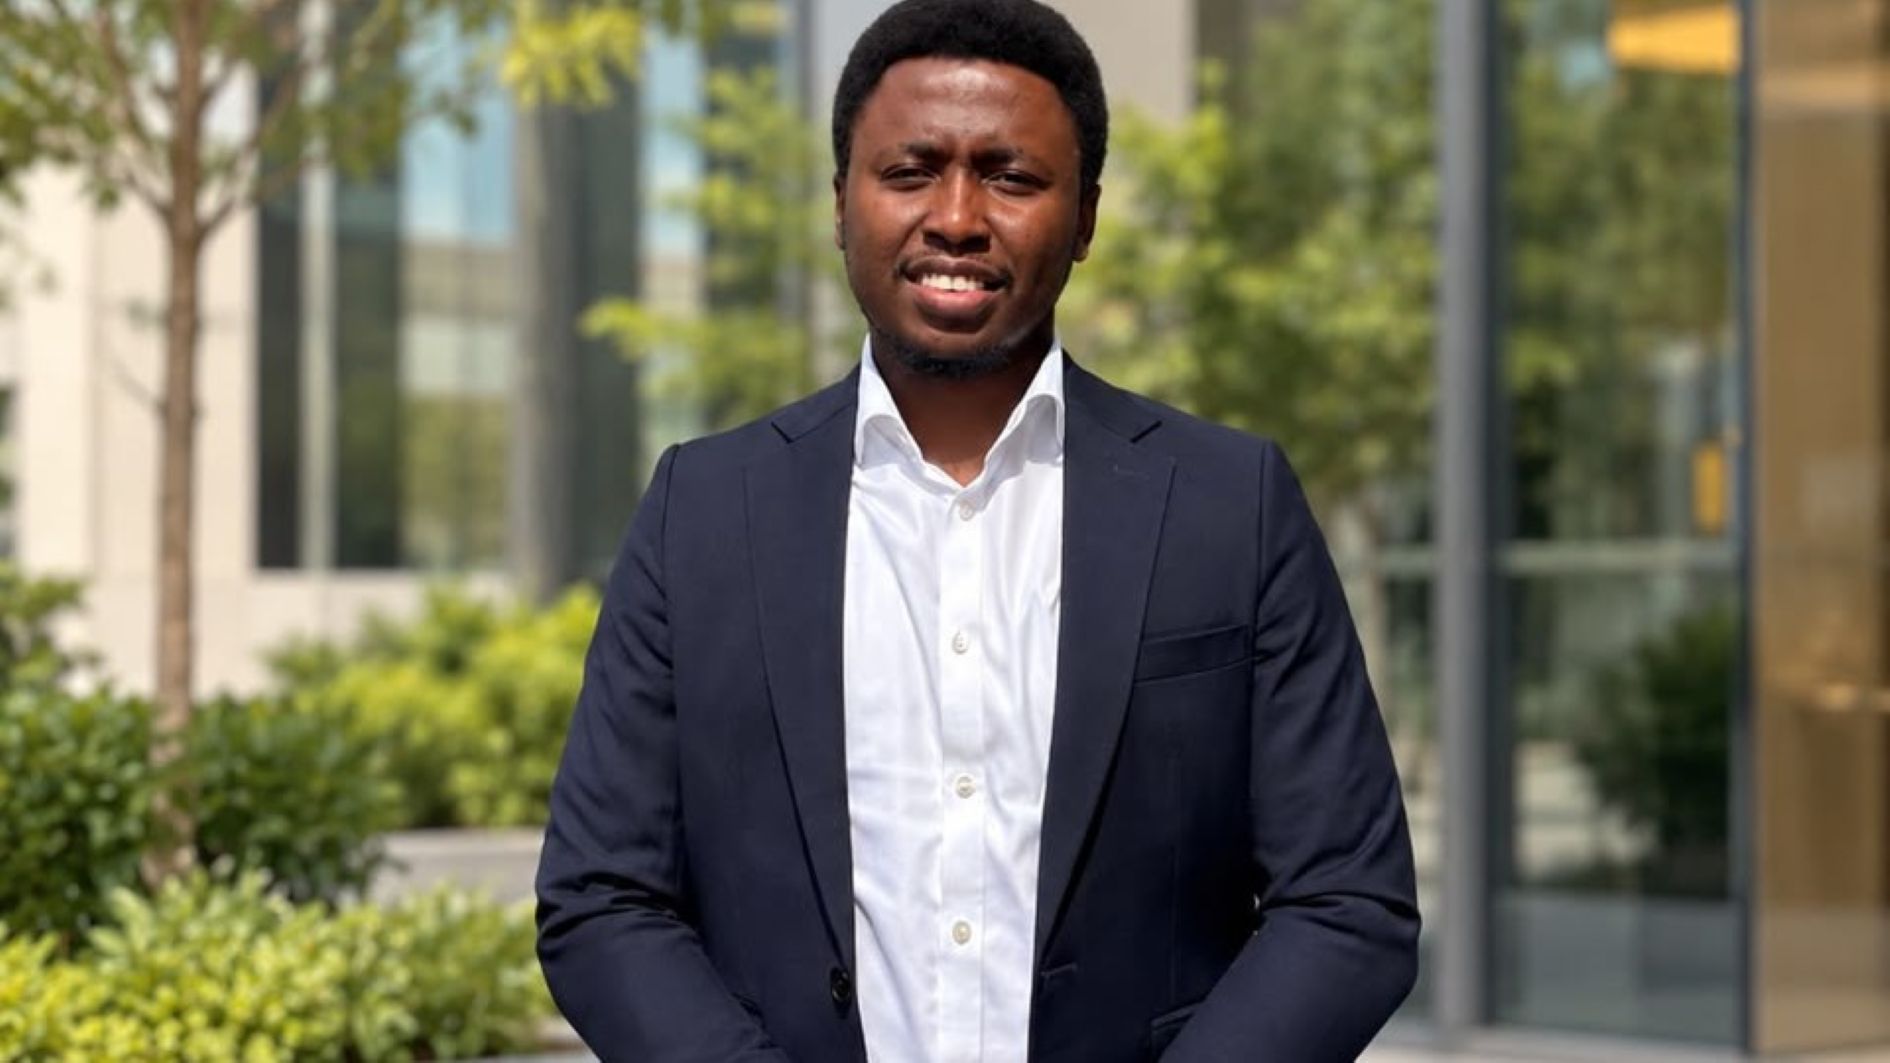
For a bank customer, a delayed decision or an unexplained rejection can carry an immediate cost. For the institution, the same decision raises questions about credit risk, efficiency and accountability. Olaolu Samuel Adesanya focuses his professional and research work on how financial institutions use data to make decisions and how leaders establish appropriate controls around those decisions.
Olaolu Adesanya worked at PricewaterhouseCoopers from 2017 to 2023, progressing through associate and senior associate roles to manager. His experience includes financial modelling, transfer pricing, compliance analysis and business strategy. He completed an MBA at the University of Chicago Booth School of Business in June 2025, following a first-class degree in Business Administration from Covenant University. His research interests include predictive credit analytics, banking automation and digital-twin applications in financial risk.
This interview explores what technology can improve, how institutions should measure its impact, and why accountability remains essential as financial decisions become increasingly automated.
You moved from advisory work in Nigeria to an MBA in Chicago. Which problem has remained central to your work?
Adesanya: The central question for me is how organizations turn financial information into better decisions. Most institutions do not lack data; the challenge is determining which information matters, whether it can be trusted and who is responsible for acting on it. My advisory experience taught me to ask where information comes from, how it is reconciled and what decision it supports. Business school broadened that perspective to include strategy, capital allocation and organizational incentives. Ultimately, I am interested in closing the gap between having information and making a sound, explainable decision with it.
Your work covers finance, compliance and technology. What connects these areas?
Adesanya: They are different parts of the same decision system. Finance helps an organization understand where resources are going and where risks are emerging. Compliance establishes the boundaries within which decisions are made. Technology helps process information and execute decisions at scale. Problems arise when organizations treat them separately. A sophisticated dashboard has limited value if teams use inconsistent definitions, just as a strong policy has limited value if it is not embedded in daily processes. I therefore start with the decision: what are we trying to decide, what information supports it and what controls make the outcome reliable?
Banks already use credit scores. What does predictive analytics add?
Adesanya: Potentially, greater context. Predictive analytics can help institutions identify patterns in repayment behaviour, cash flows and other relevant information that may not be fully captured by traditional measures. But greater complexity does not automatically mean better lending. The key question is whether the model produces demonstrably better decisions for the population on which it is used. That requires testing data quality, comparing performance with existing approaches, understanding where errors occur and monitoring results over time. A more sophisticated model can still be a worse model.
For Nigerians with irregular incomes or limited formal credit histories, what would responsible assessment look like?
Adesanya: Institutions should distinguish between limited documentation and limited ability to repay. A small-business owner may have seasonal income, uneven expenses or records spread across several channels. That does not necessarily mean the business is financially weak. Relevant cash-flow information can help lenders understand the underlying pattern, provided the data is accessed and used appropriately. But inclusion cannot simply mean approving more loans. Institutions still need to assess affordability and give customers a practical way to correct inaccurate information or challenge errors.
In March 2025, revised Central Bank of Nigeria rules increased the charges customers could face when using another bank’s ATM. If digital banking is supposed to widen financial access, how should banks assess whether transaction costs are disproportionately affecting lower-income customers?
Adesanya: Start with how customers actually use the service. The same charge can affect someone making one large withdrawal very differently from someone making several small withdrawals throughout the month. Banks should examine transaction frequency, average transaction size, complaints, failed transactions and whether customers genuinely have practical alternatives. It is easy to say customers can use a mobile app, but that assumes reliable connectivity, confidence using digital channels and sufficient merchant acceptance. Financial inclusion should ultimately be measured by customer outcomes, not simply the availability of digital products.
Your research includes digital twins for financial risk. Explain the practical use without the technical language.
Adesanya: I think of it as a structured way to ask “what if?” before an institution experiences the outcome in the real world. A team can create a representation of a portfolio or financial process and test how it responds to different conditions, such as slower collections, higher funding costs or changing customer demand. That can help management identify sensitivities before changing policy or allocating capital. But a simulation is only as useful as its assumptions. Digital twins should support judgment, not replace it.
What lesson from your PwC work matters most for institutions adopting automation?
Adesanya: Document the process before you automate the process. Many operational problems begin with inconsistent inputs, unclear ownership or teams using different definitions. Automating that environment does not solve the problem; it simply allows the problem to operate faster. Before introducing technology, teams should agree on the information required, how it is validated, the sequence of approvals and who owns exceptions. Good automation begins with process discipline.
How should a finance leader prove an automation project delivered value?
Adesanya: Establish the baseline before implementation. How long does the current process take? How often do errors occur? How much rework is required? What does the process cost? Then compare those measures after implementation while accounting for changes in transaction volume, staffing and other conditions. I would also measure more than speed. If a credit process becomes faster but defaults or customer complaints increase, the overall result may not represent an improvement. Leaders should evaluate both efficiency and outcome quality and distinguish clearly between measured results and estimates.
In September 2025, the Central Bank of Nigeria cut the Monetary Policy Rate from 27.5 per cent to 27 per cent. For a small-business owner, does that necessarily translate into cheaper credit?
Adesanya: Not necessarily. The Monetary Policy Rate is important, but banks also consider funding costs, operating expenses, expected credit losses and the individual borrower’s risk profile. For the small-business owner, the practical questions are simpler: what interest rate am I actually being offered, what fees am I paying and can my cash flow support the repayment schedule? Better analytics can help distinguish a seasonal business from a financially distressed one, but it cannot eliminate broader funding costs. The real test is whether monetary-policy changes eventually translate into better lending terms for businesses and households.
Nigerian banks have until 31 March 2026 to meet the Central Bank of Nigeria’s new minimum capital requirements. As institutions raise capital, what should customers and regulators examine beyond whether a bank reaches the required threshold?
Adesanya: Raising capital and managing capital are different disciplines. Additional capital gives a bank greater capacity to absorb losses, but management still has to decide how that capital will be deployed. Regulators should examine concentration risk, the credibility of stress tests and whether boards receive reliable risk information early enough to act. Customers should also pay attention to continuity of service and communication, particularly if recapitalisation results in restructuring or consolidation. Meeting the capital requirement matters, but the longer-term test is whether stronger capital is accompanied by disciplined allocation, effective governance and stronger risk management.
Your publication interests range from banking automation to related-party transactions. How does research influence your practice?
Adesanya: Research makes me more precise about claims. In business, we might say a process reduced errors or a technology improved efficiency. Research forces the next questions: which errors, over what period and compared with what baseline? That discipline helps separate evidence from an attractive narrative. Professional experience provides the opposite test: an idea can appear strong conceptually but be difficult to implement because the data is unavailable, the process is too complex or incentives are misaligned. Research helps me challenge assumptions; practice tests whether an idea can actually work.
What do you want the next phase of your work to focus on?
Adesanya: I want to continue working at the intersection of financial risk, analytics, strategy and governance, particularly as financial institutions rely more heavily on automated and model-assisted decisions. There is significant potential to make financial decisions faster, more consistent and better informed, but greater automation also raises important questions about model evaluation, exceptions and accountability. I want to contribute to approaches that are analytically strong and practical enough for institutions to understand, evaluate and implement. For customers, progress should mean clearer decisions, fewer avoidable errors and a meaningful route to resolve problems. For institutions, it should mean better information, stronger controls and decisions supported by evidence.