 Follow Us on Google News


 Follow Us on Google Discover
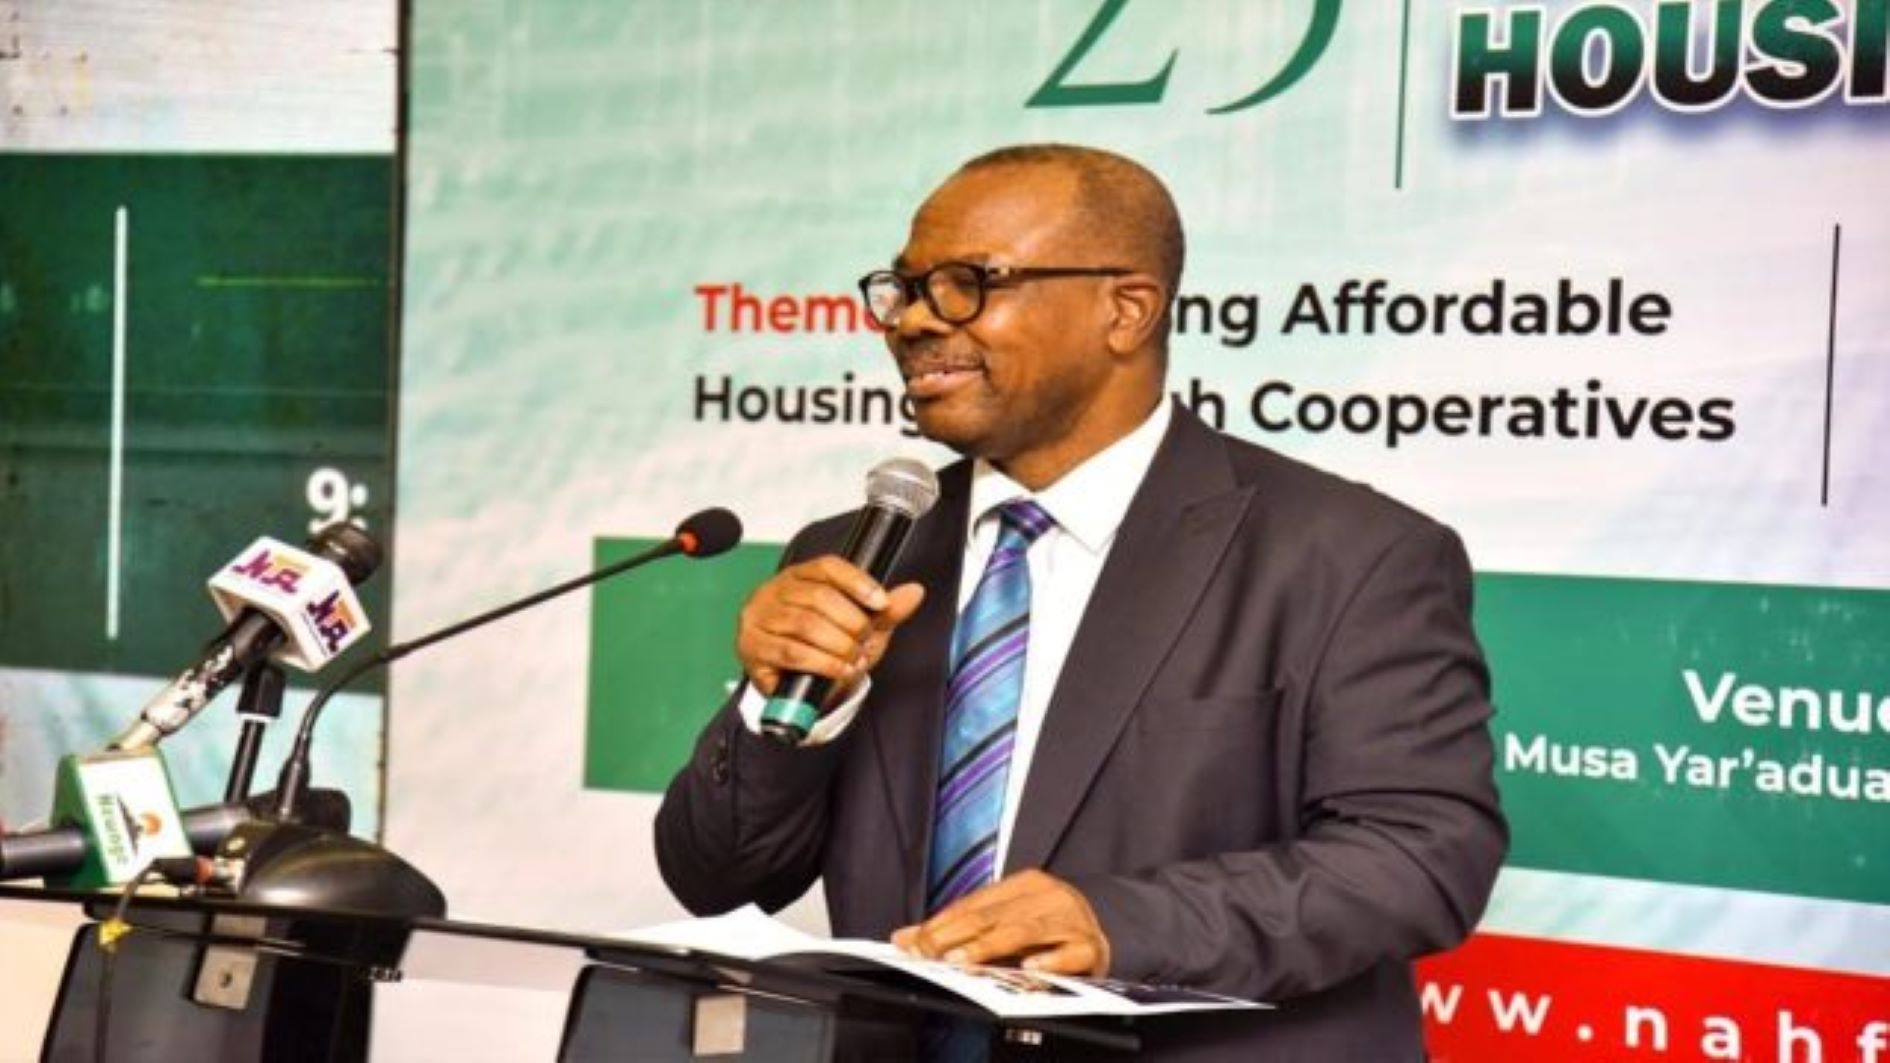
The Cooperative Housing Federation of Nigeria (COHFON) has advocated housing vouchers, guarantees and innovative financing mechanisms to help prospective homeowners access funding and reduce intermediaries in housing delivery.
The federation’s President, Dr Yemi Adelakun, made the call in a paper titled Cooperative Housing in Nigeria, presented at the National Cooperative Summit, Expo and Awards organised by the Cooperative Federation of Nigeria in Abuja.
He urged governments to facilitate partnerships with prequalified engineering, procurement, construction and finance companies with proven technical and financial capacity to deliver pre-designed homes at agreed prices.
Backed by credible guarantees from organised housing cooperatives, such arrangements could help societies that own land but lack the technical expertise or financial resources to develop it.
Adelakun also called for a dedicated revolving intervention fund to provide housing finance through cooperatives at single-digit interest rates, building on the Federal Mortgage Bank of Nigeria’s (FMBN) Cooperative Housing Development Loan programme.
He said the measures would connect organised housing demand with developers, financial institutions and government support, creating a more predictable market for affordable homes.
Acknowledging existing government-backed housing finance initiatives involving the FMBN, Family Homes Funds, the Federal Government Staff Housing Board and the Mortgage Refinance and Investment Fund (MREIF), Adelakun cited interest rates of six per cent, five per cent, three per cent and 9.75 per cent, respectively.
He, however, maintained that government institutions alone could not meet Nigeria’s housing needs, particularly given the limited number of households that qualify for available mortgage products. He urged governments to introduce additional financing mechanisms for informal-sector workers and other underserved groups, while providing land equity to support affordable housing development.
Adelakun, who is also the convener of Cooperative Housing Summit Africa (CHOSA), said cooperative housing could expand homeownership, particularly among households excluded from conventional mortgage financing.
He explained that pooling members’ savings, aggregating demand and developing suitable financing arrangements could address persistent barriers, including high construction costs, expensive credit, limited access to land and inadequate mortgage guarantees.
According to him, the model brings prospective homeowners together before construction begins, enabling developers and financiers to work with organised groups whose housing needs, affordability levels and financial commitments have been established.
This, he said, could reduce the risk of developers building homes beyond buyers’ reach while helping cooperatives negotiate better prices, improve construction quality and secure more reliable delivery arrangements.
“Nigeria does not only need more houses; Nigeria needs better mechanisms for organising people, savings, land, finance and housing supply into a coherent pathway to homeownership,” Adelakun said.
He argued that cooperative housing could convert individual housing needs into collective purchasing power, small savings into housing equity and fragmented demand into projects capable of attracting financing.
Adelakun noted that conventional mortgage products remained inaccessible to many Nigerians, particularly artisans, market traders, artists and other self-employed people whose irregular or difficult-to-verify incomes often prevent them from meeting lenders’ eligibility requirements.
Housing cooperatives, he said, could bridge this gap by mobilising savings and equity contributions, strengthening members’ financial profiles and providing collective guarantees to attract lenders and reputable construction firms.
The model could also enable members to acquire land and residential properties individually or collectively, or participate in housing projects through investments in shares and other approved financial arrangements.
He stressed, however, that cooperative housing should not be confused with conventional savings and thrift societies. Existing multipurpose and sectoral cooperatives could instead partner with specialised housing cooperatives to address members’ housing needs.
He identified good governance, transparency, accountability, capable leadership and sound financial management as critical to the success of cooperative housing schemes.
Adelakun disclosed that COHFON was working with Proppay, a digital finance infrastructure provider for the housing ecosystem, to advance its digital finance agenda. The federation also plans to support the development of cooperative digital banking, linked to the proposed Cooperative Bank of Nigeria, to facilitate the management of the Cooperative Housing Fund.
Other priorities include aggregating savings and equity contributions, developing bankable guarantees and escrow arrangements, and establishing special-purpose vehicles to connect organised housing demand with credible developers and financiers.
He said the model required collaboration among governments, financial institutions, developers, technology providers and communities under what he described as Public, Private and People Partnerships.
Under the framework, governments would provide enabling policies and infrastructure, financiers would develop suitable products, developers would deliver homes efficiently, and cooperatives would organise prospective homeowners and mobilise their resources.
Adelakun said housing development could contribute to economic growth, job creation, poverty reduction, improved public health and better living standards if supply were linked to effective demand and sustainable financing.
“The task now is to connect these instruments more effectively,” he said, referring to existing housing finance mechanisms, including the National Housing Fund and the FMBN’s mortgage, construction, rent-to-own and cooperative housing products.
He said cooperative housing should evolve beyond societies building homes for their members to establishing integrated systems linking savings, land acquisition, housing production and long-term financing.
For the model to succeed, he added, cooperative housing organisations must demonstrate sound governance, protect members’ contributions and build the confidence needed to attract investment.
He said the priority was to organise housing demand, aggregate savings, secure land, mobilise finance, improve construction efficiency and protect homeowners.