 Follow Us on Google News


 Follow Us on Google Discover
As Nigerian businesses increasingly engage in international trade, the reliability of cross-border payment systems has become an important consideration for companies paying overseas suppliers and receiving funds from international customers.
For businesses, payment delays can disrupt cash flow, affect supplier relationships, and create uncertainty about whether funds have reached their intended destination.
Addressing these challenges requires more than developing applications that initiate payments. It involves building the underlying infrastructure capable of managing complex transactions, recovering from technical failures and preventing duplicate transfers.
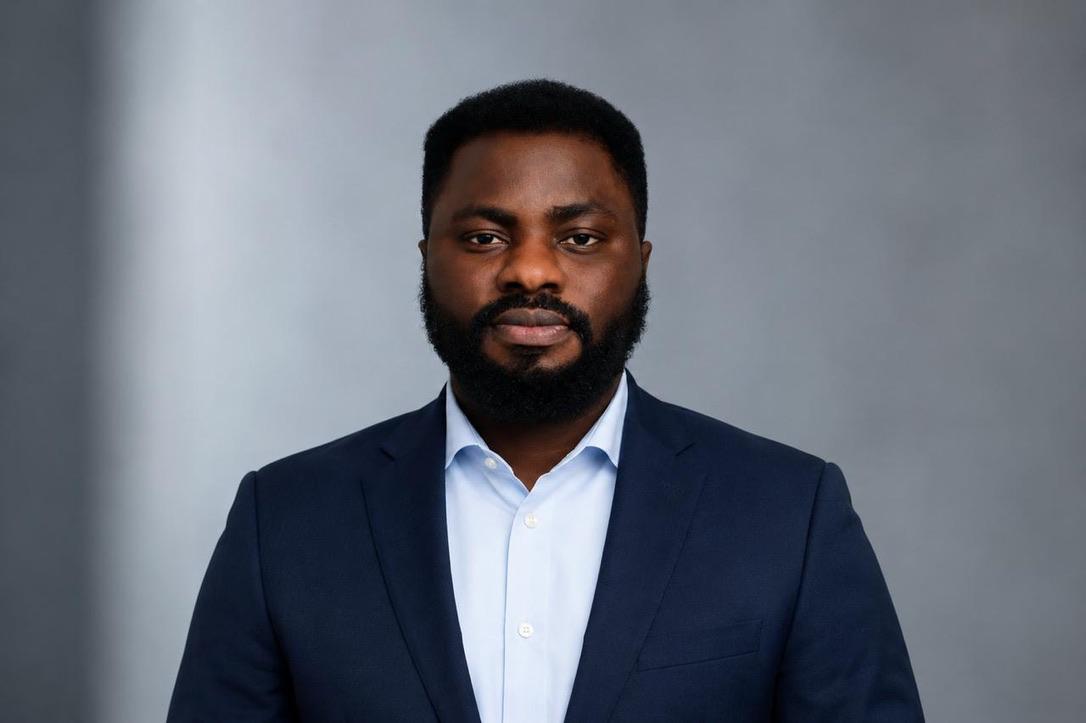
Nigerian software engineer Henry Ese Ivwighre, who is based in the United Kingdom, has contributed to this area of financial technology through his work on international payment infrastructure.
As a principal software engineer, Ivwighre has worked on payment orchestration, transaction reliability, provider integration, and system monitoring, addressing engineering challenges that influence how cross-border payment platforms operate.
Cross-border payment platforms often depend on multiple banks and financial service providers, each operating with different technical interfaces, processing requirements and transaction reporting systems.
These differences can create challenges when payment platforms attempt to coordinate transactions across several providers.
For example, one provider may confirm a transfer immediately, while another may take longer to communicate the outcome. Network interruptions can also make it difficult to establish whether a transaction has been accepted or rejected. Ivwighre addressed these challenges by designing a common architecture that introduced standardised provider interfaces and consistent transaction states.
The architecture established a shared framework through which internal services could initiate, route and monitor transactions while accommodating the different operating requirements of individual payment providers.
This approach helped reduce inconsistencies in how transactions were handled across the platform and provided a reusable foundation for integrating additional payment partners.
For financial technology platforms operating across multiple markets, such architectural consistency is important for maintaining reliable transaction processing as payment networks expand.
One challenge in digital payment processing is deciding how a system should respond when a transaction encounters a temporary failure.
A network timeout does not necessarily mean that a payment has failed. In some cases, the receiving provider may have accepted the payment instruction even though the originating platform has not received confirmation.
Attempting the same transaction again without establishing its status could result in an unintended duplicate payment.
Ivwighre’s engineering work included developing controlled retry mechanisms and implementing safeguards designed to prevent repeated payment instructions from creating additional transactions.
An important component of this work involved idempotency, a software engineering principle used to ensure that repeated requests do not unintentionally produce duplicate financial operations.
His contributions also included mechanisms for routing eligible transactions through alternative payment providers when the original route could not complete them.
Such recovery processes require careful assessment of transaction status before another payment attempt is made.
These safeguards are particularly relevant to businesses conducting international transactions, where duplicate payments or unresolved transfers can create financial and operational difficulties.
Beyond payment processing and recovery, Ivwighre has also worked on improving the visibility of transactions across interconnected financial systems.
A single international payment may pass through several internal services before reaching an external payment provider.
When delays or errors occur, engineering and operations teams need reliable information to determine what happened and identify appropriate recovery actions.
Ivwighre improved transaction tracing and monitoring to help teams follow payment instructions across different services and identify processing difficulties more clearly.
Combined with consistent transaction states, these improvements helped establish a more coherent record of payment activity.
This visibility is important for investigating delayed transfers, understanding provider responses and supporting accurate communication with customers.
For businesses depending on international payment services, the ability of a provider to explain transaction status can be as important as the speed at which a transfer is initiated.
As fintech companies expand into new markets, integrating additional payment providers can introduce new engineering challenges.
Each provider may require different connection methods, transaction formats and error-handling procedures.
Without a consistent architectural approach, these integrations can increase the complexity of maintaining and extending a payment platform.
Ivwighre’s work on standardised provider interfaces helped establish a reusable framework for connecting payment partners.
By separating provider-specific requirements from common payment processing operations, the architecture enabled internal services to interact with different providers through a more consistent approach.
The design also provided a foundation for future integration work as payment connectivity expanded.
This reflects an important consideration in financial technology engineering: infrastructure must be designed not only to address existing operational requirements but also to accommodate future changes.
Developing reliable payment infrastructure involves more than architectural design.
Financial technology platforms must also manage the risks associated with software releases, system disruptions, and changes to external services.
Ivwighre’s work extended to technical design reviews, gradual software releases and improvements to incident response arrangements.
These practices help engineering teams identify potential risks, monitor the effects of system changes and investigate disruptions when they occur.
In payment systems, where technical problems may affect financial transactions, such operational discipline is an important part of maintaining service reliability.
As Nigerian businesses develop commercial relationships with international customers and suppliers, dependable cross-border payment services remain an important part of digital commerce.
Although transaction costs and processing speed often influence the choice of a payment provider, reliability and transparency become particularly important when a transfer encounters difficulties.
Businesses need payment platforms capable of tracking transactions, identifying processing problems and recovering from disruptions without creating additional financial exposure.
The engineering challenges addressed in Ivwighre’s work demonstrate the importance of building financial systems that can manage these requirements.
His contributions to provider integration, transaction recovery, payment orchestration and operational monitoring illustrate the technical work involved in supporting dependable international payment services.
As Nigeria’s fintech ecosystem continues to develop, the reliability of the underlying infrastructure will remain an important consideration for businesses seeking to participate confidently in international markets.