 Follow Us on Google News
 Follow Us on Google Discover
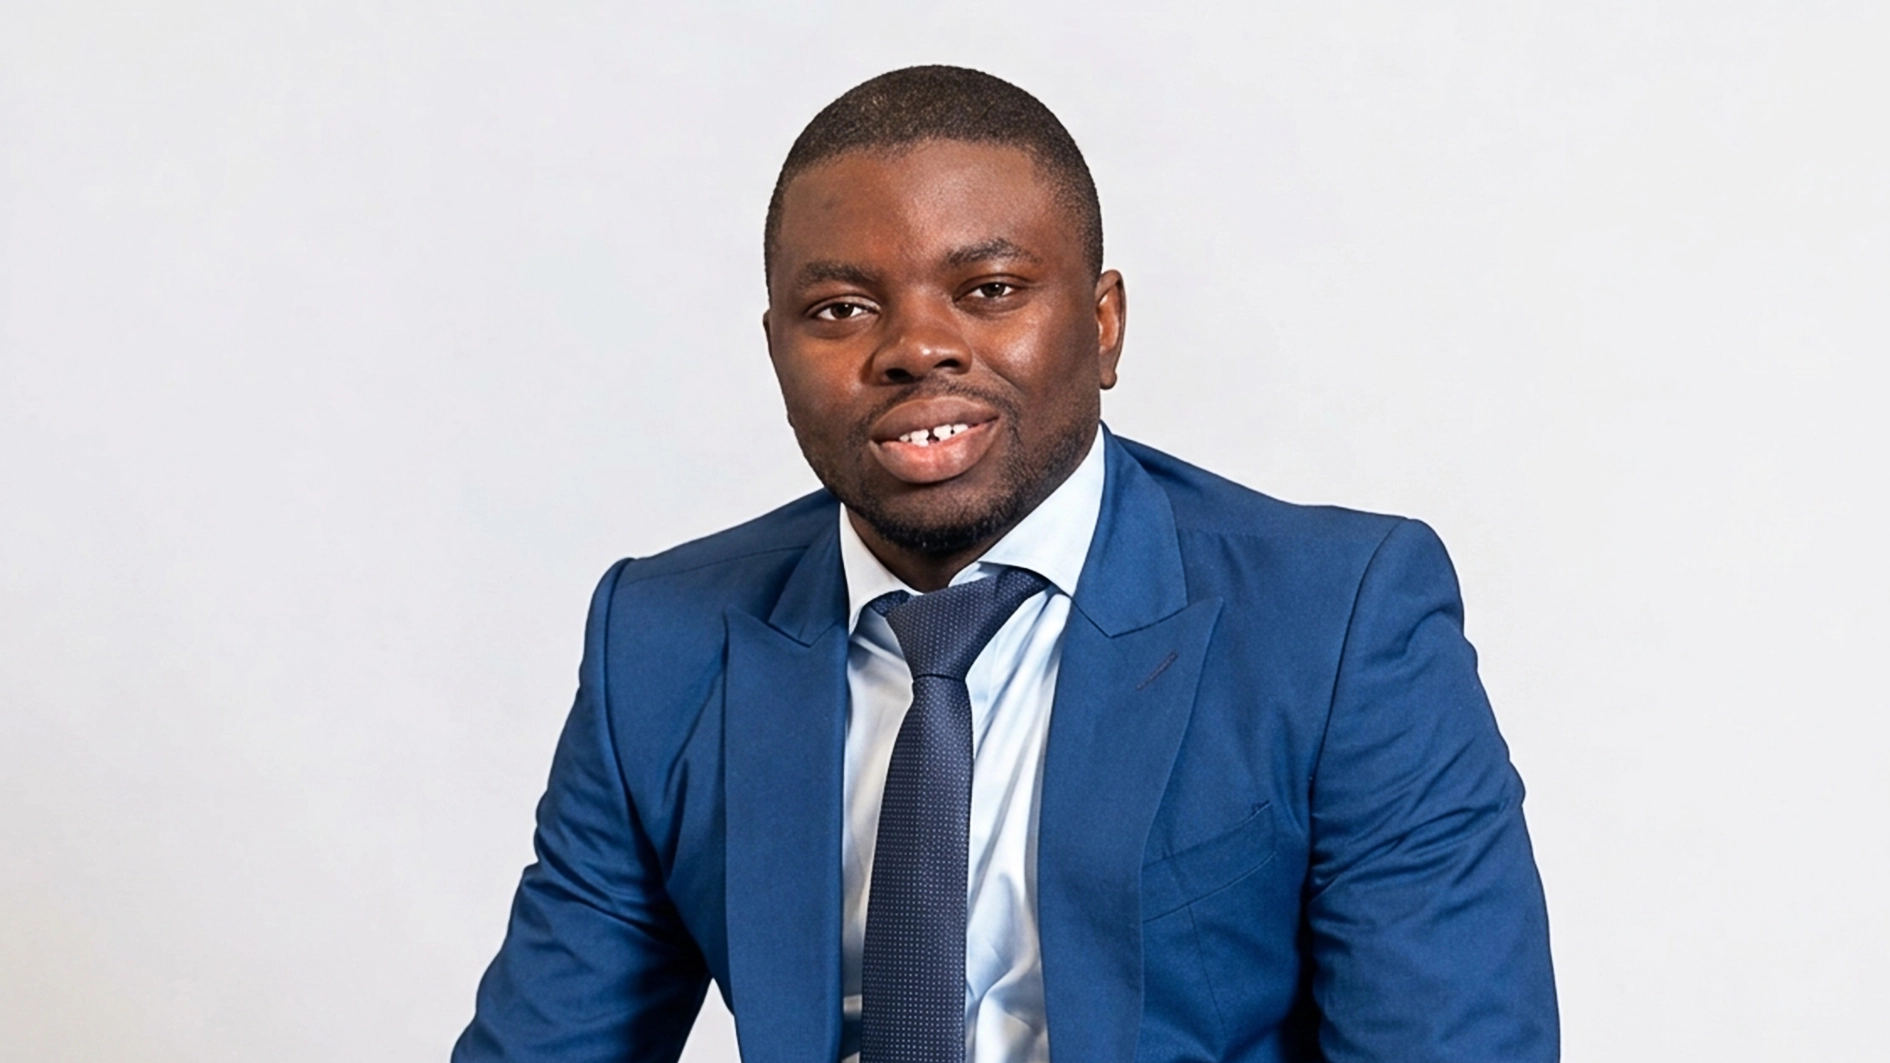
Amid the growing struggle by Nigerian small and medium-sized enterprises (SMEs) to access finance in an economy marked by rising costs and tighter borrowing conditions, a former commercial bank Relationship Manager, Michael Soetan, has urged business owners to put their finances in order before approaching lenders.
In a paper he shared with this medium, Soetan said, “for many SMEs, the greatest obstacle is not access to finance—it is financial preparedness,” stressing that entrepreneurs must be able to present credible financial information and demonstrate their capacity to repay before seeking business loans.
According to him, “banks lend on confidence, and confidence is built on credible financial information,” which includes accurate financial records, realistic projections, healthy cash flow and a clear plan for how borrowed funds will be invested and repaid.
Reflecting on his years as a Relationship Manager at one of Nigeria’s leading commercial banks, where he reviewed countless SME loan applications, Soetan said many business owners approached banks with promising ideas and strong passion for their businesses, but only a small proportion met the lending criteria.
That experience taught me an enduring lesson: for many SMEs, the greatest obstacle is not access to finance—it is financial preparedness.
Many business owners assume that a good product or a loyal customer base is enough to secure a loan. Unfortunately, lending decisions are not based on passion alone.
Banks lend on confidence, and confidence is built on credible financial information. It comes from accurate financial records, realistic projections, healthy cash flow, and a clear, practical plan for how borrowed funds will be invested and repaid.
One of the most common weaknesses I encountered was poor financial planning.
Many applicants could not produce up-to-date financial statements or clearly explain their monthly cash flow. Others had no formal budget and routinely mixed personal expenses with business finances. Some could not convincingly demonstrate how the requested loan would increase revenue, improve productivity, or strengthen profitability.
When these gaps exist, approving a loan becomes difficult—not because the business lacks potential, but because the lender has insufficient evidence to properly assess the risk.
This is why every SME should develop a sound financial strategy before applying for a business loan.
A financial strategy is more than a budget. It is a roadmap that outlines how a business will generate revenue, manage expenses, maintain healthy cash flow, and deploy borrowed funds to achieve sustainable growth.
Consider two entrepreneurs applying for the same ₦50 million loan. One simply says, “My business is doing well, and I need funds to expand.” The other submits audited or well-prepared financial statements, realistic financial projections, a detailed cash flow analysis, and a convincing explanation of how the loan will increase production, sales, and profitability.
The choice for any lender is obvious.
The difference is not the business idea.
The difference is preparation.
Poor cash flow management was another recurring challenge. Many businesses recorded impressive sales yet struggled to pay salaries, suppliers, rent, and other operating expenses because they failed to effectively manage the movement of cash into and out of the business. A company can appear profitable on paper and still fail because it runs out of cash.
Nigeria’s current economic realities make financial planning even more essential. Rising inflation, exchange rate volatility, increasing production costs, and higher borrowing costs mean business owners can no longer afford to make financial decisions based on instinct or guesswork. They must understand their financial position, prepare realistic budgets, and plan for changing economic conditions.
Fortunately, technology has made this easier than ever. Affordable accounting software, digital payment platforms, and mobile banking applications now enable SMEs to maintain proper financial records and monitor business performance in real time. However, technology is only an enabler. What matters most is how business owners use the information to make sound financial decisions.
From my years in commercial banking, one lesson remains clear: banks genuinely want to finance viable businesses because successful enterprises drive economic growth, create jobs, and stimulate development. But every lending decision must ultimately be grounded in trust, credible evidence, and the borrower’s demonstrated capacity to repay.
Perhaps it is time we changed the conversation.
Instead of asking, “Why are banks not lending?” we should begin asking, “Are our businesses truly ready to receive funding?”
Financial planning is not a cost—it is an investment in the future of every business. SMEs that maintain accurate financial records, understand their numbers, manage cash flow effectively, and pursue realistic growth strategies will always stand a stronger chance of securing finance than those that rely on optimism alone.
After years of evaluating SME loan applications, I have reached one simple conclusion: funding rarely goes to the business with the biggest dream—it goes to the business that is best prepared.
And every well-prepared business begins with a sound financial strategy.