 Follow Us on Google News
 Follow Us on Google Discover
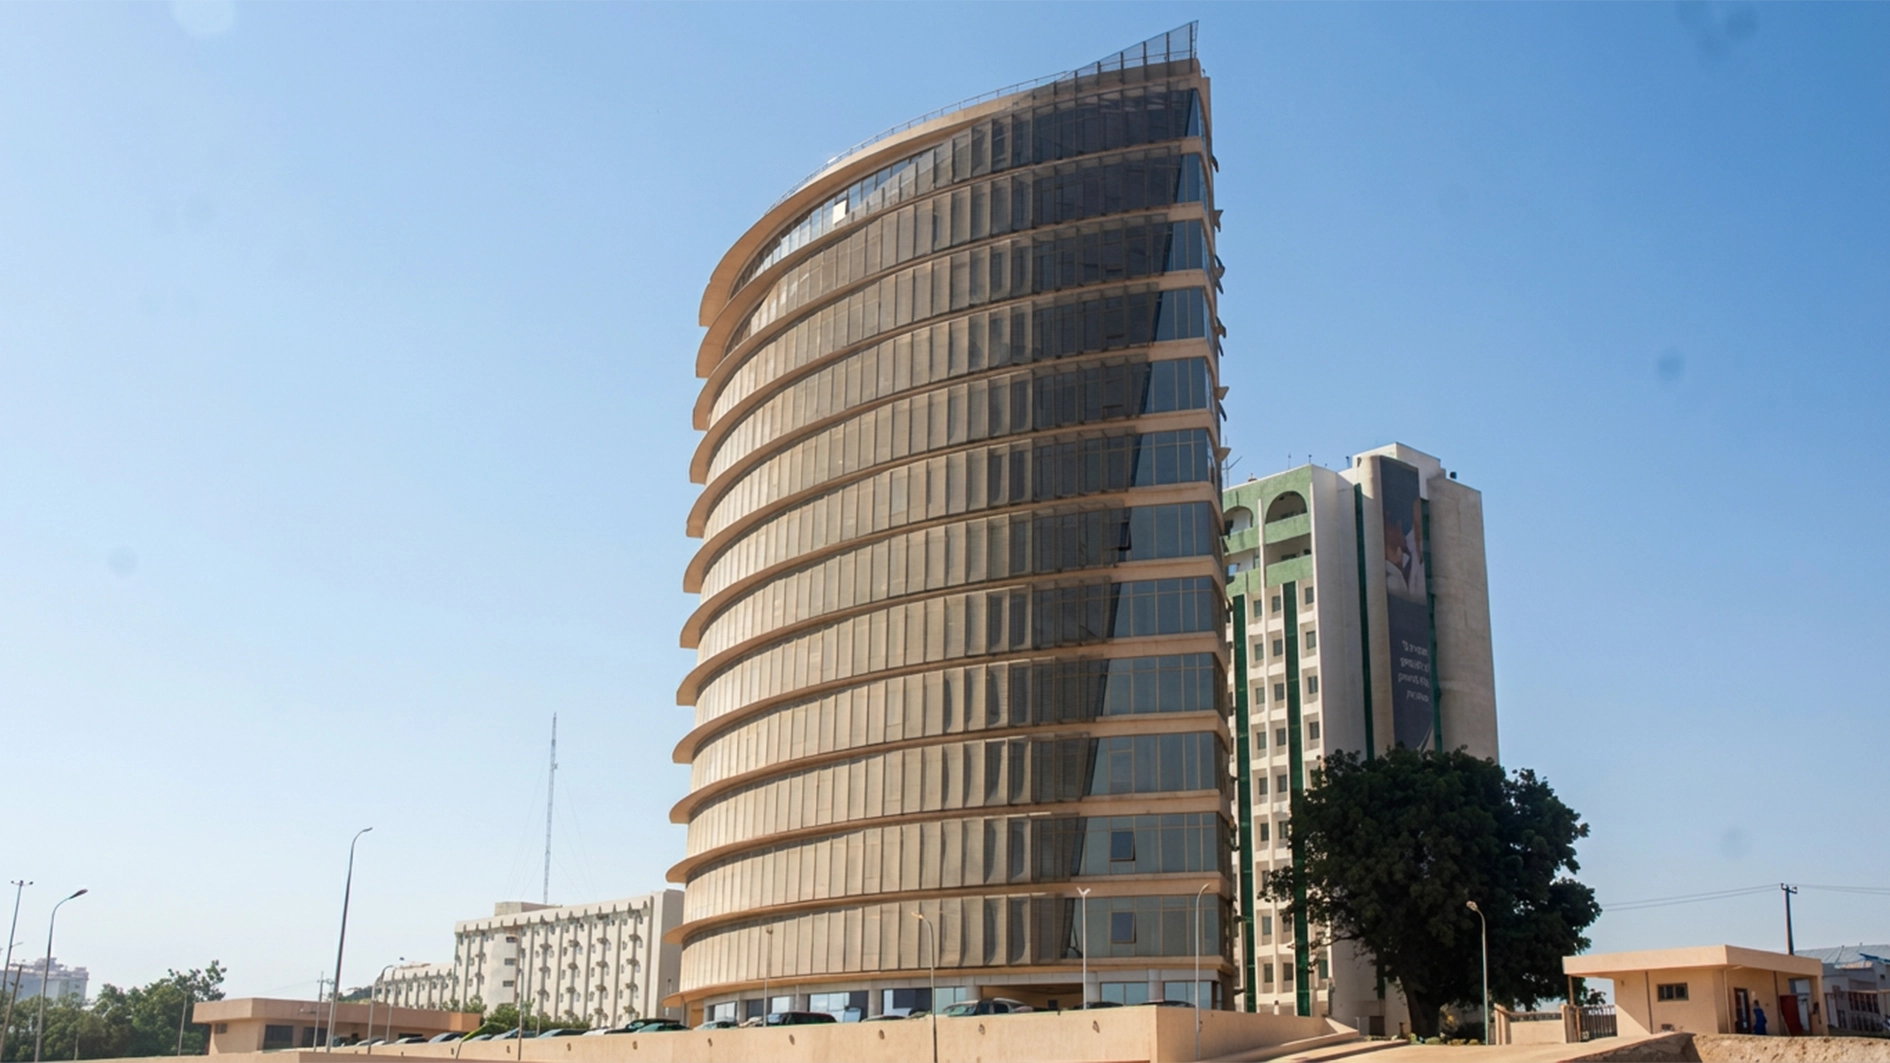
Nigeria’s industrial ambitions will not be realised through policy declarations alone. They require patient capital, competent institutions and a financial system capable of converting savings into factories, machinery, technology, jobs and competitive businesses. The Bank of Industry’s (BOI) recent N274.1868 billion Series 1 Development Bond is therefore more than a financing transaction. It is a test of whether Nigeria can mobilise domestic capital for productive investment and whether a development-finance institution can translate investor confidence into broad-based economic transformation.
The five-year fixed-rate bond, priced at 17.60 per cent and due in 2031, reportedly attracted strong institutional demand and was oversubscribed within five working days. Pension fund administrators, banks, development finance institutions, corporates, and other investors participated in the offer, with the Nigeria Sovereign Investment Authority and the International Finance Corporation among the reported institutional anchors. The result is a vote of confidence in BOI.
It is also an endorsement of the capacity of Nigeria’s domestic capital market to provide long-term naira financing for the productive economy. But the bond is only a means to an end. Its success must ultimately be judged not by the amount raised, or even by the speed of subscription, but by what the capital achieves. Does it expand productive capacity? Does it help businesses create and retain jobs? Does it strengthen local supply chains, increase exports, support women and young entrepreneurs, and reduce dependence on imported goods? Those are the questions that should define the transaction’s real value.
For many years, BOI has built a significant record of accessing international financial institutions and global capital markets. That international funding remains important, particularly for infrastructure, industrial expansion and programmes requiring foreign currency. But a development-finance institution with a predominantly Nigerian mandate must also cultivate reliable access to domestic long-term capital.
The reason is straightforward. Many Nigerian businesses earn their revenues in naira. Financing them with long-term naira liabilities reduces the risk that exchange-rate movements will render otherwise viable projects unmanageable. It also allows BOI to align the currency and tenor of its funding with the needs of the manufacturers, farmers, processors, technology firms and service providers it supports.
A deeper domestic capital market provides benefits beyond BOI. It allows pension funds, insurers, asset managers and other institutional investors to participate more directly in Nigeria’s development while holding instruments suited to their risk and return requirements. It also creates a channel through which the country’s pool of institutional savings can support long-term enterprise rather than remain concentrated in short-term or government-related assets. This is the central logic of modern development finance. Public institutions do not have sufficient funds to finance development on their own. Their role is to mobilise private capital, share risks, prepare viable projects and invest where commercial finance is either unavailable or too expensive.
The International Finance Corporation, for example, combines direct investment, advisory support, and private capital mobilisation to assist enterprises ranging from microbusinesses to large corporations.
In 2024, multilateral development banks and development-finance institutions mobilised a reported $278.5 billion in private finance. The lesson for Nigeria is clear: the impact of BOI should be measured not only by what it lends, but by what it enables others to invest.
Industrialisation is often associated with large factories, steel plants, cement works and major infrastructure. Those enterprises matter, but industrial growth also depends on thousands of smaller firms that supply components, transport goods, process agricultural products, provide services and employ local workers.
BOI’s importance lies partly in its ability to operate across this spectrum. Large manufacturers require long-term project finance, equipment finance, working capital and support for expansion. Medium-sized businesses need credit to formalise operations, acquire machinery, meet quality standards and enter larger supply chains. Micro and nano enterprises require smaller loans, business advisory services, digital tools and a realistic path towards formal finance.
The bank’s reported interventions reflect this range. It says loans disbursed to enterprises across 14 sectors nearly doubled to N1.3 trillion between 2023 and 2025, while total assets increased from N3.9 trillion to approximately N7 trillion. It also reports support for rural enterprises, women-owned businesses, youth-led ventures and beneficiaries of the Federal Government’s N200 billion grants and loans programme. Programmes such as the Rural Area Program for Investment and Development and the Guaranteed Loan for Women demonstrate an understanding that access to finance must not be limited to established corporate borrowers.
The reported support for rural businesses and women-owned firms is particularly important in an economy where geography, informality, inadequate collateral and unequal access to networks often prevent capable entrepreneurs from obtaining credit.Yet lending figures alone cannot establish development impact. A loan may create a new job, preserve an existing one, refinance a previous obligation or support an enterprise that would have expanded without public assistance.These outcomes have different economic meanings.
BOI’s evolving role is comparable in broad terms to that of institutions such as Brazil’s BNDES, Germany’s KfW and the IFC. These institutions differ in ownership and scale, but successful development banks generally combine long-term finance with technical expertise, risk-sharing, guarantees, equity investment, project preparation and rigorous evaluation.
BOI’s expansion into leasing, guarantees, impact investment, climate finance, and digital enterprise support is encouraging. Industrialisation in the 21st century is not confined to traditional manufacturing. It includes agro-processing, renewable energy, healthcare, logistics, recycling, digital services and creative industries. The bank’s support for innovation hubs, women-owned enterprises, climate adaptation and digital businesses suggests a broader understanding of productive capacity. That is welcome. But the more extensive BOI’s mandate becomes, the more important it is to establish priorities, publish results and prevent resources from being spread too thinly.
To enhance impact, BOI must preserve its institutional independence and credit discipline. Development finance is easily weakened by political interference, opaque beneficiary selection and pressure to lend on non-commercial terms without adequate compensation. Clear eligibility rules, professional underwriting, transparent procurement and strong board oversight are indispensable. Second, concessionary lending should be accounted for openly. Third, Nigeria needs a stronger credit-guarantee system. Many viable small businesses lack conventional collateral, while lenders remain cautious because loan recovery can be slow and expensive. Guarantees can reduce risk and encourage commercial lending, but they must be properly priced, transparently reported and subject to strict controls against moral hazard.
Fourth, credit must be accompanied by enterprise development. Small businesses often struggle not only because they lack access to loans but also because they have weak accounting, limited market access, unreliable power supply, poor management systems, and inadequate technical capacity. BOI should expand support for bookkeeping, certification, digital payments, business planning, productivity improvement and links to large anchor buyers.
Finally, the government must address the conditions that no development bank can solve alone. Unreliable electricity, poor transport networks, port congestion, insecurity, multiple taxation, and regulatory uncertainty can undermine the gains achieved by a well-structured loan. Industrial finance works best when supported by dependable infrastructure and predictable public policy.
BOI deserves credit for recognising that industrialisation requires more than conventional lending. Its domestic bond, growing access to long-term capital and interventions across large, medium, small and informal enterprises represent important progress. Nevertheless, a DFI must show not only how much it mobilised, but where the money went, who benefited, what risks it assumed and what changed as a result.
The N274.18 billion bond should therefore be regarded as a beginning rather than an end. Its ultimate success will be seen in factories that expand, businesses that survive, suppliers that enter formal value chains, exports that rise and jobs that endure. Nigeria needs BOI to be ambitious, innovative and willing to take development risks. It also needs the bank to be transparent, professionally managed and rigorous in measuring results.
If BOI can combine capital mobilisation with accountability, additionality, independent evaluation and serious support for enterprise development, it can help transform Nigeria’s savings into productive capacity. Development financing will ultimately be judged by the industrial future built with mobilised funds.