
 Get Guardian on Google
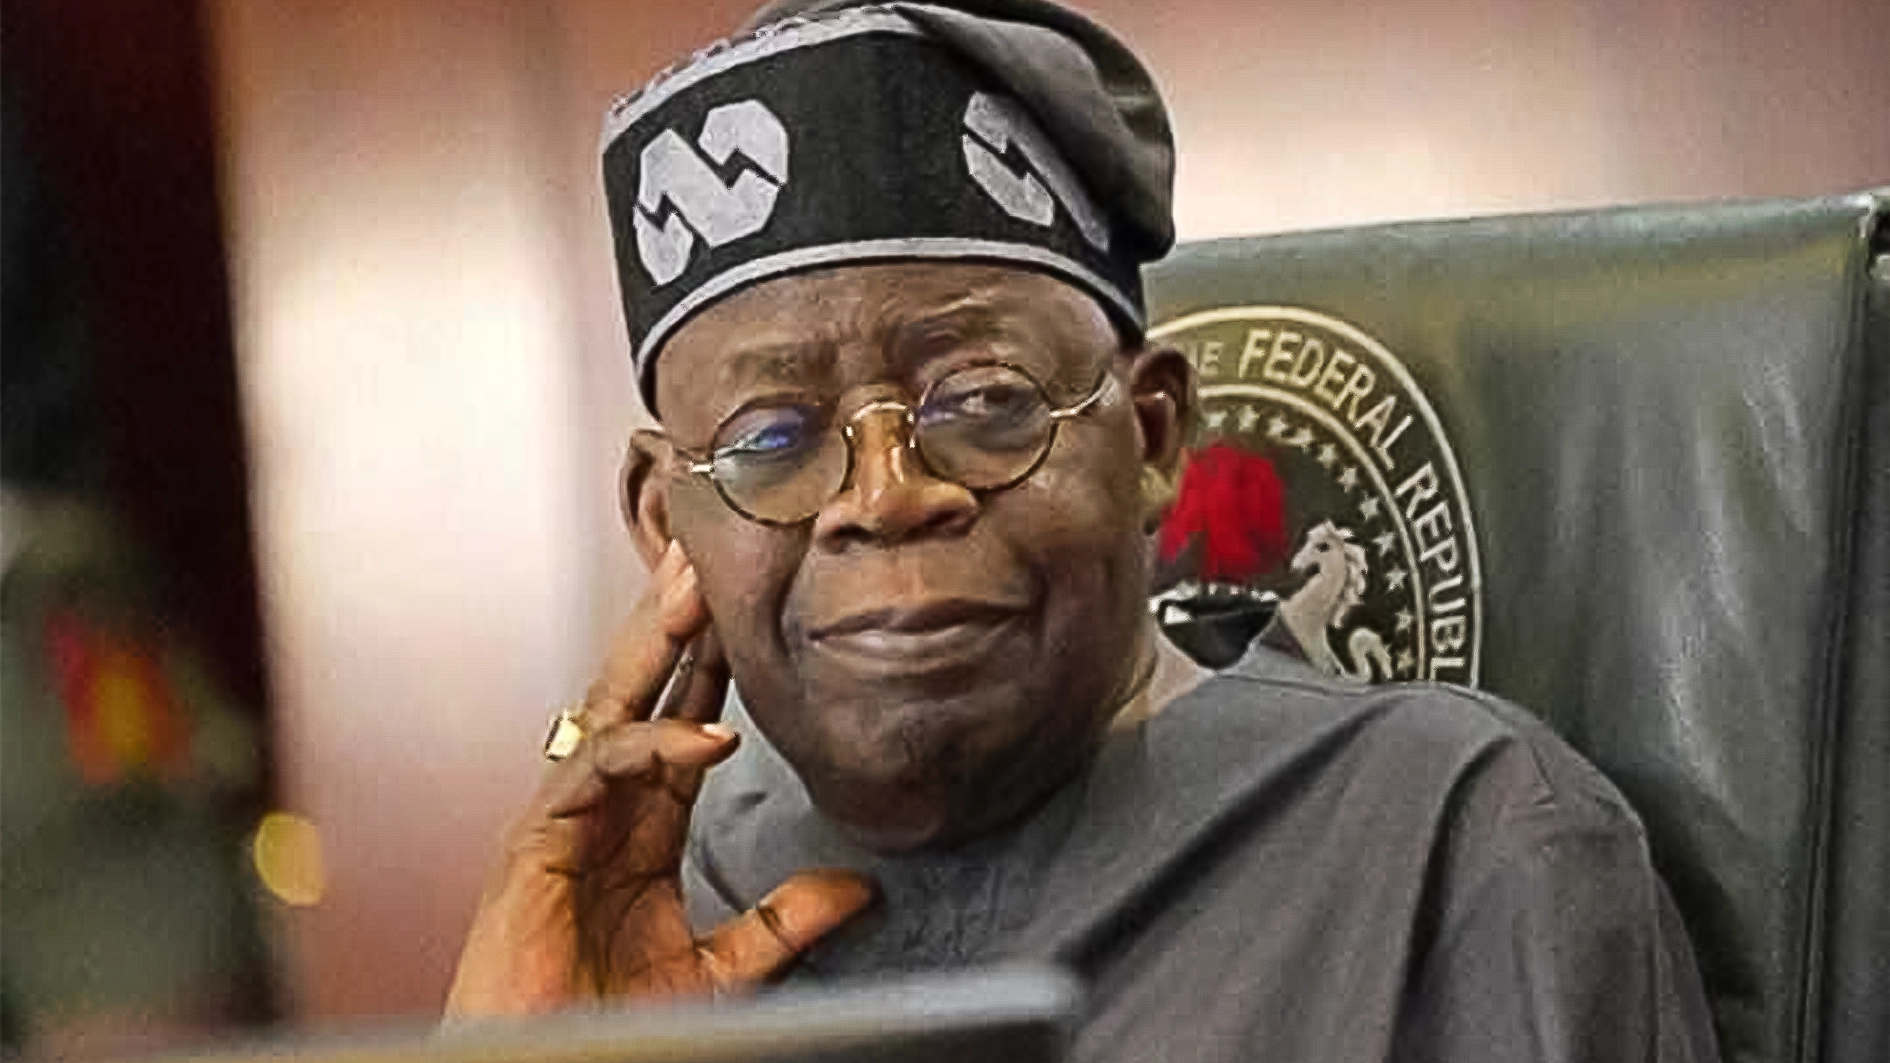
President Bola Tinubu has withdrawn his request for approval of $20.5 billion and €1.05 billion in external loans and replaced it with a smaller proposal of $7.7 billion to part-finance the 2026 budget deficit, with a stated preference for Eurobonds.
In a fresh letter read by Senate President Godswill Akpabio at plenary yesterday, Tinubu sought approval for $7,707,404,882.49, equivalent to about N10.79 trillion at an exchange rate of N1,400 to the dollar.
Akpabio said the new request effectively cancelled the earlier one, which was presented to the Senate last week under the 2026–2027 Supplementary External Borrowing Plan and sought $20.52 billion and €1.05 billion. He described the latest letter as far more explicit than the first.
He referred the request to the Senate Committees on Local and Foreign Debts and Appropriations and directed them to report back as soon as practicable. Akpabio added that the borrowing would not come from a single source, so the government must look for the best terms on a willing-buyer, willing-seller basis.
In the letter, Tinubu said the money would finance projects in infrastructure, defence and security, agriculture, healthcare, power and education, and support the country’s external reserves. He argued that it would also help the naira and sustain the macroeconomic reforms of his administration. The Central Bank of Nigeria is expected to receive the proceeds on behalf of the Federal Government.
The earlier proposal, by contrast, was meant to fund infrastructure, agriculture, healthcare, education, water supply, security, employment generation and public financial management reforms.
The President said the request formed part of the N29.2 trillion borrowing provision in the 2026 Appropriation Act, which is expected to finance a budget deficit of about N31.4 trillion. The provision comprised N18.4 trillion in domestic financing and N10.79 trillion in external borrowing.
The $7.7 billion request represents the external component.
The distinction matters: the new request is not an additional sum on top of the borrowing already provided for in the budget. It is meant to supply financing within the approved external framework.
Tinubu said the government would pursue several options at the same time, including concessional and commercial loans from multilateral and bilateral institutions, the International Monetary Fund, bridge financing, direct borrowing from international financial institutions and Eurobond issuance. Each would be assessed on cost, benefits and the time needed to access the funds.
He, however, indicated a preference for Eurobonds, citing faster execution, the capacity to raise larger amounts and potentially competitive borrowing costs.
“The plan is to raise the new external borrowings of $7.7 billion. I wish to note that all the options will be pursued simultaneously considering the cost and relative benefits to the country and the time required to access the funds,” the letter said.
The President noted that final terms, including interest rates and repayment periods, would depend on market conditions at the time of pricing. He assured the Senate that the Federal Ministry of Finance and the Debt Management Office (DMO) would work to secure favourable terms.
Tinubu said the request was made in line with Sections 21(1) and 27(1) of the DMO Act 2003. Section 21(1) requires that the terms of any external loan be laid before the National Assembly and approved by resolution before the Minister of Finance can obtain it.
The request comes amid concerns over Nigeria’s growing debt and rising servicing costs. DMO data showed that total public debt rose to N166.79 trillion (about $120.93 billion) as of June 30, 2026, from N159.35 trillion at the end of March, an increase of N7.44 trillion in three months. The stock stood at N87.38 trillion in June 2023, when Tinubu assumed office.
Between January and June, the Federal Government spent N7.7 trillion on debt service. The 2026 budget earmarks N15.81 trillion for debt servicing over the full year, roughly 45.2 per cent of projected government revenue.
The National Assembly had earlier approved a $516.3 million Deutsche Bank loan for the Sokoto-Badagry Superhighway. The nine-year facility, which includes a grace period of up to three years, carries an interest rate capped at SOFR plus 5.3 per cent annually.
In March, lawmakers also approved a $6 billion external borrowing plan, comprising a $5 billion facility from First Abu Dhabi Bank to support the budget and a $1 billion UK export finance facility arranged by Citibank for the rehabilitation of Tin Can Island Port and Lagos Port Complex.
Although the new request is substantially smaller, it would still add foreign-currency obligations, with the ultimate cost depending on financing terms, interest rates, repayment schedules and exchange-rate movements.
The government has often defended borrowing as necessary to close Nigeria’s infrastructure deficit. Better roads can reduce transport costs and help farmers reach markets, while more reliable electricity can lower operating costs for manufacturers and small businesses.
The rising debt stock has intensified calls for improved revenue generation and more effective management of borrowed funds, as analysts warn that high debt-service costs could constrain spending on infrastructure and essential public services.
The International Monetary Fund and the World Bank have repeatedly urged Nigeria to raise revenue, improve tax collection and ensure borrowed funds go into productive investments.