 Follow Us on Google News


 Follow Us on Google Discover
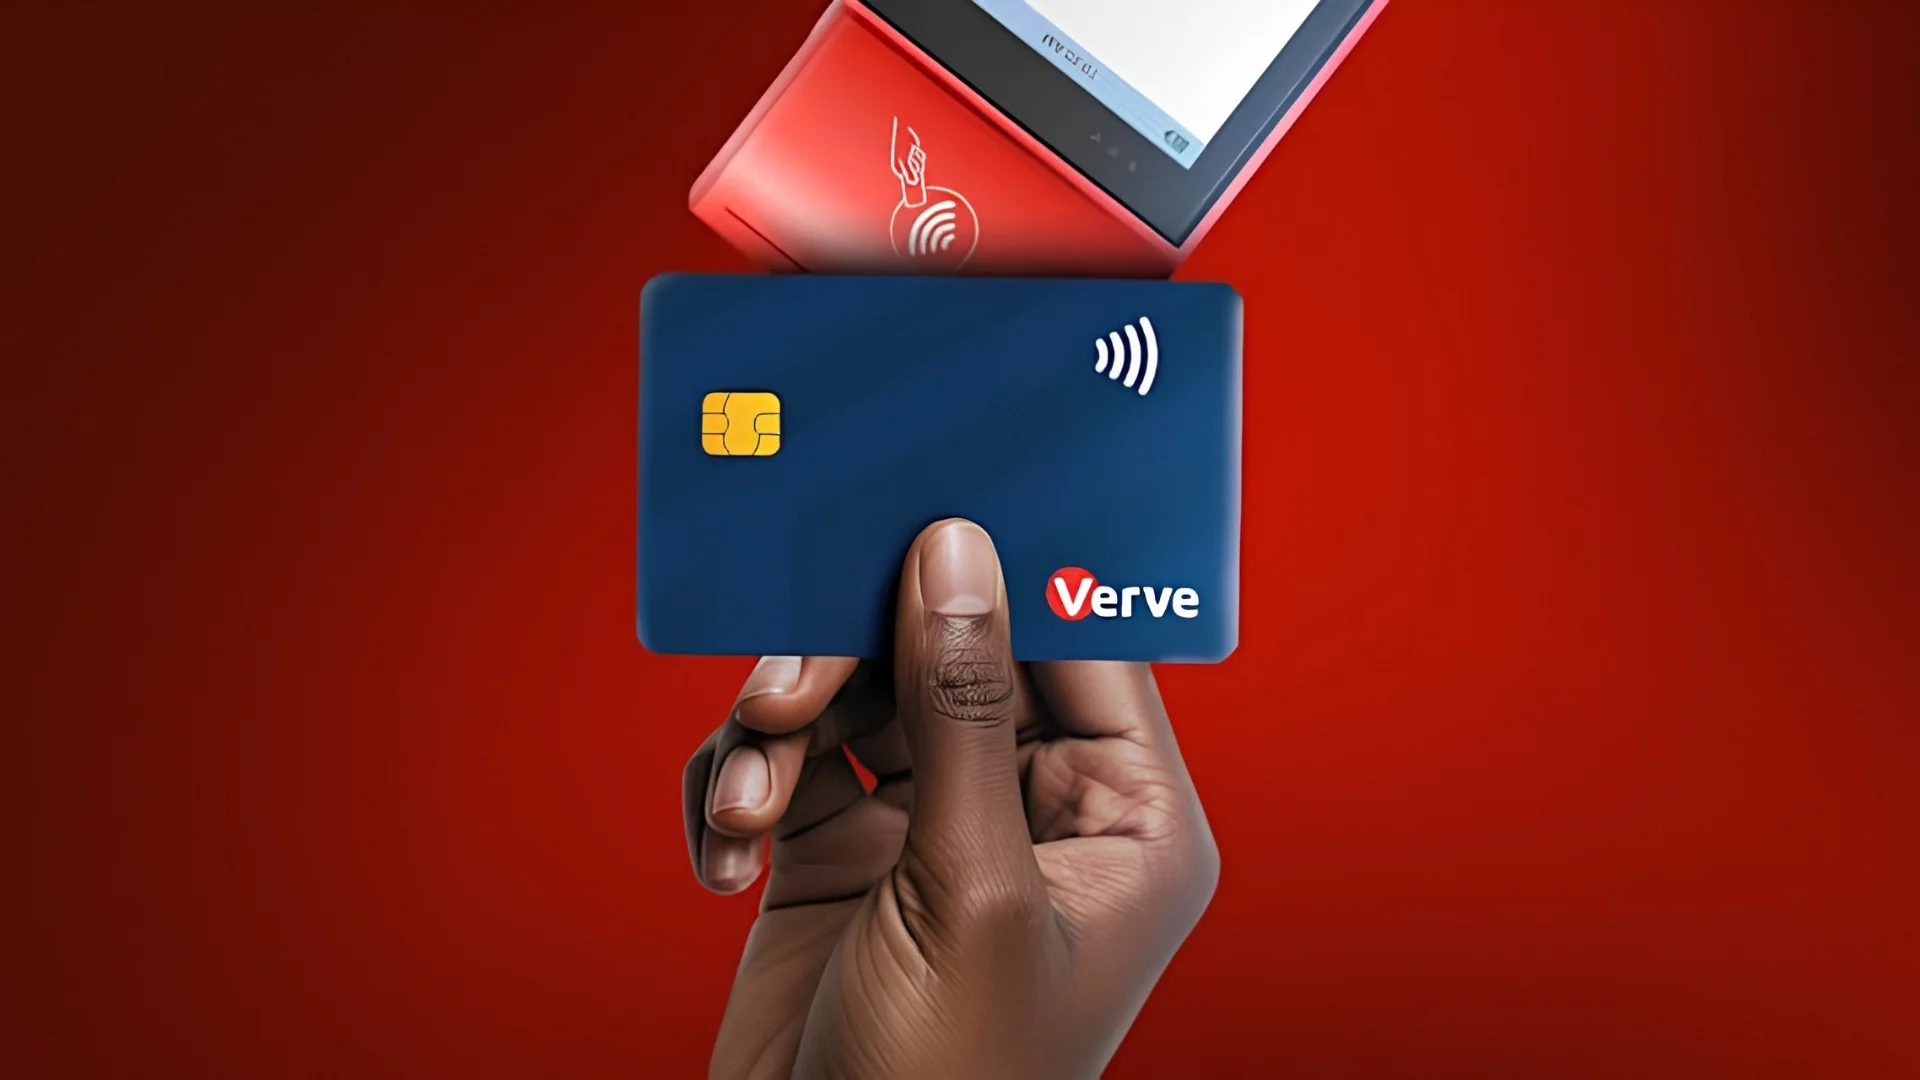
Interswitch Group has outlined plans to expand the infrastructure supporting tokenised digital payments in Nigeria, working with banks, financial institutions, card schemes and merchants to encourage wider adoption of contactless and digital-wallet transactions.
The Nigerian payments technology company said its efforts were focused on enabling financial institutions to deploy payment tokenisation, a security technology that substitutes sensitive card information with digital identifiers during transactions.
According to the company, the initiative is also supporting payment infrastructure development in other African markets, including Kenya and Uganda.
Interswitch said the technology could help financial institutions strengthen transaction security, improve payment processing and provide customers with additional ways to make electronic payments.
The company is seeking to support wider adoption of tap-to-pay and wallet-based transactions by developing the connectivity and processing systems required for banks and merchants to accept them.
How payment tokenisation works
Payment tokenisation is a security process that replaces sensitive payment information, such as a card’s primary account number, with a substitute identifier known as a token.
The token can be used to process an eligible transaction without unnecessarily exposing the underlying card details.
Depending on how a payment system is configured, tokens may be restricted to particular devices, merchants or payment environments.
This can reduce the usefulness of compromised payment credentials and limit the exposure of sensitive information during processing.
Tokenisation is commonly associated with digital wallets and contactless transactions, although the technology is also used in other forms of electronic payment.
Tap-to-pay, meanwhile, generally involves making a contactless transaction by bringing an enabled card or device close to a compatible payment terminal.
The two technologies are related but distinct.
A contactless payment may use tokenised credentials, while tokenisation can also protect transactions that do not involve tapping a device at a terminal.
Interswitch said its infrastructure was intended to help banks, card schemes and merchants support these payment experiences more widely.
Banks, merchants targeted for integration
The company said it was working with multiple financial institutions and payment ecosystem participants to establish the technical connections required for tokenised transactions.
These include issuer connectivity, token management and payment processing capabilities.
Issuing banks play an important role in the process because they provide customers with payment cards and must support the relevant authentication and transaction authorisation arrangements.
Card schemes, payment processors and merchants must also have compatible systems for transactions to move through the payment network successfully.
Interswitch said its role involved supporting these connections and helping participating organisations integrate tokenisation into their existing payment infrastructure.
The company identified improved payment authorisation, reduced exposure of sensitive card information and greater customer confidence among the potential benefits.
Managing Director, Payment Switching and Processing at Interswitch, Akeem Lawal, said collaboration among financial institutions and payment service providers would be important to expanding secure digital payment options.
“Collaboration across the payments ecosystem is essential to expanding secure and accessible digital-payment options in Nigeria,” Lawal said.
He explained that Interswitch was working to provide infrastructure that would allow more financial institutions to support tokenised payments.
According to him, the technology reduces the need for customers’ original payment credentials to be exposed during transactions.
Instead, a substitute identifier can be used within the relevant payment environment.
The security benefit depends on the way the token is issued, restricted, stored and authenticated.
Although a stolen token may be less useful than compromised card details, tokenisation does not eliminate every form of payment fraud.
Other threats, including account takeover, social engineering and unauthorised transactions, still require appropriate safeguards.
Lawal said Interswitch intended to strengthen its relationships with financial institutions and other payment ecosystem participants to support the adoption of contactless and digital-wallet services.
“As Interswitch, we are helping to establish the issuer connectivity, tokenisation and payment processing capabilities required to bring ‘tap-to-pay’ and wallet-based payments to Nigerian consumers,” he said.
He added that the company was seeking to make secure payment experiences more accessible across African markets.
The expansion of tokenised payment infrastructure comes as financial institutions continue to examine ways of protecting customers’ payment credentials during electronic transactions.
Traditional card payments may involve the transmission or storage of sensitive information at different stages of processing.
Tokenisation can reduce the exposure of original card numbers by substituting them with identifiers that are subject to defined security controls.
This can help limit the consequences of certain forms of data compromise.
For financial institutions, tokenisation may also support improved transaction processing when combined with appropriate authentication and payment network systems.
Supporting contactless payments
For consumers, one potential application of tokenisation is the use of mobile devices and digital wallets for contactless payments.
Where the necessary infrastructure is available, customers can make eligible purchases by presenting a compatible card, phone or wearable device at a contactless terminal.
The process can reduce the need to enter card details manually for certain transactions.
For merchants, supporting these payment methods may provide customers with additional checkout options.
However, widespread adoption requires more than tokenisation infrastructure alone.
Banks must support the relevant payment products, merchants need compatible acceptance systems and consumers must have access to eligible cards or devices.
Transaction security, network reliability, customer education and the cost of deploying payment terminals can also influence adoption.
Interswitch said its work was intended to support these requirements by connecting participating institutions through its payments infrastructure.
The company has not announced a timetable for nationwide availability or specified when tokenised tap-to-pay services would become accessible to customers of particular banks.
Executive Vice-President, Marketing and Communications at Interswitch, Cherry Eromosele, said the company’s tokenisation activities formed part of its wider investment in payment infrastructure.
She described the initiative as an effort to improve the reliability and security of digital transactions for businesses and consumers.
Eromosele said Interswitch had spent more than two decades developing technology intended to support electronic payments across Africa.
According to her, the company’s approach focused on the systems that enable everyday transactions rather than individual product features alone.
The announcement reflects the growing attention being given to the underlying technology required to support digital financial services.
As more transactions move through electronic channels, payment providers face the challenge of improving convenience while maintaining security and reliable processing.
Tokenisation offers one approach to reducing the exposure of sensitive payment information, but its wider impact will depend on adoption by banks, merchants and consumers.
For Interswitch, the next measure of progress will be the extent to which its infrastructure translates into operational services, increased acceptance and demonstrable improvements in transaction security.