 Follow Us on Google News


 Follow Us on Google Discover
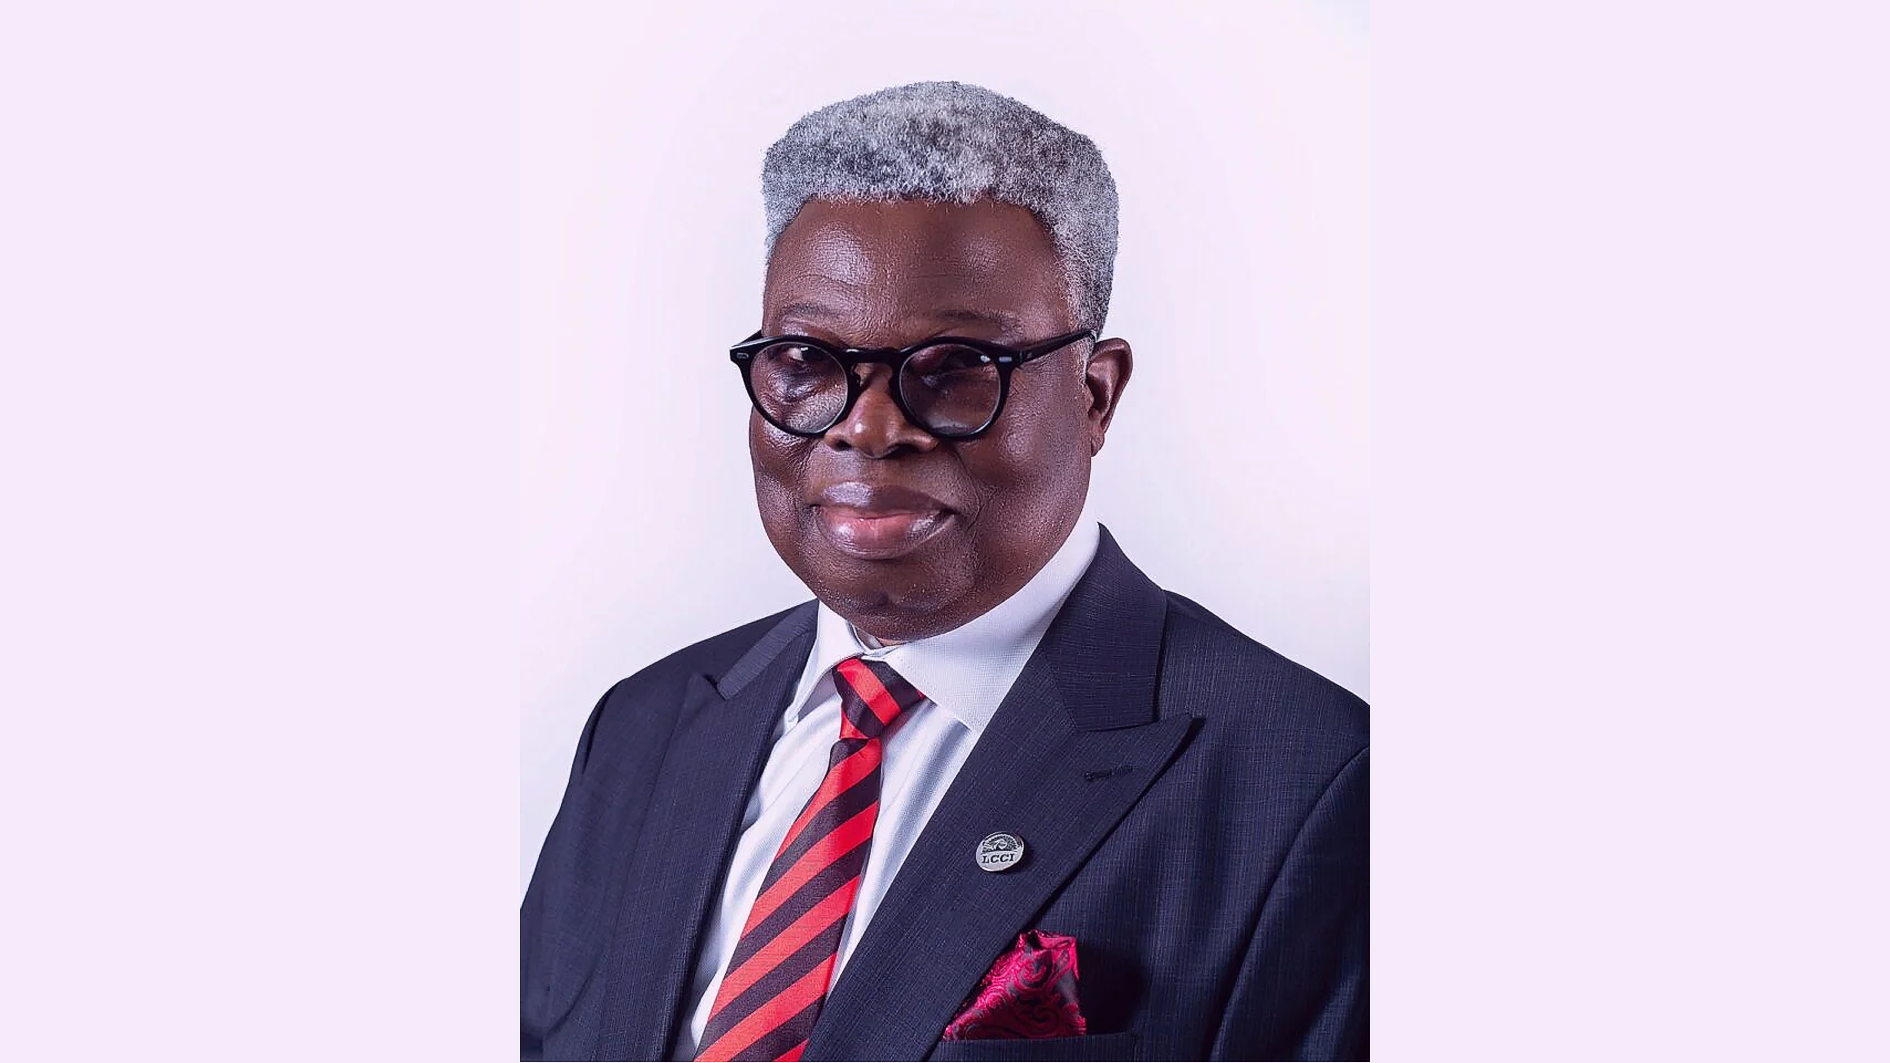
The Lagos Chamber of Commerce and Industry (LCCI) has warned that Nigeria’s rising public debt and mounting interest payments threaten private-sector investment, affordable credit and economic growth and urged the Tinubu-led Government to tackle structural constraints undermining businesses.
LCCI president, Leye Kupoluyi, who spoke at the chamber’s Q4 conference at Commerce House in Lagos yesterday, said any economic growth touted by the government must translate into broad-based prosperity through higher productivity, industrialisation, private investment and employment creation.
He said a growing economy does not automatically guarantee improved business performance, higher real incomes or sufficient employment, stressing the need to strengthen productive sectors, particularly manufacturing, agriculture, construction, logistics and export-oriented services.
According to him, the reforms can only become tangible when capital flows into productive projects that improve living standards and create jobs.
Lamenting the debt burden, which he said is crowding out credit to the private sector and placing additional pressure on them, he said Nigeria’s total public debt rose to N166.79 trillion by June 30, 2026, an increase of N14.39 trillion, or 9.4 per cent, from N152.40 trillion in June 2025.
He also stated that Nigeria’s interest payments increased to N7.7 trillion in H1 2026, from N5.6 trillion in the corresponding period of 2025, amid high domestic borrowing costs.
He warned that rising debt-servicing obligations are reflected in high interest rates and constraining public spending on infrastructure, electricity, transportation and other growth-enabling investments. He said it is also exposing public finances to exchange-rate risks, while the increasing cost of servicing domestic borrowing is making it harder for micro, small and medium enterprises (MSMEs) and manufacturers to access affordable financing.
He maintained that Nigeria’s economic recovery would remain fragile unless policymakers address the high cost of doing business and macroeconomic stabilisation translates into stronger production, improved household purchasing power and business expansion.
On inflation, Kupoluyi said the elevated cost of living remains a major concern, with households continuing to struggle with food, transportation, housing, energy and other essential expenses. He warned that sharp increases in petrol and diesel prices in Q3 and into Q4, pose renewed risks to the disinflation process, as higher energy costs feed into transportation, manufacturing, agriculture, distribution and retail prices.
He urged monetary and fiscal authorities to coordinate policies that sustain the moderation in inflation without unnecessarily constraining productive investment.
According to him, the government must go beyond efforts to slow the rate of price increases and tackle the structural factors driving inflation, including high logistics costs, inadequate infrastructure, insecurity in food-producing areas and excessive charges along domestic supply chains. He said the objective should be to moderate production costs, improve real incomes and make essential goods more affordable.
Identifying access to affordable credit as another major obstacle to private-sector expansion, he said many businesses, particularly MSMEs and manufacturers, continue to face financing costs that discourage investment, expansion and job creation.
He said the challenge is not merely whether banks have sufficient capital, but whether viable businesses could obtain loans at interest rates and repayment tenors that support productive investment.
As such, he called on monetary authorities, development finance institutions and commercial banks to strengthen credit delivery to the real sector, prioritising working capital, equipment acquisition, agricultural value chains, export-oriented manufacturing, technology adoption and SME expansion.
Reviewing business conditions in Q3, he identified rising energy costs, weak consumer demand, declining purchasing power, multiple taxation, expensive financing, infrastructure deficits, unreliable electricity, high logistics costs, insecurity and policy uncertainty as major constraints confronting enterprises.
He said higher petrol and diesel prices significantly increased the cost of operating generators, transporting goods, distributing products and providing essential services, compounding the burden of electricity tariffs and expenditure on alternative power generation.
Lamenting the issue of multiple taxation, overlapping regulatory requirements, administrative bottlenecks and charges imposed by different levels of government and public agencies, he said these practices raise compliance costs, create uncertainty and place formal businesses at a disadvantage, particularly when they are already struggling with high operating expenses.
He urged governments at all levels to harmonise business charges, eliminate duplicative levies, digitise tax administration and regulatory processes and simplify compliance requirements.
He also recommended a structured review of regulations that impose disproportionate costs on SMEs to encourage formalisation, investment and business expansion.
On logistics, Kupoluyi said congestion, cargo-clearance delays, inefficient port operations, multiple charges, inadequate roads and avoidable administrative bottlenecks continued to undermine the competitiveness of Nigerian businesses. These challenges, he said, are particularly costly for manufacturers, import-dependent businesses, exporters and companies operating across multiple states.
He called for accelerated port modernisation, improved cargo evacuation, better coordination among border and port agencies and the removal of unnecessary checkpoints and unofficial charges along major transport corridors.
He described trade facilitation as a national competitiveness priority, arguing that faster and more predictable movement of goods would reduce costs, improve working-capital efficiency and strengthen Nigeria’s position in regional and international markets.
He further raised concerns about policy uncertainty and implementation gaps, arguing that businesses need a more predictable operating environment to plan investments and expand production.