 Follow Us on Google News


 Follow Us on Google Discover
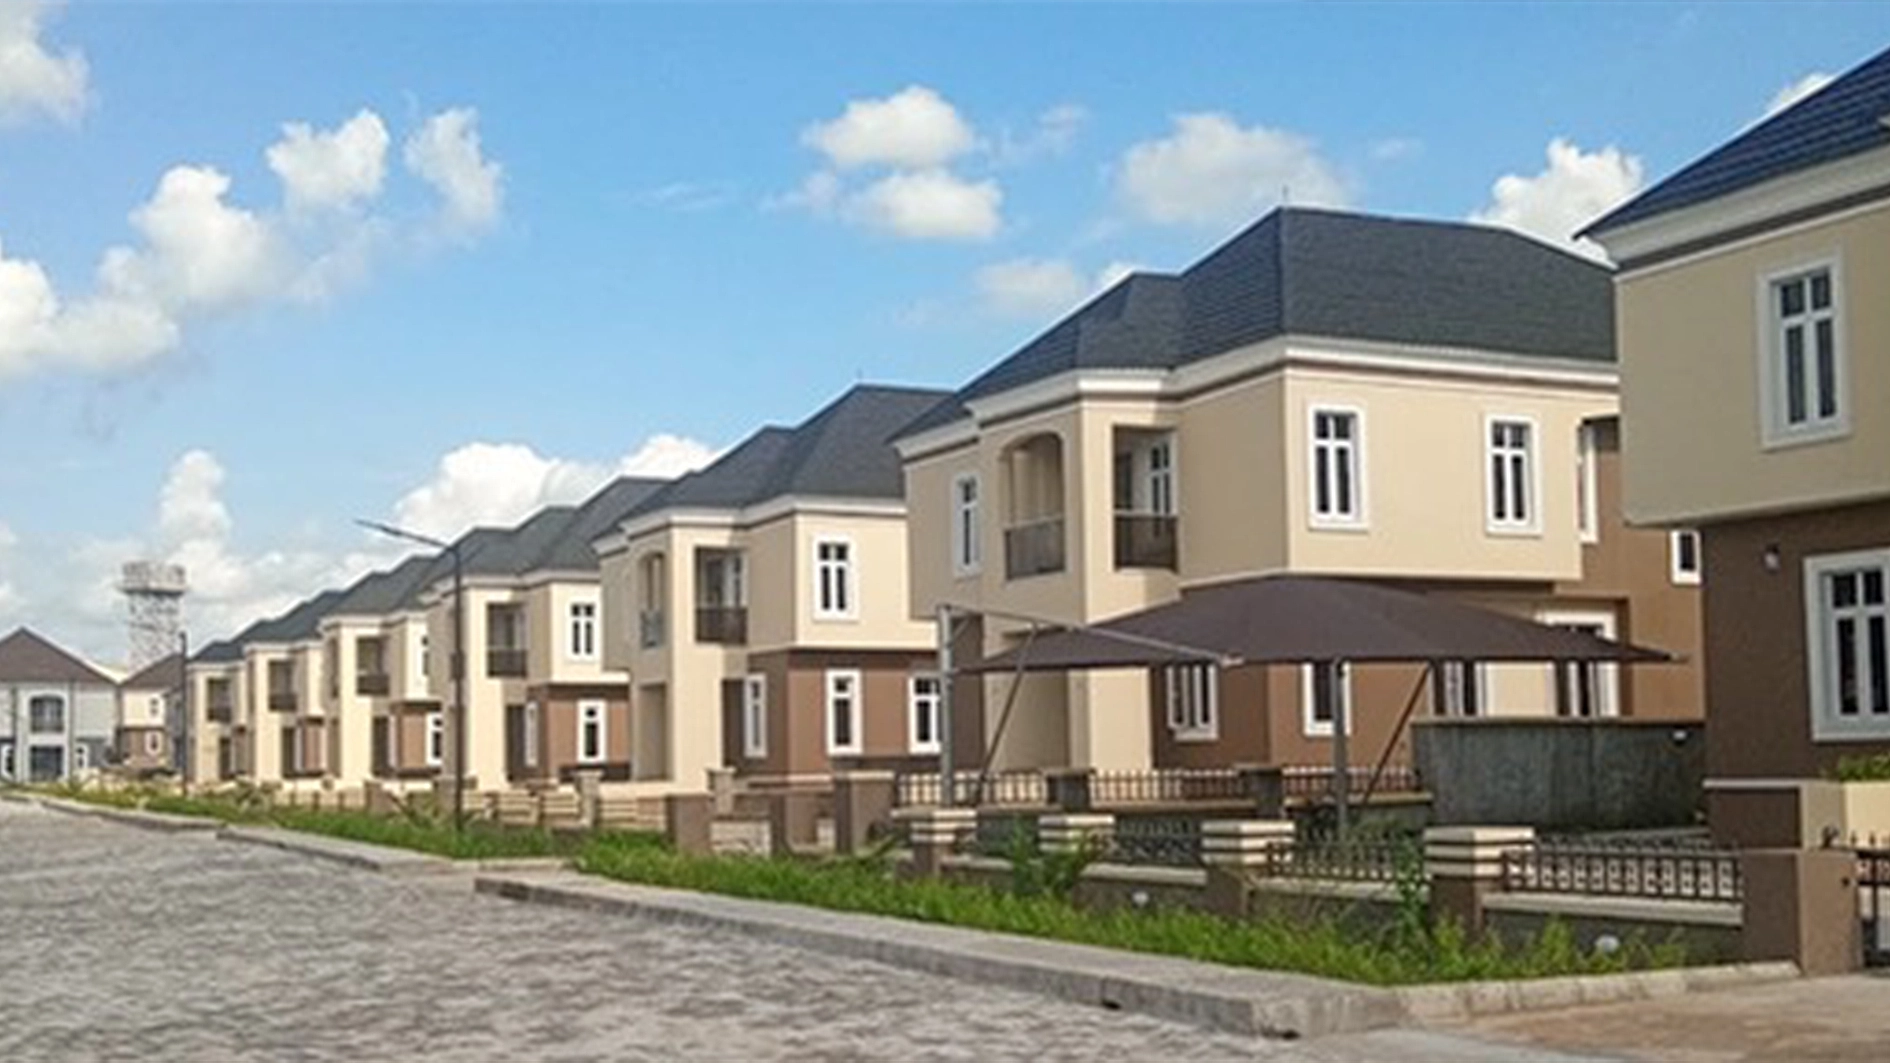
Knight Frank’s H1 2026 Lagos Market Update has identified a property market shaped by rising residential costs, infrastructure investment and increasingly selective occupier demand across Lagos, Abuja and Port Harcourt.
The report noted that Nigeria’s construction sector grew by 6.38 per cent year-on-year in the first quarter of 2026, while real estate accounted for 13.10 per cent of real GDP.
Although headline inflation eased to 15.91 per cent in June from 25.29 per cent a year earlier, affordability and development costs remain important considerations for investors, landlords and occupiers.
According to the report, in Lagos, residential rents continue to rise amid limited formal supply, particularly in prime locations, including Ikoyi, Victoria Island, Banana Island and Lekki Phase 1.
With some rents more than doubling since 2023, demand is also shifting towards more affordable studios, mini-flats and two-bedroom homes on the Mainland. Transport and road projects, including expansion of the rail network and improvements along the Lekki-Epe corridor, are reinforcing interest in growth areas, such as Ajah, Sangotedo and Ibeju-Lekki.
Commercial property demand is more selective as Grade A office rents have stabilised at about $55 per square metre monthly, with landlords increasingly offering fit-out contributions, concessions and flexible lease terms to attract tenants. In the industrial market, Grade A rents in Alaro City and Lagos Free Zone are reported at $4 6.5 per square metre monthly.
The report also noted that changes to the effective tax regime for free trade zones may influence investment decisions.
In Abuja, property values are rising in selected districts, with Guzape I and II recording reported increases of 20 to 30 per cent.
Prime districts, such as Maitama, Asokoro and Wuse 2, face saturation, encouraging regeneration and new supply. Diaspora investment remains an important driver, while affordability continues to be a concern. Commercial rents increased by more than 10 per cent in the first half of the year, supported by demand for quality office space and flexible work environments.
Port Harcourt’s market remains supported by the oil and gas sector, which underpins demand for premium housing, offices, hospitality and industrial facilities.
Residential demand is concentrated in established neighbourhoods, such as Old GRA, GRA Phases 1–3 and Peter Odili Road, alongside mid-market locations, including Rumuodara, Ada George and Eliozu.
For offices, tenants increasingly prioritise reliable power, lifts, parking, security and professional facilities management, leaving older buildings under pressure to refurbish or compete on price.
Senior Partner and Chief Executive Officer of Knight Frank Nigeria, Frank Okosun, said: “The market is showing resilience, but performance is increasingly location- and asset-specific. Infrastructure can unlock new opportunities, yet investors and developers must also respond to affordability pressures, operating costs and clearly demonstrated demand.”
Also, Lead Research Analyst, Daniel Fabi, said: “Across the three cities, occupiers are prioritising value and functionality. Quality offices and well-located industrial assets remain relevant, while residential demand is splitting between prime property and more affordable options. Understanding these differences is essential to sound investment decisions.”
Similarly, Head of Marketing and Corporate Communications, Lanre Sonubi, said: “The H1 2026 report provides market participants with a practical view of how infrastructure, changing occupier needs and affordability are shaping real estate opportunities. Our aim is to support clients with evidence-led insights as they assess risk, and position for growth across Nigeria’s key urban markets.”