 Get Guardian on Google
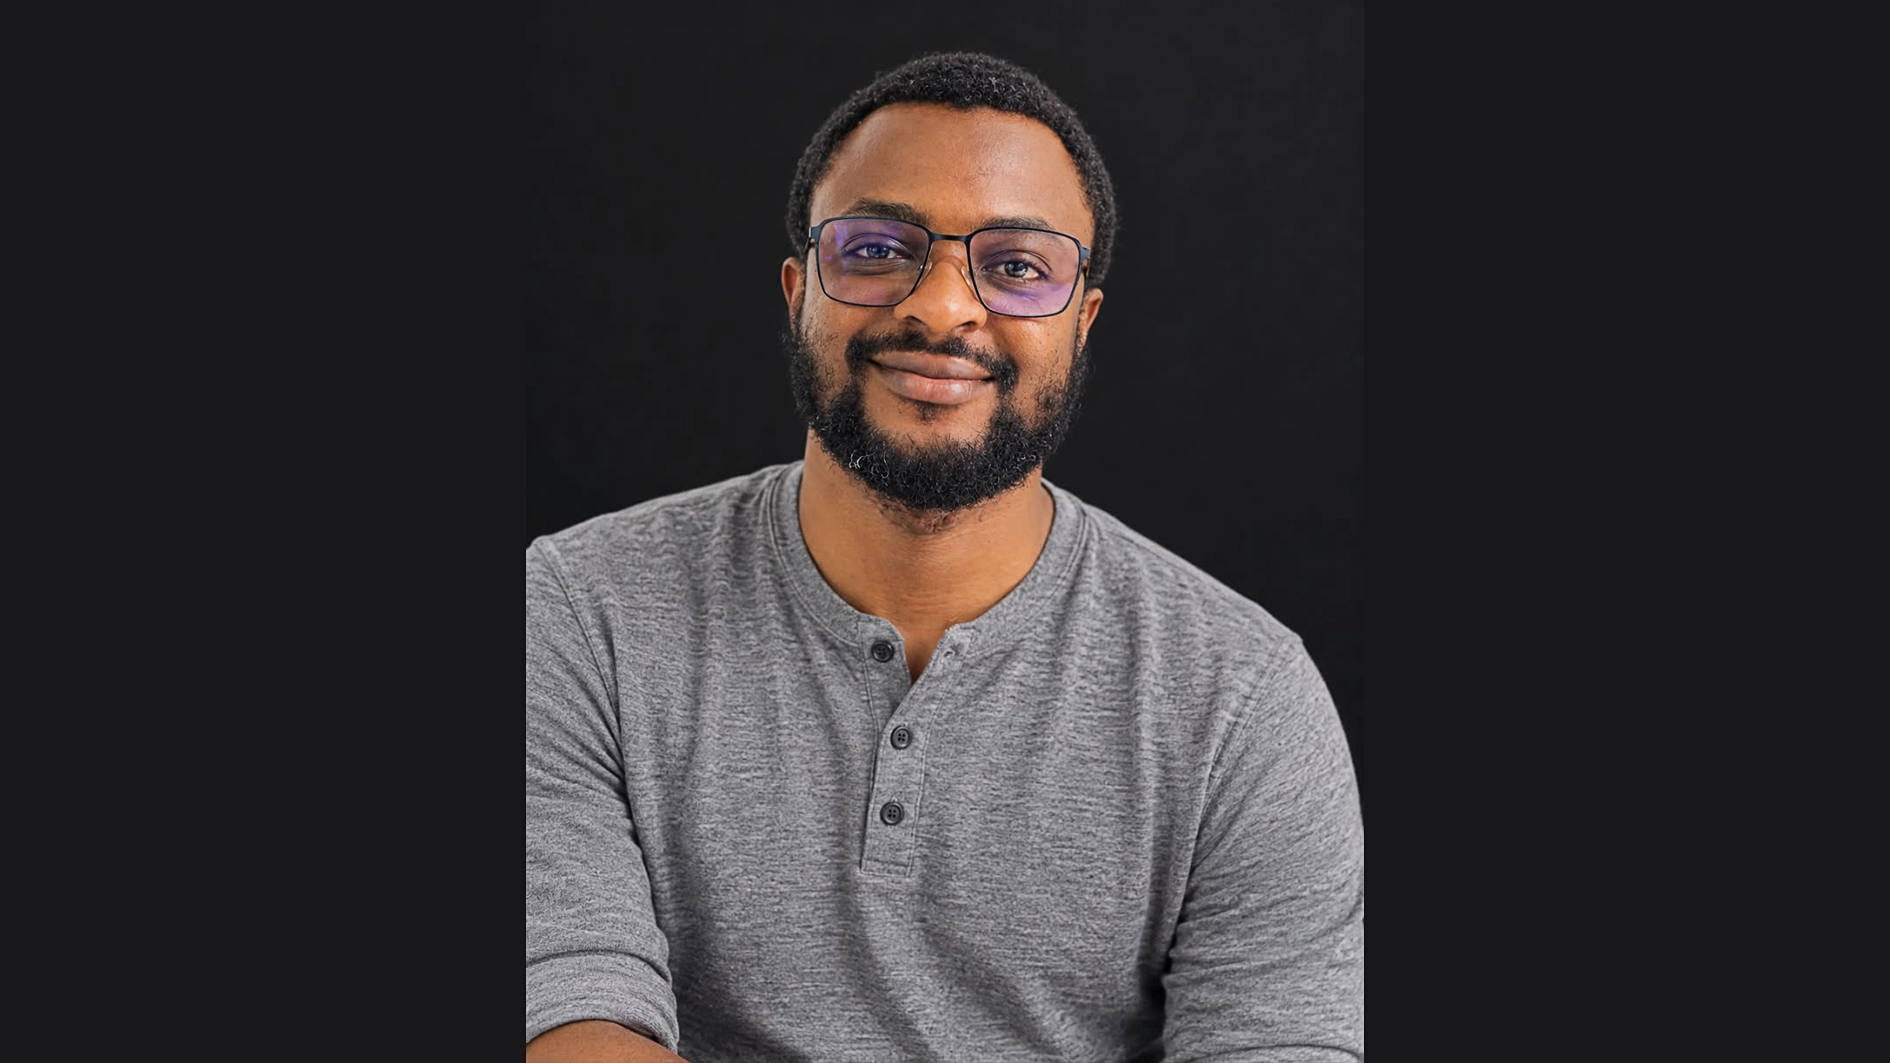
By Remi Adeoye
Nigeria has built one of the most active real-time payment systems in the world. Nearly 11 billion transactions moved through NIBSS Instant Payments in 2024, up from about five billion in 2022, with a combined value of more than N1 quadrillion. That is the product of banks, fintechs, regulators and engineers working, often imperfectly, in the same direction.
But volume is a flattering measure if trust does not keep pace. The question for the next phase is no longer whether Nigerians can pay digitally. It is whether they can rely on it every time. Almost everyone has a story: a debit with no value delivered, a transfer that hangs, a merchant still waiting for settlement. The recent joint framework from the CBN and the Nigerian Communications Commission on failed airtime, data and digital payment transactions shows that regulators see the same problem.
The unglamorous layer
Reliability is invisible when it works. Nobody celebrates a payout that arrives on time or a ledger that balances to the last kobo. So it attracts less funding, attention and prestige than a new product launch. Yet everything built on top of payments, including lending, savings, commerce and cross-border transfers, inherits its quality.
After twelve years building payment systems for Nigerian and African companies, I can say the hardest problems are rarely the headline features. They are retries, timeouts between systems, reconciliation across partners, and rules that change while the system is running. This is the work that decides whether a customer trusts a platform with their salary or only with small change.
A moving regulatory target
The rules are moving quickly. The CBN published a fintech policy report in February, the National Payment Stack has introduced the ISO 20022 messaging standard, and payment operators must keep locally generated transaction data inside Nigeria from January 2027. The direction is sensible: resilience, transparency and accountability for a sector now carrying huge value.
But compliance is also an engineering project, and smaller firms feel the burden first. A rule that takes a large institution one quarter to implement can take a start-up half a year of its scarce technical capacity. The February report’s proposals for a standing forum between regulator and industry are therefore encouraging, provided they lead to early technical consultation and not just announcements.
What should happen next
First, regulators can publish technical specifications early, set realistic timelines, provide test environments, and report outcomes the public can understand, such as failure rates and average refund times. What gets measured in public tends to improve.
Second, companies can treat reliability as a core product. That means investing in reconciliation, monitoring and honest incident reviews, and communicating clearly when things go wrong. Customers forgive an outage far more readily than silence.
Third, the country can value the people who build this infrastructure. Payments engineering and site reliability are strategic skills. Nigeria will keep its edge only if it trains, retains and rewards engineers who can run critical systems at scale, instead of watching them leave for markets that pay more for the same work.
Finally, customers have a role. Ask providers about refund timelines and complaint channels, and use the ones that answer plainly.
A better measure of success
The next decade of Nigerian fintech will not be judged by how many transactions it processes. It will be judged by how many succeed the first time, and how quickly the rest are put right. Novelty gets headlines, but reliability earns trust, and trust is what keeps a payments system growing.
Remi Adeoye is a software engineer with 12 years of experience building payments and financial infrastructure for fintech companies across Nigeria and Africa. He has worked on core payments systems, led product teams for enterprise disbursement and collection platforms, and helped break legacy monoliths into microservices. He writes on payments infrastructure, reliability engineering and technology leadership.