 Follow Us on Google News


 Follow Us on Google Discover
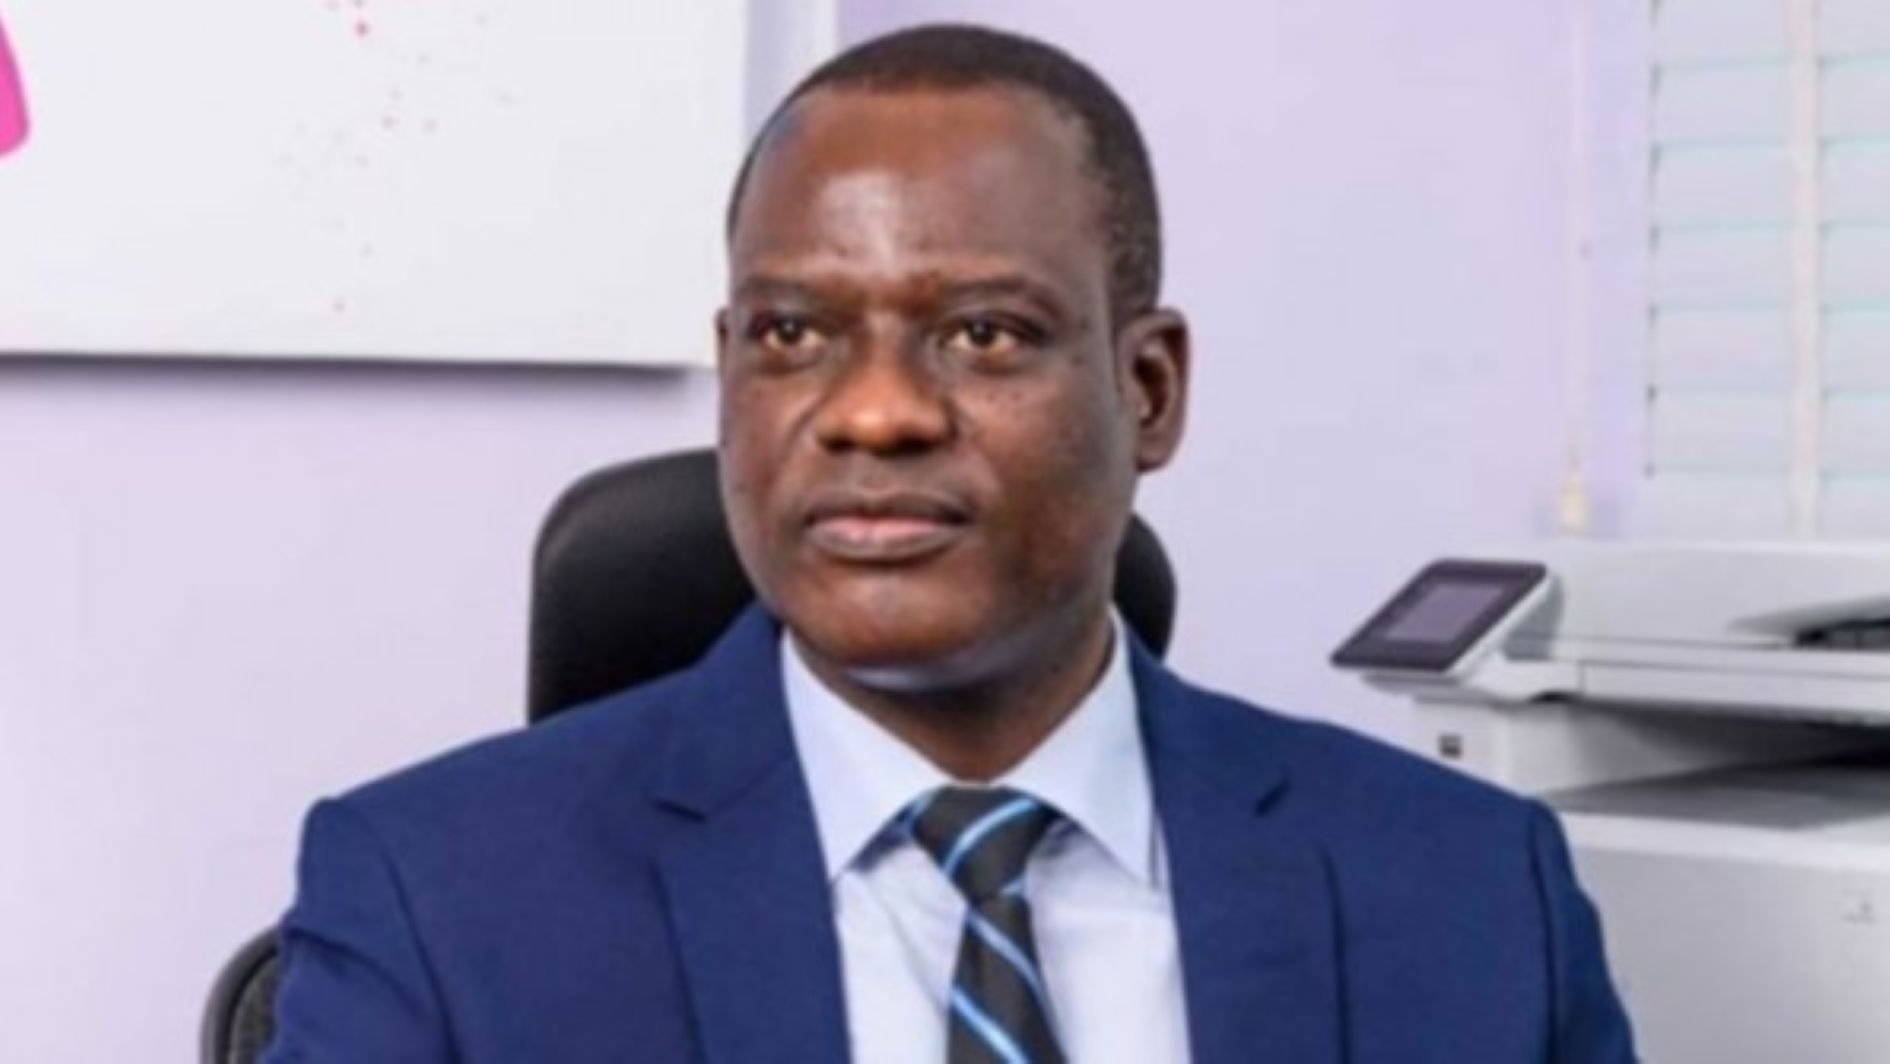
. NESG demands shift from reforms to jobs, lower production costs
The Federal Government is proposing mandatory impact assessments for major economic policy changes in a move to curb policy reversals, restore investor confidence and ensure government decisions translate into productive investment, decent jobs and higher household incomes.
Under the proposed Nigeria Economic Policy Framework unveiled by the Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, policymakers would be required to demonstrate the problem a proposed intervention seeks to solve, the evidence supporting it, who stands to benefit, who bears the cost and the conditions for ending the policy.
Oyedele announced the proposal at the 32nd Nigerian Economic Summit in Abuja yesterday. He warned that inconsistent policies and inadequate consultation have undermined investment, weakened business confidence and constrained economic growth.
According to him, “Our challenge has never been a shortage of ambition or good ideas. It has been the absence of an enduring economic philosophy, consistent policymaking, and disciplined implementation.”
Describing policy uncertainty as an invisible tax on businesses, the minister said the proposed framework was designed to establish enduring economic principles that would survive successive administrations, rather than become another development plan or the economic manifesto of a particular government.
The proposal comes as the private sector intensifies pressure on the government to move beyond macroeconomic stabilisation and demonstrate tangible improvements in productivity, employment, purchasing power and living standards following successive economic reforms.
On trade protection, Oyedele cautioned against using tariffs to shield inefficient businesses indefinitely from competition, saying trade policy should help local industries become competitive rather than entrench inefficiency.
“A tariff must serve as a runway for local industry to take off, never a permanent shelter from competition,” he said.
The draft framework will be opened for public consultation from November 27, 2026, with Nigerians invited to respond to 17 questions through the Federal Ministry of Finance’s website.
Following consultation and validation, the document is expected to proceed to the Federal Executive Council for approval and the National Economic Council for endorsement.
Oyedele said the government also planned to introduce an annual national economic scorecard, to be published on or before October 1, to track indicators including real wages, productive employment and poverty.
The scorecard is intended to shift the measurement of economic performance beyond aggregate GDP growth towards improvements in household incomes, employment opportunities and business productivity.
“GDP growth matters, but per capita income matters even more,” the minister said.
He identified enterprise as the engine of growth, open but fair markets and coordination across government institutions as the framework’s guiding principles.
President Bola Tinubu, while declaring the summit open, defended the administration’s reform programme, describing the removal of fuel subsidy and other difficult economic decisions as necessary to address longstanding structural distortions.
The President, who was represented by Vice-President Kashim Shettima, said the reforms were restoring confidence, strengthening the economy’s foundations and creating conditions for sustainable growth, but acknowledged that favourable economic statistics must translate into tangible prosperity.
According to him, Nigeria’s inflation-adjusted gross domestic product grew by 3.89 per cent in the first quarter of 2026, compared with 3.13 per cent in the corresponding period of 2025.
He also cited capital importation of $10.37 billion in the first quarter of 2026, representing an 83.83 per cent increase over the corresponding period of the previous year, as evidence of improving investor confidence.
Tinubu said the administration would continue to ease regulatory bottlenecks, strengthen transparency, improve policy predictability and expand access to finance while pursuing reforms across the energy, agriculture and solid minerals sectors.
Chairman of the Nigerian Economic Summit Group (NESG), Olaniyi Yusuf, said stabilisation alone could not guarantee economic prosperity, insisting that the next phase of reforms must focus on reducing production costs, improving infrastructure and expanding productive investment.
“Stabilisation creates the conditions for progress; it does not automatically deliver it,” Yusuf said.
He warned that a more stable exchange rate would not, by itself, make Nigerian manufacturers competitive, arguing that businesses still require reliable electricity, affordable financing, efficient transport infrastructure and predictable regulations to expand production and create jobs.
The summit, themed “Growth That Works: Delivering Jobs, Productivity and Shared Prosperity,” is seeking to forge a stronger partnership between government and businesses to translate economic reforms into measurable improvements in the lives of Nigerians.