 Follow Us on Google News


 Follow Us on Google Discover
As 38 per cent of planned upstream investments face break-even risks under a changing global energy outlook, experts say Nigeria must reconcile petroleum expansion with energy access, fiscal stability and environmental accountability. KINGSLEY JEREMIAH reports.
Nigeria’s ambition to expand oil and gas production while preparing for a lower-carbon energy future faces a fundamental problem. The country could commit billions of dollars to projects that fail to deliver expected returns, even as inadequate infrastructure prevents available energy resources from meeting domestic needs.
The dilemma places the Nigerian National Petroleum Company Limited (NNPCL) at the centre of a difficult economic balancing act. The company must support government revenue, energy security and industrial development while managing the risks of changing global demand, increasingly competitive renewable energy, and the environmental liabilities of petroleum production.
Last week in Abuja, experts from the Natural Resource Governance Institute (NRGI), the Centre for Energy, Finance and Development (CEFD), the Inclusive and Sustainable Development Research Centre (ISDRC) and the Centre for Petroleum, Energy Economics and Law (CPEEL) at the University of Ibadan estimated that 38 per cent of planned upstream investments involving Nigeria could fail to break even under the International Energy Agency’s Announced Pledges Scenario, raising concerns about stranded assets and potential losses to the economy.
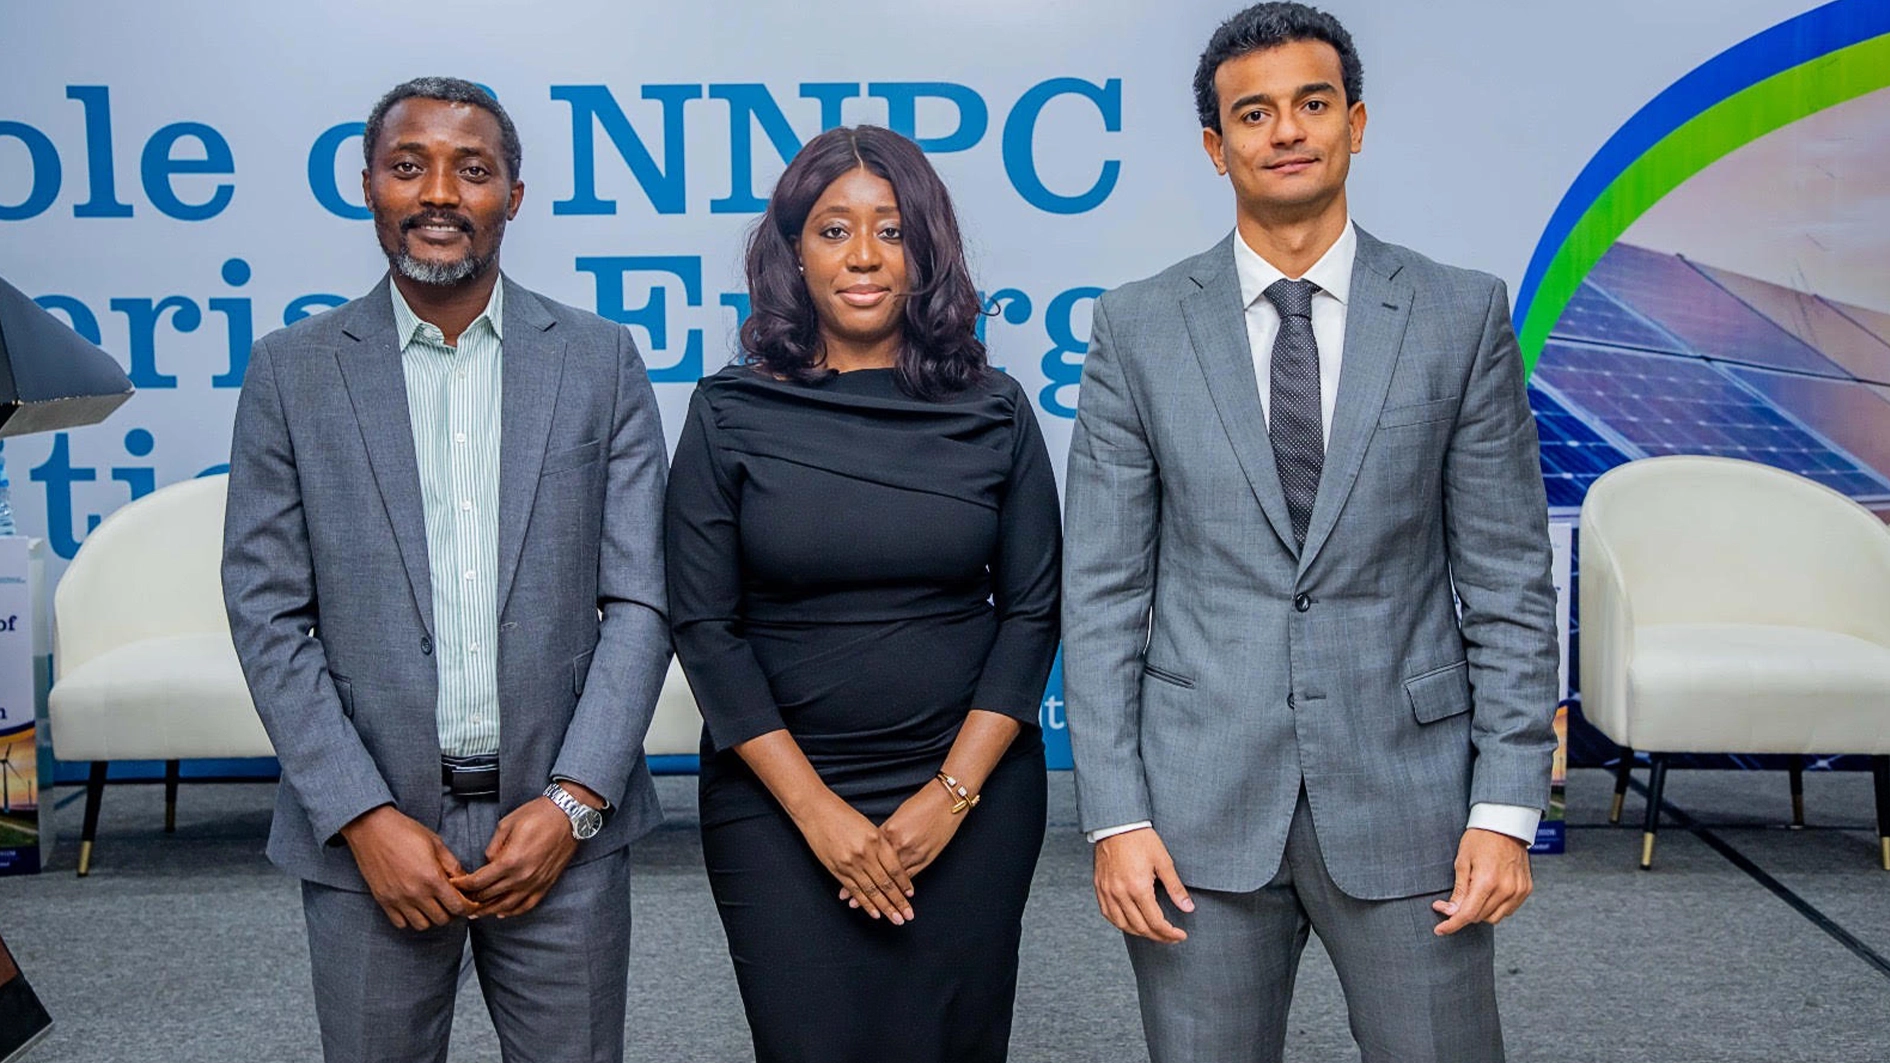
The Nigeria Country Manager of NRGI, Tengi George-Ikoli, disclosed this at a policy engagement on The Role of NNPC in Nigeria’s Energy Transition in Abuja. The event was organised by NRGI in collaboration with the Centre for Petroleum, Energy Economics and Law and the Centre for Energy, Finance and Development.
“For Nigeria, we have assessed that Nigeria is 38 per cent at risk of not being able to break even on those projects,” George-Ikoli said.
The assessment does not mean that 38 per cent of Nigeria’s existing petroleum assets will automatically become worthless. Rather, it signals the proportion of planned upstream investment exposed to break-even risks under a scenario aligned with countries implementing their announced climate commitments.
The commercial outcome will depend on production costs, commodity prices, demand, financing conditions and project timelines. Nevertheless, the warning highlights why Nigeria cannot assume that every investment in oil and gas will remain profitable throughout its operating life.
George-Ikoli urged the Federal Government to prioritise projects capable of delivering sustainable returns and contributing meaningfully to national development. She also called for publicly available sustainability plans and closer coordination between NNPC, the ministries responsible for finance and national planning, and other relevant institutions.
The underlying question is whether Nigeria’s petroleum investment strategy is adequately accounting for the risks of a changing energy market or continuing to rely on assumptions that may not hold over the decades required to recover major investments.
Business as usual could deepen Nigeria’s exposure
The challenge is particularly serious because petroleum revenues remain important to Nigeria’s public finances and foreign exchange earnings. A poorly managed transition could reduce investment, employment and government revenue before alternative industries are sufficiently developed to compensate.
However, continuing to invest without rigorous commercial assessment carries its own risks. If global demand weakens, export markets tighten, or production costs become uncompetitive, the country could be left with expensive infrastructure that fails to generate the returns needed to repay its costs.
George-Ikoli’s presentation, drawing on NRGI research, showed that national oil companies face substantial exposure to investments that may not break even under changing demand conditions. The institute argued that inaction could deepen hydrocarbon dependence when diversification is increasingly important.
The solution is not an indiscriminate withdrawal from petroleum. It is to assess each project against different oil and gas price assumptions, production costs, financing requirements and demand scenarios before committing public or company capital.
NNPCL should disclose the expected returns and principal risks of major investments, while the government should establish clear criteria for deciding which projects deserve funding, which require restructuring and which should be deferred or abandoned.
Such scrutiny is particularly important for long-lived infrastructure, where the financial consequences of poor decisions can persist long after the officials who approved them have left office.
NNPCL’s transition position remains unclear
Another problem is the gap between Nigeria’s stated energy transition objectives and the way NNPCL communicates its investment priorities.
Nigeria’s Energy Transition Plan, launched in 2022, targeted net-zero emissions by 2060. It identifies natural gas as a transition fuel while renewable energy expands and energy access improves.
Yet an NRGI analysis of 264 Nigerian media articles between January 2021 and March 2026 found that only seven per cent reflected NNPCL commitments classified as aligned with the transition plan. The institute classified 45 per cent as misaligned, five per cent as contradictory and 42 per cent as containing no discernible transition position.
The analysis assessed the company’s own statements and commitments, rather than independently measuring its entire investment portfolio. NRGI classified oil expansion and long-lived gas commitments without clear end dates as misaligned, while contradictory statements combined claims of transition leadership with commitments to expand fossil fuel activities.
These findings suggested that NNPCL has yet to articulate a sufficiently consistent public account of how its petroleum investments will coexist with its long-term transition objectives.
The solution is to translate the national plan into measurable company-level targets, including emissions reductions, methane control, gas-flaring elimination, renewable energy investment and transparent capital-allocation milestones.
The Federal Government must set the direction rather than leave NNPCL to define its own ambitions without clear accountability. The company should then report regularly on progress and explain how its investment decisions support national energy access, industrial development and environmental objectives.
Gas expansion faces a domestic demand problem
Natural gas presents another major test of Nigeria’s strategy. The country has set production targets of 10 billion cubic feet per day by 2027 and 12 billion cubic feet per day by 2030.
However, projections cited in NRGI’s presentation, Nigeria’s Decade of Gas at Midpoint: Progress, Gaps and the Path Forward, suggest that projects already producing or having reached final investment decisions could add only about 1.3 billion cubic feet daily above the 2020 baseline by 2030. This is less than a third of the additional 4.6 billion cubic feet required to meet the stated ambition.
Even if production increases, the benefits will depend on whether Nigeria can develop reliable markets and infrastructure to transport and consume the gas.
The NRGI presentation indicated that between 60 and 80 per cent of production from selected new projects was earmarked for export markets. Exports can generate foreign exchange, but an export-heavy strategy raises questions about whether sufficient gas will be available to support domestic power generation, manufacturing and industrialisation.
The problem is compounded by weaknesses in the electricity value chain. According to figures presented by NRGI, gas-fired generators received substantially less fuel than required for full-capacity operations.
The presentation also put grid transfer capability at approximately five gigawatts against more than 13 gigawatts of installed capacity, while gas-bill payment performance by generators stood at about 40 per cent in 2024.
These figures expose a structural problem: gas production, pipelines, power plants, transmission infrastructure and payment arrangements are interdependent. If any part of the chain fails, investments elsewhere may become commercially unattractive.
The solution is to appraise gas projects as integrated systems. Before approving pipelines and new production facilities, NNPCL and its partners should establish firm buyers, binding offtake agreements, realistic utilisation forecasts and credible payment arrangements.
The company must also test whether proposed pipelines can achieve adequate throughput and whether gas-fired power investments will remain competitive as renewable energy and storage technologies improve.
Commercial reform must go beyond the PIA
The Executive Director of the Centre for Energy, Finance and Development (CEFD), Nicolas Lippolis, examined how NNPCL’s commercial decisions should respond to changes in global demand, domestic energy technologies and the company’s post-Petroleum Industry Act governance structure.
Lippolis’s presentation distinguished between decarbonising NNPCL’s existing oil and gas operations and diversifying into new energy businesses. The former involves reducing methane emissions and gas flaring, improving efficiency and considering electrification and carbon capture. The latter involves developing businesses in renewable power, biofuels, energy storage, electric-vehicle charging and other low-carbon services.
The distinction matters because reducing emissions from existing petroleum operations does not, by itself, reduce the company’s long-term dependence on oil and gas revenues. Conversely, investing in renewable energy does not automatically make a project commercially viable.
Lippolis’s analysis noted that in 2022, major international oil companies allocated an average of about 15 per cent of capital investment to energy transition and low-carbon activities, compared with less than five per cent among the national oil companies covered by the cited Wood Mackenzie estimates. The presentation also observed that, by 2026, low-carbon spending among national oil companies had increased relative to European majors following the latter’s strategic recalibration.
The figures showed that transition investment is not following a single global trajectory. For Nigeria, the implication is that NNPCL needs a strategy based on its own commercial strengths and national priorities rather than simply copying international companies.
Lippolis’s presentation also warned that corporatisation under the Petroleum Industry Act does not necessarily translate into effective reform. Commercial autonomy must be matched by stronger board oversight, independent audits, clear performance indicators and disclosure of capital allocation.
Government should specify the public objectives NNPCL must deliver, disclose the costs of non-commercial obligations and distinguish them from investments expected to generate commercial returns.
NNPCL should also clarify how executive rewards will be tied to measurable sustainability outcomes, including emissions reductions, environmental performance and progress in developing new energy businesses.
Diversification must be phased and commercially justified
The economic consequences of changing NNPCL’s investment strategy also require careful consideration.
A researcher at the Centre for Petroleum, Energy Economics and Law, University of Ibadan, and director of the Inclusive and Sustainable Development Research Centre, Oluwasola Omoju, presented an economy-wide analysis of three scenarios: reducing investment in oil and gas, shifting investment from crude oil to natural gas, and investing in technologies to capture or reduce gas flaring.
Using a computable general equilibrium model, Omoju found that all three strategies had negative economic effects relative to the business-as-usual baseline, with divestment and shifting investment towards natural gas producing larger negative effects.
The results highlighted the potential costs of poorly sequenced changes in an economy that depends on petroleum for revenue, exports, investment and employment. They do not establish that maintaining existing investment levels is necessarily the best long-term option, because the findings depend on the model’s assumptions and the baseline against which the scenarios were assessed.
The appropriate response is to diversify gradually while protecting commercially viable petroleum operations and directing investment towards alternative businesses with demonstrable demand.
Lippolis proposed solar power for NNPCL’s own facilities as a starting point for reducing electricity costs and improving reliability. It also recommended partnerships with solar developers serving businesses with clear energy needs and credible payment arrangements.
Electric-vehicle charging could be piloted at selected NNPCL retail stations where demand justifies the investment. Biofuels projects would require dependable feedstock supplies, enforceable domestic blending requirements or committed export buyers.
The principle is to start small, measure costs and returns, and expand only when projects demonstrate commercial viability. NNPCL should invest directly where it has a clear operating advantage, partner where specialist expertise is required and use pilot projects where market demand remains uncertain.
Environmental liabilities and communities cannot be ignored
A Credible transition must also address the environmental costs of petroleum production.
George-Ikoli warned that pollution and liabilities associated with petroleum operations, including assets relinquished by international oil companies, must not be transferred to host communities.
Without adequate decommissioning funds, transparent liability assessments and enforceable remediation obligations, communities could be left with polluted land and water after operators withdraw.
The solution requires environmental liabilities to be assessed and funded before assets change ownership, with clear disclosure of who will pay for restoration. Workers also need retraining and social protection, while oil-producing communities require investment in alternative economic activities.
Ultimately, Nigeria’s energy transition is not simply a debate about producing more oil and gas or investing in renewables. It is a question of how to protect public revenue, secure affordable energy, prevent stranded investments and build new sources of economic value.
George-Ikoli’s warning on investment risks, Omoju’s analysis of economy-wide effects and Lippolis’s emphasis on commercial discipline point to the same challenge. Nigeria needs a transition strategy grounded in evidence, transparent governance and realistic market assessments.
The Federal Government must set measurable objectives, NNPCL must subject investments to rigorous downside testing, and gas and renewable projects must be developed around credible demand.
Without these changes, Nigeria risks committing scarce resources to projects that may fail to deliver their promised returns while leaving domestic consumers without the reliable, affordable energy needed for economic development.