
 Get Guardian on Google
Nigeria’s sustainable development ambitions may be undermined by low insurance penetration, as inadequate risk protection leaves households, businesses and critical investments exposed to financial losses, industry stakeholders have warned.
The warning comes amid the ongoing efforts to strengthen the financial capacity of insurance companies through recapitalisation, with stakeholders insisting that the exercise must translate into wider coverage, improved claims settlement and greater public confidence rather than merely higher capital bases.
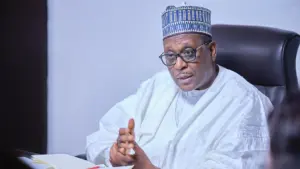
The former African Development Bank (AfDB) President, Dr Akinwumi Adesina, who spoke at the just-concluded 2026 Insurance Companies Directors’ Conference, organised by the College of Insurance and Financial Management, in Lagos, at the weekend, identified public trust, enforcement of compulsory insurance and innovation as critical to expanding the market, noting that insurance penetration remains below one per cent.
He stressed that the industry must move beyond strengthening its capital base to improving service delivery and extending protection to millions of Nigerians who remain outside the formal insurance system.
Adesina, who was also named Insurance Ambassador at the conference, challenged the industry to expand coverage among more than 100 million Nigerians who have never owned an insurance policy, saying that market development should be measured not only by premium growth but also by the number of people and businesses protected.
He said the implementation of the Nigerian Insurance Industry Reform Act (NIIRA) 2025 and the recapitalisation exercise had provided the sector with a stronger foundation, but operators must demonstrate their relevance by improving consumer protection and developing innovative products.
The former AfDB President also called for stronger enforcement of compulsory insurance policies, noting that compliance with the six compulsory classes remains below 30 per cent.
According to him, greater collaboration among insurers, government agencies and law enforcement authorities is necessary to improve compliance, protect lives, safeguard public assets and expand the insurance market.
Earlier, Chairman of the Nigerian Insurers Association (NIA), Ebelechukwu Nwachukwu, identified low penetration as a major challenge facing the industry, warning that stronger capitalisation alone would not deliver meaningful market expansion.
Nwachukwu, while speaking at a pre-investiture media engagement in Lagos, called for strategic partnerships with banks, Fintech companies, microfinance institutions, and non-financial platforms to improve distribution and reach underserved individuals and businesses.
She said that digital channels and strategic alliances could help insurers extend their products to millions of Nigerians and small businesses currently excluded from insurance coverage.
The NIA chairman identified public understanding and confidence as essential to increasing adoption, noting that distrust often stems from inadequate knowledge of insurance benefits and concerns about claims settlement.
She said that simplifying policy language, improving claims processes, and providing practical examples of how insurance protects policyholders would help rebuild confidence and encourage wider coverage.
Nwachukwu, therefore, pledged stronger collaboration with regulators and government institutions to support the implementation of NIIRA 2025 and promote a more competitive and inclusive insurance industry.
Also commenting on yesterday’s development, a former Chief Executive Officer of FSL Insurance Brokers Limited, Alfred Daudu, said that low insurance penetration leaves households, businesses and communities vulnerable to financial shocks arising from accidents, fire outbreaks, natural disasters, health emergencies and other unforeseen events.