 Follow Us on Google News


 Follow Us on Google Discover
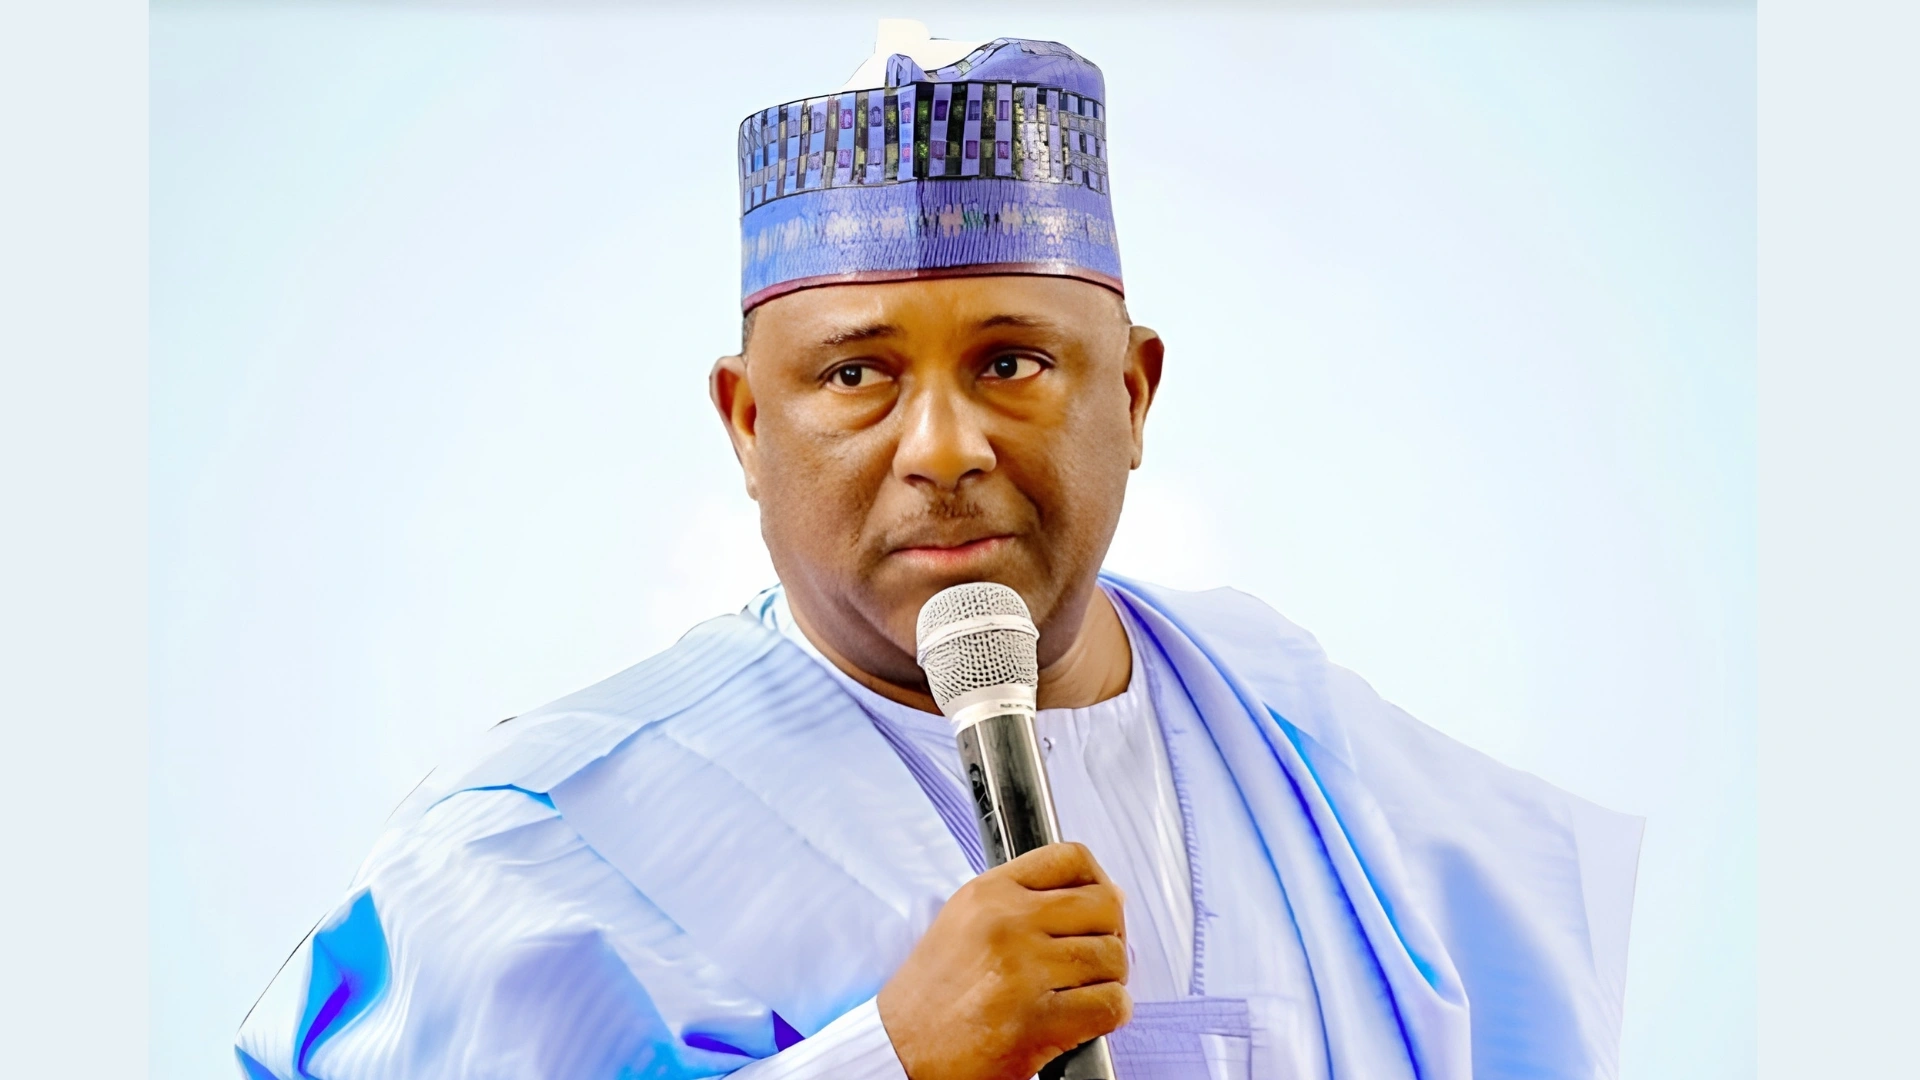
The Founder and Executive Chairman of BUA Group, Abdul Samad Rabiu, has commended President Bola Tinubu’s economic reforms for improving Nigeria’s investment environment, particularly access to foreign exchange.
This comes as BUA Group advances major industrial expansion projects expected to double production capacity across key food manufacturing operations by 2027.
He further challenged Nigeria to create the conditions for no fewer than 100 more major indigenous industrial enterprises capable of investing across manufacturing, agriculture, mining, technology and other productive sectors.
Rabiu, in his keynote address at the 32nd Nigerian Economic Summit Group (NESG) in Abuja, said the progress achieved through the reforms must now be translated into increased industrial production, job creation and improved living standards for Nigerians.
Speaking on the theme, “Growth That Works: Building a New Economic Accord for Nigeria,” he acknowledged the administration’s foreign exchange reforms, removal of petrol subsidies, fiscal and tax reforms, banking sector strengthening and infrastructure investments, noting that these measures were beginning to address longstanding constraints to business growth.
According to him, the ability to access foreign exchange through a functioning market has brought greater predictability to investment planning, particularly for manufacturers undertaking large-scale projects.
While acknowledging the difficulties that households and businesses continue to face, Rabiu urged sustained commitment to the reforms, with greater emphasis on expanding Nigeria’s productive capacity.
Meanwhile, highlighting the group’s industrial growth, Rabiu disclosed that BUA Foods and BUA Cement, both listed on the Nigerian Exchange, now have a combined market capitalisation exceeding $17 billion, with BUA Foods valued at over $10 billion and BUA Cement at approximately $7 billion.
He also outlined ongoing investments across flour milling, pasta, noodles, edible oils, rice milling and feed mills, with projects expected to be completed in 2027 and double production capacity.
Nevertheless, Rabiu identified access to affordable long-term capital as a major obstacle to industrial expansion, noting that large manufacturing investments often require 10 to 20 years to realise their full potential.
To that end, Rabiu called for greater mobilisation of financing from banks, pension funds, insurance companies, development finance institutions and capital markets to support productive investments, alongside sustained policy stability and infrastructure development.
Rabiu further called for a new economic accord between government, businesses and citizens, anchored on policy stability, productive investment, human capital development, access to long-term capital and shared prosperity.
Moreover, he urged Nigerian businesses to take advantage of the opportunities under the African Continental Free Trade Area (AfCFTA), stressing that Nigeria’s industrial future must include greater participation in regional and international markets.