 Follow Us on Google News


 Follow Us on Google Discover
Africa’s growing financial technology sector is facing mounting challenges from regulatory uncertainty and fragmented financial infrastructure, as fintech companies struggle to expand payment services across markets operating under different financial systems and regulatory frameworks.
The challenges have exposed gaps in the infrastructure needed to support cross-border transactions, customer verification and regulatory compliance, increasing the cost of expansion for technology businesses seeking to operate beyond their domestic markets.
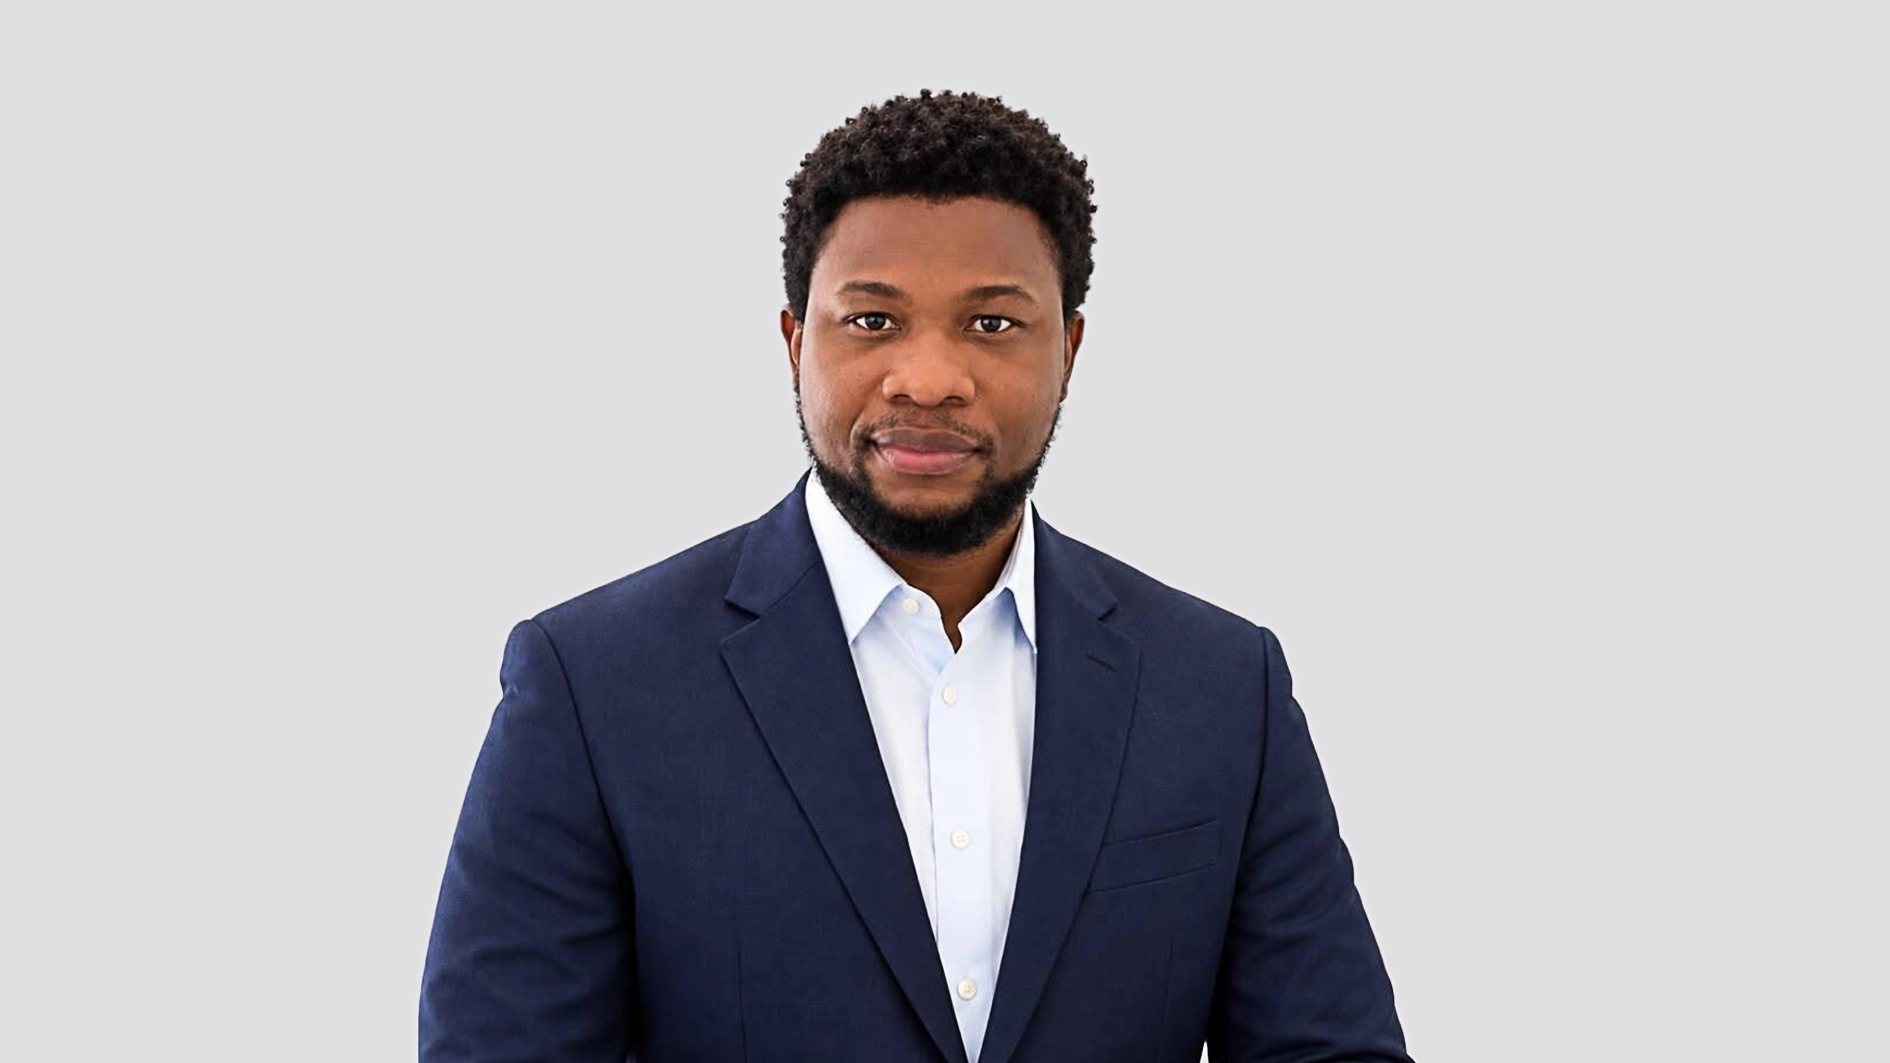
One of those drawing attention to the challenges is Charles Olanrewaju, Head of Operations at Ivorypay, a financial technology company developing cryptocurrency and stablecoin payment solutions for African markets.
Olanrewaju’s work across business operations, strategic partnerships and digital payment product delivery has centred on addressing the operational difficulties associated with building and expanding financial technology services in Africa.
Although the continent is frequently described as a single growth market, fintech companies expanding across national borders often encounter different licensing requirements, banking relationships, identity-verification systems and payment infrastructure.
The differences mean that businesses seeking to introduce the same product in multiple countries may need to develop separate compliance procedures, customer onboarding processes and transaction settlement arrangements for each market.
For early-stage companies, these requirements increase operating costs and divert resources from product development towards adapting existing systems to local conditions.
The difficulties are particularly pronounced in cryptocurrency and stablecoin payments, where regulatory frameworks remain relatively new in several African markets and continue to evolve.
Nigeria’s digital asset sector has experienced significant regulatory changes in recent years, reflecting efforts to strengthen oversight of cryptocurrency-related activities while addressing concerns surrounding financial stability, consumer protection and compliance.
The developments have increased the importance of payment systems capable of connecting digital assets with conventional financial infrastructure without exposing businesses to unnecessary regulatory and operational risks.
For Olanrewaju, the limitations of Africa’s financial infrastructure extend beyond differences in regulation to the operational systems required to make payment products work across markets.
A platform developed for one country may require different banking integrations, identity-verification procedures, settlement arrangements and customer support processes before it can operate effectively elsewhere.
The absence of common standards also creates challenges for companies attempting to reconcile transactions, monitor payment activity and maintain consistent financial controls across multiple jurisdictions.
These are among the challenges Olanrewaju has encountered through his work at Ivorypay, where he joined the founding team in 2022 and has contributed to the company’s operational development, commercial growth and strategic partnerships. His responsibilities have included facilitating Ivorypay’s partnership with stablecoin issuer Tether in April 2024 and its engagement with Hedera, which made a strategic investment in March 2025, as well as coordinating the delivery of Duffle, a consumer cryptocurrency payment application launched in Nigeria in April 2025. Ivorypay reported processing more than $80 million in cryptocurrency payments over the preceding year and onboarding over 9,000 merchants across several African markets by the time of Duffle’s launch, with Olanrewaju involved in commercial and operational initiatives supporting the company’s growth.
The experience has highlighted the importance of developing operational systems alongside financial products, particularly where businesses depend on multiple payment providers, banking partners and compliance requirements.
Olanrewaju identified risk management, structured financial controls and coordination between product, engineering and compliance teams as important requirements for fintech companies operating in such environments.
During the development of Duffle, the project team used a live risk register to monitor potential operational challenges, assign responsibilities and track mitigation measures, alongside a delivery approach combining structured compliance planning with shorter product development cycles.
The application enables cryptocurrency users to make payments through bank transfers and mobile money, connecting digital assets to conventional payment channels without requiring receiving merchants to integrate cryptocurrency payment systems.
Its Nigerian launch in April 2025 reflected the growing interest in making digital assets usable for everyday transactions, beyond cryptocurrency trading and investment.
But while payment applications are helping connect digital currencies to existing financial networks, differences in local regulation and infrastructure remain obstacles to wider regional expansion.
Olanrewaju believes fintech businesses need to distinguish between the technology that can be shared across markets and the operational arrangements that must be adapted to local requirements.
“The product can be shared, but the operation underneath it cannot,” he said.
Under such an approach, companies could maintain common transaction ledgers, risk policies and performance measurements while adapting customer onboarding, payment methods, banking partnerships and support services to individual markets.
The need for reliable operational systems becomes more significant as fintech companies grow, particularly when increasing transaction volumes place greater demands on financial reconciliation, customer support and regulatory reporting.
Unreconciled transactions, failed customer onboarding, delays in settlement and excessive dependence on individual banking partners can create vulnerabilities that become difficult to manage as businesses expand.
Automating high-volume and rules-based activities could help address some of these difficulties, although decisions involving significant financial consequences or unusual circumstances would still require human oversight.
“My short version: automate the rule, keep a person on the exception,” Olanrewaju said.
Automated transaction reconciliation, technology-enabled regulatory compliance and artificial intelligence-assisted operations are among the systems expected to play an increasing role in helping fintech businesses manage complexity.
Beyond payment processing, gaps in digital identity and verification infrastructure present another challenge for technology-driven businesses across Africa.
Many organisations continue to rely on telephone calls, emails, letters and physical documentation to verify identities, employment records and qualifications, creating delays and requiring businesses to repeat checks that could otherwise be completed through secure digital systems.
The limitations have informed Olanrewaju’s work on VERAYO, an artificial intelligence-powered employment verification platform being developed to simplify employment history checks and aspects of hiring and onboarding, initially targeting the United Kingdom and Nigeria.
The development of reusable verification systems could help reduce administrative costs and improve trust between businesses and individuals, provided that appropriate consent, security and data protection measures are maintained.
For African fintech companies, the broader challenge remains the absence of sufficiently connected financial and regulatory infrastructure to support efficient operations across national borders.
Addressing the gaps would require greater cooperation among regulators, banks, payment providers and technology companies, alongside investment in digital identity, transaction settlement and regulatory technology.
Olanrewaju maintained that sustainable fintech expansion would depend not only on developing innovative financial products but also on building the operational infrastructure needed to support those products reliably across different markets.